

- Industrial location is the spatial outcome of countless decisions by firms, states and workers. Each works within technological, economic, social and environmental limits.
- Industries are not set up at random. Each firm looks for the site that minimises costs or maximises profit.
- The result is a highly uneven industrial landscape:
- dense cores of diversified manufacturing and advanced services;
- specialised export enclaves;
- peripheral regions with fragile, resource-dependent activity.
- Economic geography studies where industries locate, why they shift, and what problems arise in old and new industrial areas. The answers feed directly into industrial and regional policy.
Industrial Location: Factors and Theory

Factors Affecting the Location of Industries
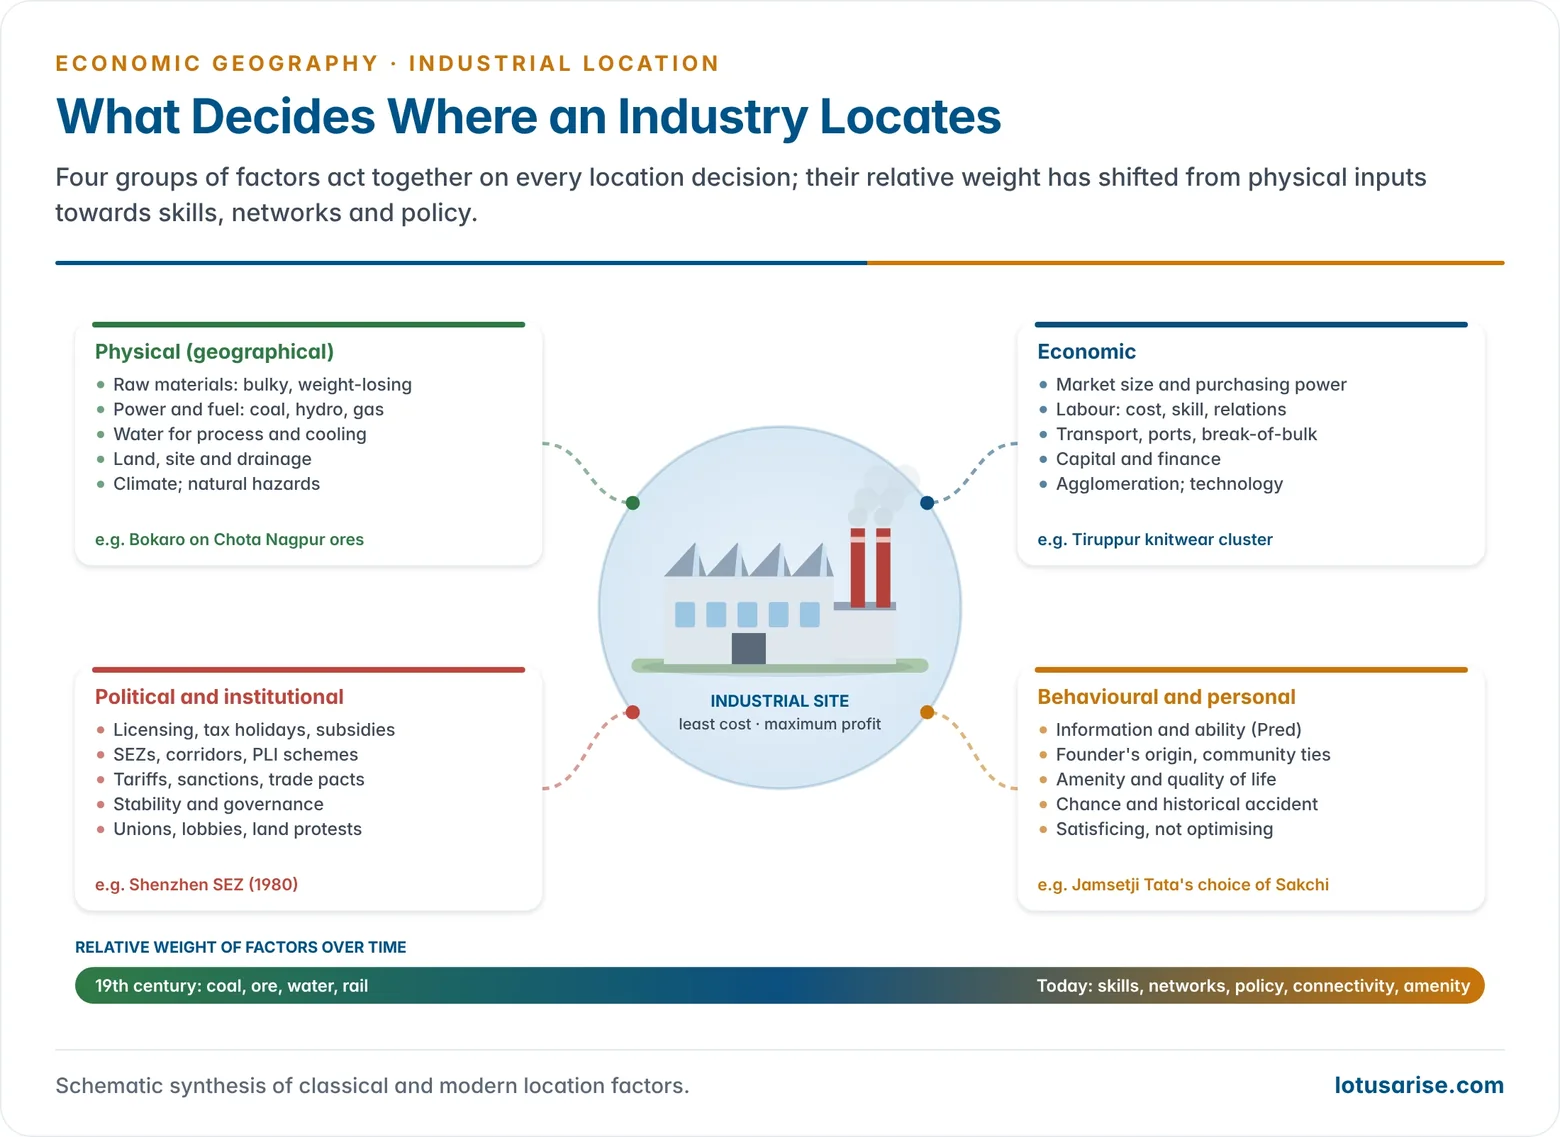
- The factors fall into four groups: physical (geographical), economic, political–institutional and behavioural. Their relative weight changes with technology and with the type of industry.
Physical (Geographical) Factors
- Raw material base: industries using bulky, weight-losing or perishable inputs locate near the source to save transport costs.
- Examples: the iron and steel plants of Bokaro, Rourkela and Bhilai on the Chota Nagpur ores; sugar mills in cane belts; cement, brick, jute, food processing and smelting.
- Power and fuel: cheap, reliable energy draws power-hungry industries.
- Early industry clung to coalfields (Ruhr, Pittsburgh, Damodar valley).
- Aluminium smelting still follows cheap electricity: hydropower in Norway, Quebec and Iceland, coal power in Inner Mongolia and Xinjiang, gas in the Gulf, coal in Odisha.
- Water: needed in bulk for steel, textiles, paper, chemicals and thermal power.
- Water-intensive units in arid regions (Rajasthan, Pakistan, the Middle East) face shortages.
- Land and site: flat, well-drained, affordable land with room to expand. Rising urban land prices push large plants to the fringe.
- Climate: once decisive for cotton spinning in humid Lancashire and Mumbai. Air conditioning has reduced its role, though precision industries still prefer clean, dust-free sites.
- Natural hazards (earthquakes, cyclones, floods) raise risk and insurance costs.
Economic Factors
- Market proximity: industries making weight-gaining, fragile or perishable goods locate near large markets with high purchasing power.
- Examples: bottled drinks, bakery products, furniture and printing.
- India’s large middle-class market attracts global consumer-goods and automobile firms.
- Labour: two aspects matter, its cost and its skill.
- Cheap labour draws labour-intensive industries: garments in Bangladesh and Vietnam.
- Skilled labour anchors high-tech sectors: Bengaluru, Silicon Valley, Hsinchu.
- Labour relations (strong unions, strike risk) and labour laws also weigh in the decision.
- Transport: connects raw materials, plant and market.
- Ports, rivers and dense rail–road networks cut costs. Break-of-bulk points (Rotterdam, Singapore, Mumbai) attract processing industries.
- Coastal industrial belts in Japan and the Netherlands grew on imported raw materials.
- Capital and finance: access to banks, venture capital and stock markets. Liberal credit and investment-friendly regimes attract firms.
- Agglomeration economies: firms gain by clustering.
- The gains come from shared infrastructure, specialised suppliers, a skilled labour pool and knowledge spillovers.
- Examples: Detroit (automobiles), Silicon Valley (IT), Tiruppur (knitwear).
- Technology: turns “neutral stuff” into resources and allows upgrading, for example beneficiation of low-grade ores and electric arc furnaces using scrap.
Political and Institutional Factors
- Government policy shapes location through:
- industrial licensing, tax holidays, subsidies and backward-area incentives;
- public-sector plants;
- Special Economic Zones, industrial corridors and trade agreements.
- Examples: China’s SEZs (Shenzhen, 1980), India’s Special Economic Zones and industrial corridors, and production-linked incentives (PLI). Tariffs and sanctions redraw supply chains.
- Political stability and governance quality matter, as do the stance of unions, environmental lobbies and local communities. Land acquisition protests can stall projects.
Behavioural and Personal Factors
- Entrepreneurs are not perfectly rational optimisers. Personal preference, community networks, the birthplace of a founder and plain chance influence decisions.
- Examples: Henry Ford in his home region around Detroit, and Indian family firms that stay near their home town or community network.
- Allan Pred (1967) captured this with the behavioural matrix: decisions vary with the quality of information a firm holds and its ability to use it.
Theories of Industrial Location in Brief
- Location theory moved from least-cost models to profit-maximisation, behavioural and institutional explanations. The classical models have their own notes, and classical and contemporary location theories compares them with later theories.
| Theory | Proponent (year) | Core idea | Key tools |
|---|---|---|---|
| Least-cost theory | Alfred Weber (1909) | Plant goes to the point of minimum transport cost, adjusted for labour cost and agglomeration | Locational triangle, material index, isotims, isodapanes |
| Transport-cost refinement | Edgar M. Hoover (1937, 1948) | Freight rates have terminal costs and taper with distance, so plants favour transport terminals and break-of-bulk points | Tapering freight curves |
| Profit-maximisation (market area) | August Lösch (1940; English 1954) | Firms seek the location of maximum profit, not minimum cost; demand varies over space | Hexagonal market areas |
| Spatial margins of profitability | E. M. Rawstron (1958), David M. Smith (1966, 1971) | Any site inside the margin where revenue exceeds cost is viable, which explains sub-optimal choices | Space-cost and space-revenue curves |
| Inductive measures | P. Sargant Florence (1940s) | Concentration is measured, not deduced | Location quotient, coefficient of localisation |
| Behavioural matrix | Allan Pred (1967) | Choice depends on information and ability | Behavioural matrix |
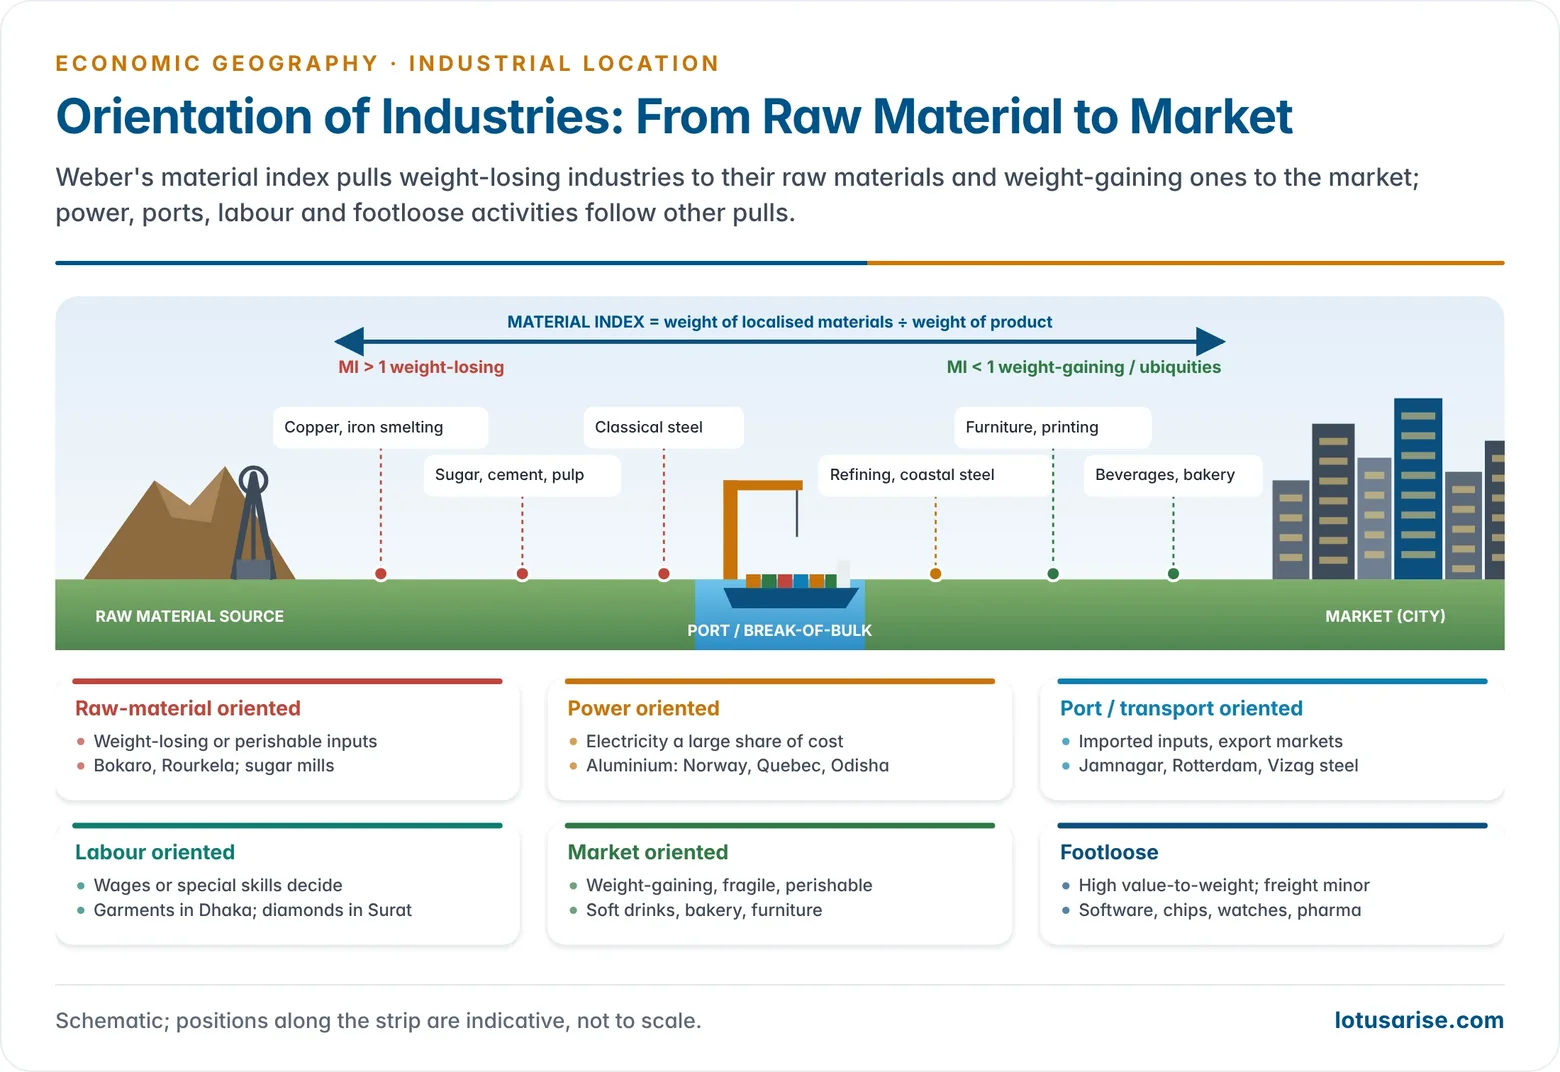
- Weber’s model in one line: the material index (weight of localised materials ÷ weight of product) sets the pull.
- MI > 1 (weight-losing) pulls the plant to the raw material.
- MI < 1 pulls it to the market.
- Two Weberian tools are often confused:
- Isotims join points of equal transport cost for a single input or for the product.
- Isodapanes join points of equal total transport cost, adding the cost of all inputs and of the product.
- A critical isodapane marks how far a plant can move from the least-transport-cost point to a cheap-labour or agglomeration site before extra freight cancels the saving.
- Sargant Florence’s location quotient (LQ) is the share of a region’s industrial workers in a given industry divided by that industry’s share of the national industrial workforce.
- LQ > 1 shows that the region specialises in the industry.
- His coefficient of localisation runs from 0 (spread like all industry) to 1 (wholly concentrated). Mining scores high; bricks and bakeries score low.
Orientation of Industries
| Orientation | Pull factor | Examples |
|---|---|---|
| Raw-material | Weight-losing or perishable inputs | Iron and steel (classical), copper smelting, sugar, cement, pulp, fish canning |
| Power | Cheap energy forms a large share of cost | Aluminium smelting, ferro-alloys, fertilisers |
| Market | Weight-gaining, fragile, perishable or fashion goods | Beverages, bakery, furniture, printing, fashion garments |
| Labour | Wages form a large share of cost, or special skills are needed | Garments, footwear, toys, diamond cutting (Surat) |
| Port / break-of-bulk | Imported raw materials | Refining (Jamnagar, Rotterdam), coastal steel, shipbuilding |
| Footloose | No single pull; high value-to-weight | Electronics, software, watches, pharmaceuticals |
Footloose Industries
- Footloose industries can locate over a wide range of sites. Transport costs form only a small share of total cost because:
- both inputs and products have a high value-to-weight ratio;
- the inputs are ubiquitous;
- the product travels by air or digitally.
- Examples: electronics and semiconductors, software and IT services, watches, diamond cutting, pharmaceuticals, and research and development.
- For these industries the importance of transport cost declines sharply. What decides location instead:
- Skilled labour, universities and research and development: Bengaluru, Hyderabad, Cambridge (UK), Hsinchu.
- Amenity and quality of life: the “sunbelt” and Silicon Valley.
- Digital and air connectivity, airports and data links.
- Policy: SEZs, software technology parks, PLI.
- Footloose industry is not truly location-free. It is freed from freight costs but tied to talent, networks and institutions. This is why it clusters so strongly.
- For backward regions, footloose units are a dispersal opportunity, since they do not need mineral or port locations. They still need human capital and connectivity.
Agglomeration and Industrial Inertia
- Agglomeration economies come in three kinds:
- internal scale economies of the firm;
- localisation economies among firms of the same industry, for example Sialkot sports goods and Tiruppur knitwear;
- urbanisation economies of a large diversified city.
- Beyond a point, diseconomies set in: congestion, high land prices, pollution and wage inflation.
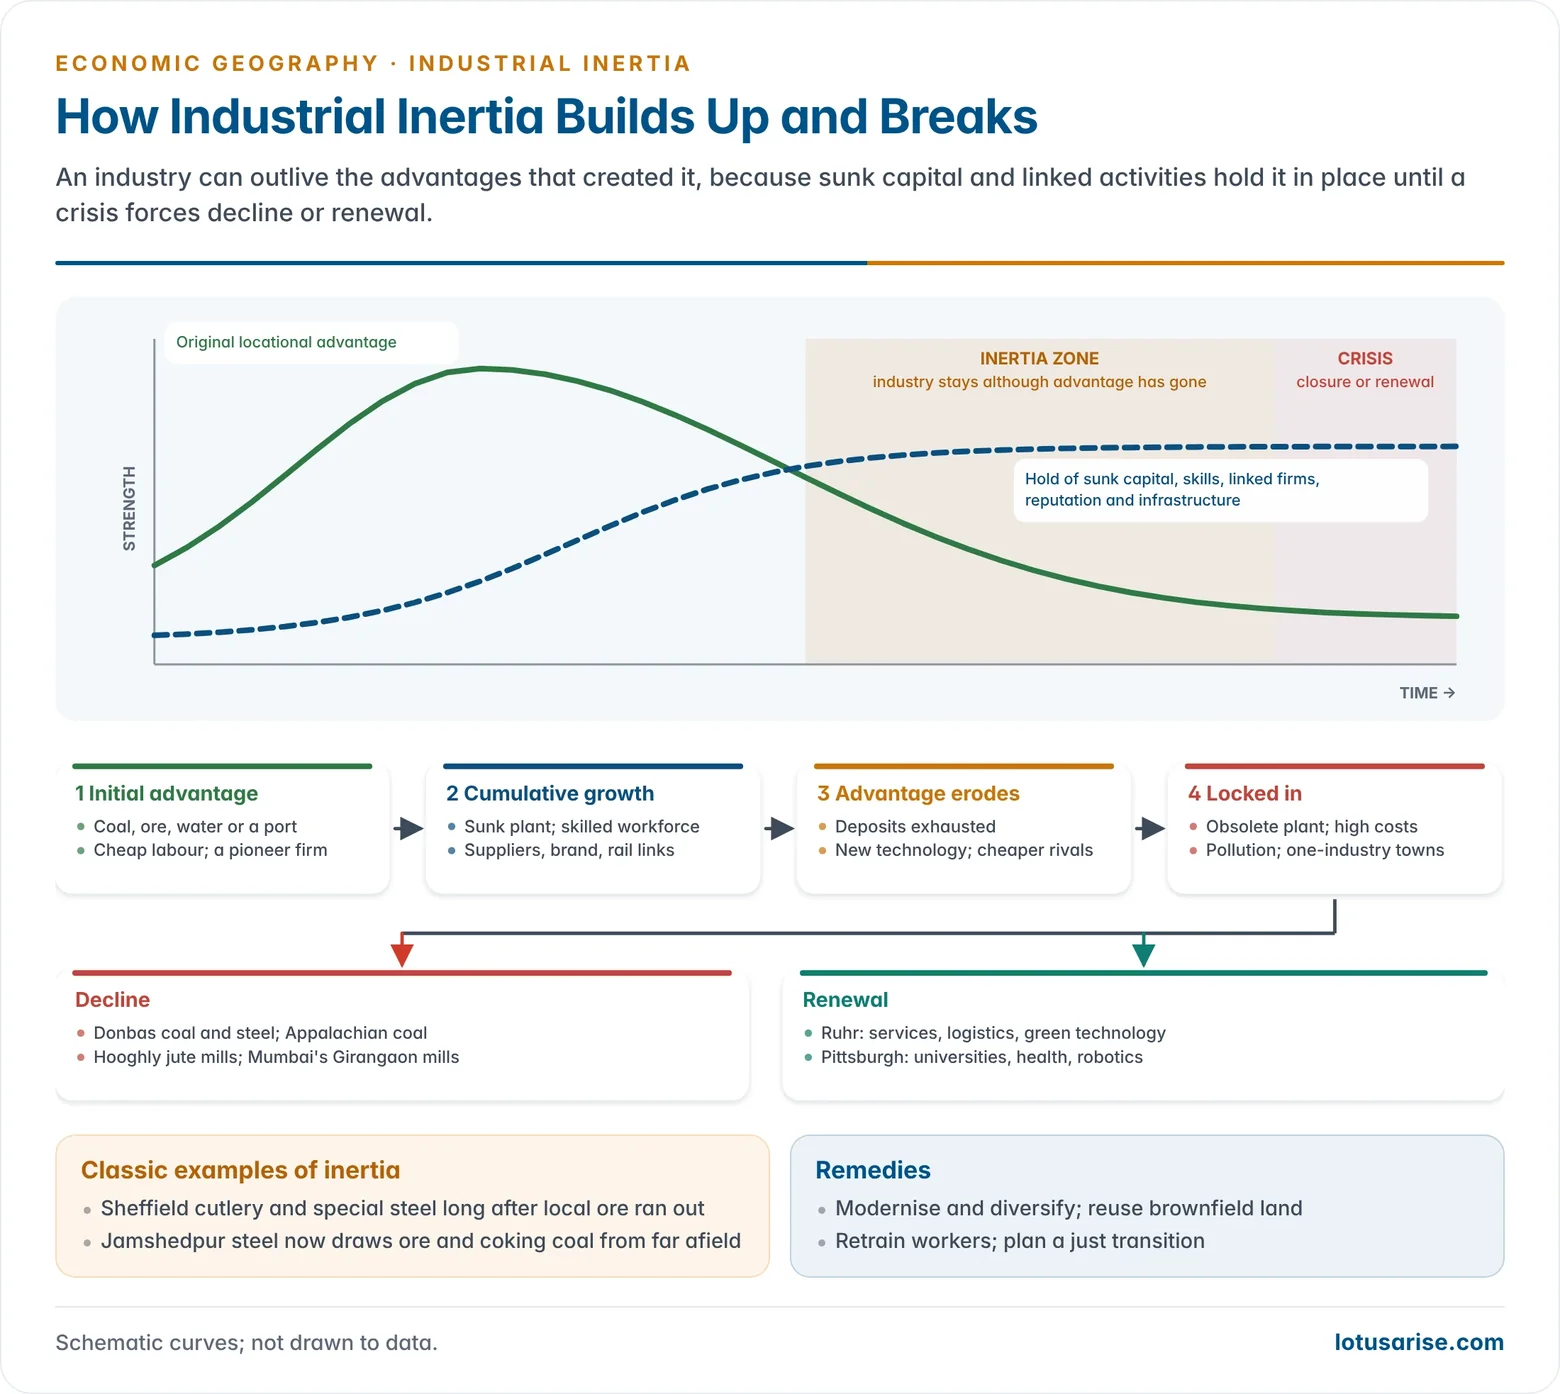
- Industrial (geographical) inertia is the tendency of an industry to stay in its original location after the initial advantages have weakened or vanished.
- The ore or coal may be exhausted, but sunk capital, skilled labour, reputation, linked firms and infrastructure keep it there.
- Examples: Sheffield cutlery and special steels after local ore ran out, Lancashire textiles, Kolkata–Hooghly jute, and Jamshedpur steel, which now draws ore and coking coal from a much wider area.
- Problems of inertia-based industries:
- obsolete plant and old technology, with low productivity;
- higher input costs as raw materials come from farther away;
- congested, ageing infrastructure and cramped sites;
- high wages and strong unions relative to newer regions;
- pollution legacies and derelict land;
- dependence on a single industry, which turns closures into regional unemployment;
- sick units that need repeated bailouts.
- Examples: the jute mills on the Hooghly, the closed textile mills of Mumbai’s Girangaon, the British Midlands and the Ruhr.
- Remedies: modernisation and diversification, reuse of brownfield sites, retraining, and planned relocation. The Ruhr’s shift from coal and steel to services, logistics and green technology is the classic case.
Classification of Industries
- Industries are classified on several bases. The sectoral ladder (primary to quinary) belongs to sectors of the economy.
| Basis | Types | Examples |
|---|---|---|
| Raw material | Agro-based, mineral-based, forest-based, marine-based, animal-based | Sugar, cotton; steel, cement; paper, furniture; fish processing; leather, dairy |
| Product use | Basic (feeding other industries), capital goods, intermediate, consumer goods | Steel; machine tools; chemicals; soap, smartphones |
| Weight and capital | Heavy, light | Steel, shipbuilding, locomotives; garments, toys, electronics assembly |
| Size | Large, medium, small, micro and cottage | Integrated steel plant; MSME clusters; handloom |
| Ownership | Public, private, joint, cooperative | SAIL; Tata Steel; Maruti Suzuki (earlier joint venture); Amul |
| Technology level | Traditional, high-technology | Handicrafts; semiconductors, aerospace, biotechnology |
Locational Patterns of Major World Industries
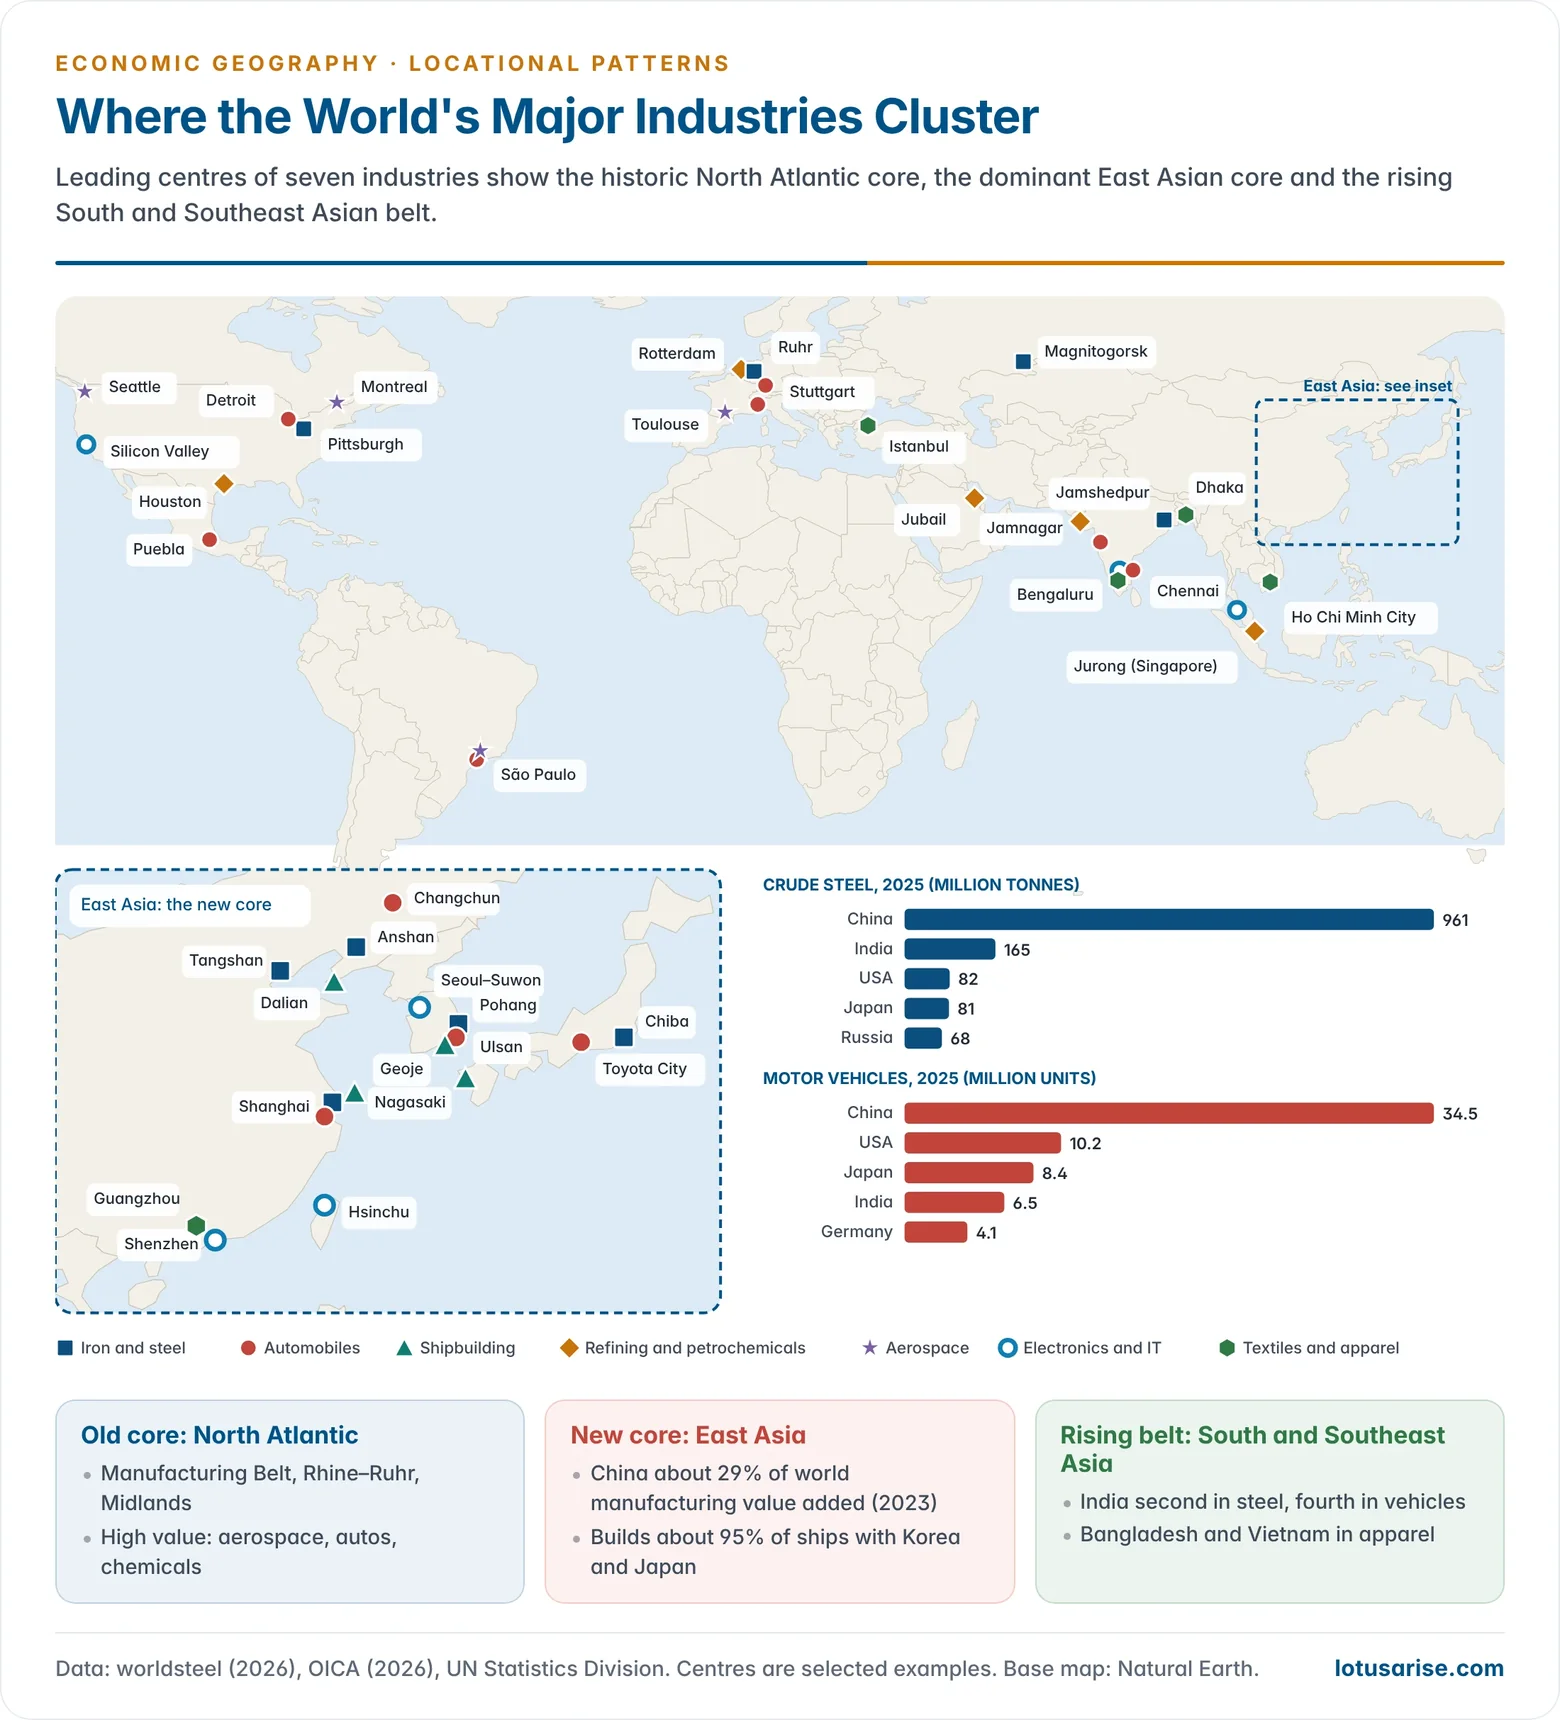
- In 2023, China produced about 29% of world manufacturing value added, roughly 12 percentage points ahead of the United States (UN Statistics Division). Japan, Germany, India and South Korea follow.
- The broad pattern is a historic core in the North Atlantic and a dominant new core in East Asia, with a rising South and Southeast Asian belt.
Iron and Steel
- Steel is the “backbone of modern industry”, used in construction, railways, shipbuilding, automobiles and machinery.
- Locational shifts over time:
- Coalfield phase (19th century): coking coal was the heaviest input. Plants grew on coalfields: Ruhr, Pittsburgh, the Donbas, Kuzbass, the British Midlands, Jharia–Raniganj.
- Ore-field and intermediate phase: better fuel efficiency raised the pull of ore. Examples: Lorraine (minette ore), Magnitogorsk, Bhilai, Rourkela.
- Tidewater phase (after 1950): imported high-grade ore and coal favoured coastal integrated plants such as Japan’s Pacific belt (Chiba, Kimitsu), Pohang and Gwangyang, Dunkirk, Taranto, Visakhapatnam, and JSW Dolvi.
- Scrap and market phase: electric arc furnace (EAF) mini-mills near cities and scrap sources (the US South, Turkey, India’s induction-furnace units).
- Green steel phase: hydrogen-based direct reduction and renewable power favour sites with cheap clean energy, for example the HYBRIT pilot at Luleå in Sweden and proposed green-hydrogen hubs in Odisha and Gujarat.
- Producers (2025, worldsteel): world output was 1,849 Mt.
- China 961 Mt (about 52%), India 165 Mt (second, and growing over 10% a year).
- United States 82 Mt, Japan 81 Mt, Russia 68 Mt, South Korea 62 Mt.
- Problems: Chinese overcapacity and export dumping, trade defences (US Section 232 tariffs, EU safeguards, India’s safeguard duty, 2025), carbon border taxes (EU CBAM), and the decline of old belts.
Non-Ferrous Metals and Aluminium
- Aluminium is the classic power-oriented industry, because electrolysis consumes huge amounts of electricity.
- World primary output was about 73 Mt in 2024, and China produced close to 60%.
- India (Hirakud, Angul, Jharsuguda, Renukoot, Korba) is the second-largest producer.
- Iceland, Norway and Canada run on hydropower; Bahrain and the UAE on gas.
- Copper smelting follows the ore belts of Chile, Peru and the Zambia–Congo Copperbelt. China dominates refining.
- New metals such as lithium, rare earths and cobalt feed batteries and electronics. Their processing is concentrated in China, which has become a strategic concern.
Textiles and Apparel
- Textiles are among the oldest and most footloose of the labour-intensive industries. The industry has repeatedly moved to cheaper labour:
- Lancashire (18th–19th century) → New England, then the US South → Osaka and Japan (1950s) → Hong Kong, Taiwan and South Korea (1960s–70s) → coastal China (1990s) → Bangladesh, Vietnam, Cambodia and India (2010s).
- Raw-material types: cotton (India, China, the USA, Egypt, Pakistan), wool (the UK, Australia, New Zealand), silk (China, India), synthetics (China, South Korea, Taiwan, India).
- Historic and present centres: Manchester, Lowell, Osaka, Shanghai, Milan, Mumbai–Ahmedabad–Surat, Tiruppur, Dhaka–Gazipur, Ho Chi Minh City.
- Apparel exports, 2024 (WTO): China 29.6% of the world total, Bangladesh 6.9%, Vietnam 6.1%, Türkiye 3.2%, India 2.9%.
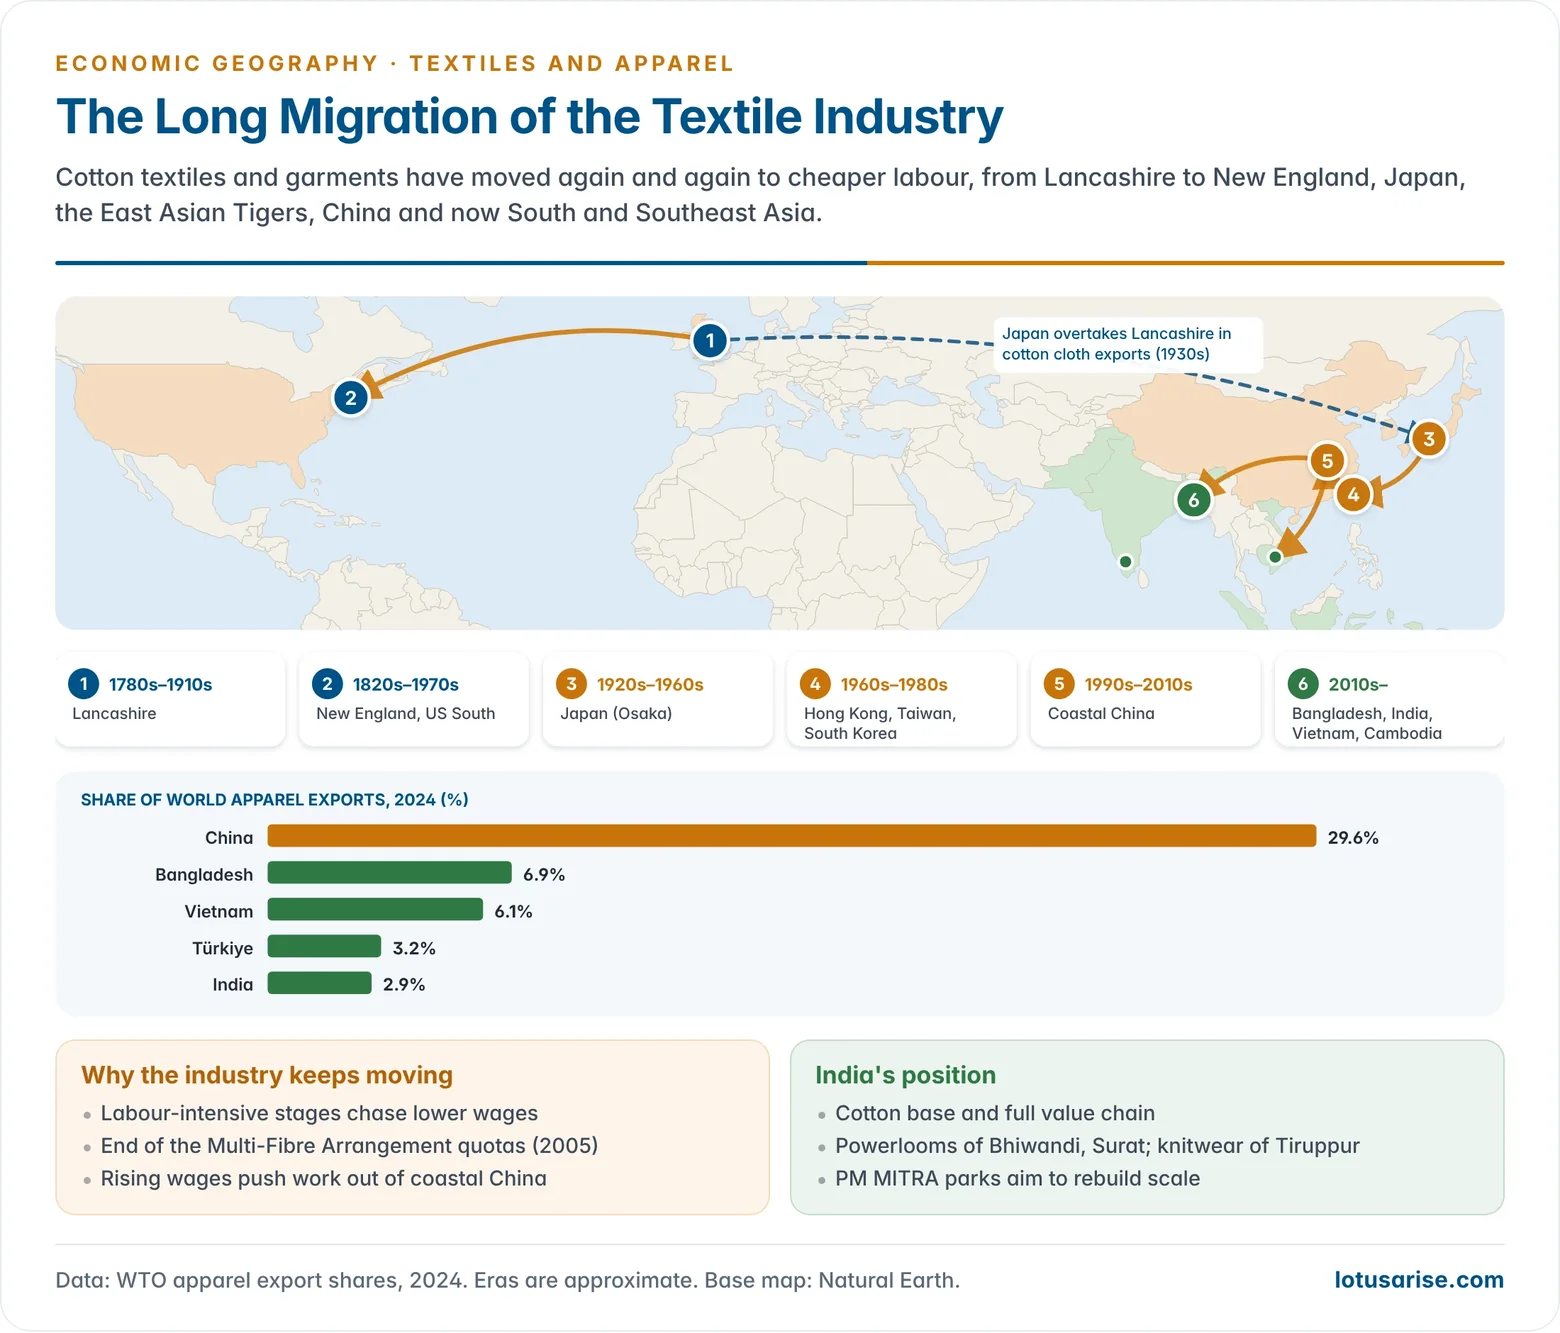
- India: the cotton textile industry shifted from Mumbai mills to the decentralised powerloom centres of Bhiwandi, Surat and Tiruppur. The PM MITRA mega textile parks aim to rebuild scale.
Chemicals and Petrochemicals
- These industries supply fertilisers, plastics, synthetic fibres, dyes, detergents and pharmaceuticals.
- They are capital-intensive and port- or feedstock-oriented. Clusters grow around refineries and gas fields:
- the US Gulf Coast (Houston–Baton Rouge);
- Rotterdam–Antwerp and the Rhine (Ludwigshafen);
- Jubail and Yanbu in Saudi Arabia and Ras Laffan in Qatar;
- Jurong Island in Singapore and Ulsan in South Korea;
- the coastal zones of eastern China;
- Jamnagar, where Reliance runs the world’s largest single-site refining complex (about 1.4 million barrels a day), along with Hazira and Dahej.
- Trend: a shift to cheap-feedstock sites (US shale gas, Gulf ethane), to China for self-sufficiency, and towards green chemistry and bio-based inputs.
Automobiles
- This assembly industry has thousands of component suppliers. It is market- and agglomeration-oriented, and governments court it heavily.
- Classic clusters:
- Detroit (Michigan): Ford, General Motors, Chrysler;
- Stuttgart, Wolfsburg and Munich;
- Toyota City–Nagoya;
- Ulsan;
- Turin;
- São Paulo (ABC region);
- Chennai, Pune–Chakan and Gurugram–Manesar in India.
- Production, 2025 (OICA): world output was 96.4 million vehicles.
- China 34.5 million (over a third), United States 10.2 million, Japan 8.4 million, India 6.5 million (fourth), Germany 4.1 million, South Korea 4.1 million, Mexico 4.1 million.
- Trends:
- The shift to electric vehicles is led by China, which accounted for nearly two-thirds of the more than 17 million electric cars sold in 2024 (IEA).
- Near-shoring to Mexico, Morocco and Eastern Europe.
- Battery gigafactories are becoming the new anchor plants.
Shipbuilding
- The industry needs deep, sheltered waterfronts, steel supply, skilled labour and state support.
- East Asia builds about 95% of world tonnage. In 2024 China delivered about 55% of gross tonnage, South Korea 28% and Japan 13%. China also won about 70% of new orders.
- Major yards: Shanghai and Dalian; Ulsan, Geoje and Okpo; Nagasaki; formerly Glasgow (Clydeside), Belfast and Hamburg.
- India’s yards are at Cochin, Visakhapatnam, Mumbai (Mazagon) and Goa. The 2025 maritime package targets a top-10 global rank by 2030.
Aircraft, Electronics and Other High-Technology Industries
- Aerospace is capital-, skill- and defence-linked:
- Seattle–Everett (Boeing), Toulouse and Hamburg (Airbus), Montreal (Bombardier), São José dos Campos (Embraer), Shanghai (COMAC);
- in India, Bengaluru (HAL) and the Tata–Airbus C-295 line at Vadodara.
- Electronics and information technology:
- Silicon Valley, Shenzhen–Pearl River Delta, Hsinchu (semiconductors), Seoul–Suwon, Penang;
- in India, Bengaluru, Hyderabad, Noida and Sriperumbudur (mobile phones).
- Biotechnology and pharmaceuticals: Boston–Cambridge, Basel, the San Diego region, and India’s Hyderabad and Ahmedabad–Vadodara belt.
- Renewable-energy manufacturing (solar modules, wind turbines, batteries) is dominated by China, with Denmark and Germany in wind and India rapidly building module and cell capacity under PLI.
Agro-Based and Forest-Based Industries
- Agro-based:
- sugar (Brazil, India, Thailand);
- jute (West Bengal, Bangladesh);
- tea processing (Assam, Darjeeling, Sri Lanka, Kenya);
- vegetable oils (palm oil in Malaysia and Indonesia);
- food processing (the USA, France, China, India).
- These industries are raw-material oriented because the inputs are perishable or weight-losing.
- Forest-based:
- paper and pulp (Canada, Finland, Sweden, the USA, Brazil’s eucalyptus belt);
- furniture (Italy, China, Vietnam).
- They are moving towards certified sustainable forestry and recycled fibre.
Famous Industrial Centres of the World
| Centre | Industry | Centre | Industry |
|---|---|---|---|
| Pittsburgh (USA) | Iron and steel | Detroit (USA) | Automobiles |
| Seattle (USA) | Aircraft | Houston (USA) | Petroleum refining, petrochemicals |
| Akron (USA) | Rubber tyres | Chicago (USA) | Meat packing (historic), agro-processing |
| Sheffield (UK) | Cutlery, special steel | Manchester (UK) | Cotton textiles (historic) |
| Dundee (UK) | Jute (historic) | Glasgow (UK) | Shipbuilding (historic) |
| Halifax (UK) | Worsted woollens | Toulouse (France) | Aircraft |
| Lyon (France) | Silk | Wolfsburg (Germany) | Automobiles |
| Jena (Germany) | Optical instruments | Basel (Switzerland) | Pharmaceuticals |
| Turin (Italy) | Automobiles | Milan (Italy) | Fashion, silk |
| Magnitogorsk (Russia) | Iron and steel | Ivanovo (Russia) | Cotton textiles |
| Baku (Azerbaijan) | Oil refining | Anshan (China) | Iron and steel |
| Shenzhen (China) | Electronics | Hsinchu (Taiwan) | Semiconductors |
| Ulsan (South Korea) | Shipbuilding, automobiles | Toyota City (Japan) | Automobiles |
| Hamamatsu (Japan) | Musical instruments, motorcycles | Johannesburg (South Africa) | Gold mining |
| Havana (Cuba) | Cigars | Sialkot (Pakistan) | Sports goods |
| Jamshedpur (India) | Iron and steel | Surat (India) | Diamond cutting, synthetic textiles |
| Tiruppur (India) | Knitwear | Jamnagar (India) | Oil refining |
Major Industrial Regions in Outline
- The great world industrial regions grew where these location factors combined most strongly:
- North America: the Manufacturing Belt (New England, Mid-Atlantic, Pittsburgh–Lake Erie, the Great Lakes), the Southern and Pacific regions, and Ontario–St Lawrence.
- Europe: the Midlands, Lancashire, Yorkshire, Scotland, South Wales and London (UK); Rhine–Ruhr, Saxony and Bavaria (Germany); Nord, Lorraine and Paris (France); the Po valley (Italy); Silesia (Poland–Czechia); and Rotterdam–Antwerp.
- Russia and the CIS: Moscow–Tula, the Urals, the Volga, Kuzbass and the Donbas (Ukraine).
- East Asia: Japan’s Pacific belt (Keihin, Chukyo, Hanshin, North Kyushu); China’s Northeast (Liaoning), the Yangtze delta, the Pearl River delta and Bohai; Seoul–Incheon; Ulsan–Busan; Taiwan’s west coast.
- South Asia: the industrial regions of India such as Hooghly, Mumbai–Pune, Ahmedabad–Vadodara, Chota Nagpur, Bengaluru–Chennai and the National Capital Region.
- Latin America: São Paulo, which produces close to a third of Brazil’s GDP.
Locational Problems of World Industries
- Locational advantage is never permanent. Resources run out, technology changes, markets move and policy shifts. What made a region rich can later trap it.
Resource and Energy Problems
- Exhaustion of raw materials brings decline to industrial regions built on finite deposits.
- Examples: the closure of British coal mines from the 1980s, and the decline of Appalachian coal, the Ruhr and the Donbas.
- Dependence on imported raw materials exposes Japan, South Korea, Singapore and Taiwan to price shocks and supply disruptions.
- Energy insecurity: Europe’s gas shock after the Russia–Ukraine war (2022) made fertiliser, chemical, aluminium and glass plants uncompetitive. Several shut, especially in Germany.
Market and Competitive Problems
- Changing demand and cheaper competitors hollowed out Manchester and Lowell textiles and British shipbuilding.
- Overcapacity in steel, solar modules, aluminium and electric vehicles, led by China, depresses prices worldwide and triggers anti-dumping action.
Labour Problems
- High wages in old cores push labour-intensive work to Bangladesh, Vietnam and India.
- Labour unrest raises costs. Examples are the US auto workers’ (UAW) strike of 2023 and wage disputes in the Indian auto belts.
- Skill gaps and spatial mismatch: high-tech and AI-related industries cannot find workers where plants are wanted, while redundant workers remain in old regions.
Transport and Infrastructure Problems
- High freight costs handicap landlocked regions (Central Asia, much of Africa) for bulky industries.
- Ageing infrastructure, congested ports and obsolete rail lines hurt old belts in Europe and North America.
Agglomeration, Congestion and Regional Imbalance
- Inertia keeps outdated industries in place.
- Over-concentration in Mumbai, Shanghai and São Paulo raises land prices, congestion and pollution. Rising costs are pushing Chinese factories inland to Chongqing, Chengdu and Zhengzhou, and offshore.
- Core–periphery imbalance: industrial cores prosper while peripheries stagnate. Gunnar Myrdal‘s backwash effects describe this.
- Industrial dispersal policies (growth centres, backward-area incentives) try to correct it, with mixed results.
Political, Trade and Regulatory Problems
- Protectionism and trade wars:
- the US–China trade war (from 2018) and the sweeping US tariffs of 2025;
- export controls on chips and critical minerals;
- all of these force costly supply-chain reconfiguration.
- Environmental regulation in the EU and USA pushes polluting stages abroad. This is the pollution-haven hypothesis, now countered by carbon border taxes.
- Geopolitical instability: war in the Donbas, Red Sea shipping attacks (2024) and Middle East conflict disrupt supply chains.
Environmental and Technological Problems
- Pollution legacies (air, water and soil contamination) in the Donbas, Ruhr, Appalachia, Singrauli and the Vapi–Ankleshwar chemical belt.
- Decarbonisation pressure threatens coal-dependent belts such as Silesia, Jharkhand and Shanxi. A just transition for their workers is now a policy issue.
- Technological obsolescence: old coal-based steel and European shipbuilding became uncompetitive.
- Automation and the digital divide reshape where work is done, and with it the global shift in manufacturing towards Asia.
Case Examples
| Region | Problem | Response |
|---|---|---|
| Ruhr (Germany) | Coal and steel decline | Restructuring into services, logistics, universities, green technology (IBA Emscher Park) |
| Donbas (Ukraine) | Resource depletion, unsafe mines, war since 2014 | Production collapsed |
| Appalachia (USA) | Coal decline, unemployment, social distress | Federal regional programmes, energy transition funds |
| Manchester (UK) | Loss of textiles | Service, media and knowledge economy |
| Coastal China | Rising wages, pollution, congestion | Relocation inland and to Southeast Asia; upgrading |
| Hooghly belt (India) | Jute decline, inertia, labour issues | Diversification, mandatory jute packaging, modernisation |
| Mumbai (India) | Textile mill closures (after 1982) | Mill lands redeveloped for offices and housing |
- Outlook: future industrial geography will turn on green industry, digital manufacturing, resilient supply chains and spatially balanced development.
Previous Year Questions
2020Analyse the dynamics of industrial location in the metropolitan cities of India.2019Distinguish between ‘isodapanes’ and ‘isotims’. Critically examine the least cost theory of industrial location given by Alfred Weber.2018Discuss the degree of importance of transportation costs as a factor of industrial location with respect to “footloose industries”.2012Write short note on Problems faced by industries which developed due to inertia.1991Examine the world patterns of industrial development and explain the problems of industrial development at national levels.





thanku so much sir
thank you o much for providing such quality content. your content is detailed and in-depth for mains.
Thank you sir
You haven’t discussed the problems.
The description of this article is very good and I am sure that there will be no mistakes in it.