

- Balance of Trade (BOT), also called the trade balance or international trade balance, is the gap between the value of a country’s exports and imports over a given period.
- It is the largest component of the balance of payments (BOP) and a quick reading of how a country fits into world trade. Foreign trade is often called the economic barometer of a nation.
- India’s position in 2025-26: goods exports of US$ 441.78 billion, goods imports of US$ 774.98 billion, and a merchandise deficit of about US$ 333.2 billion. A services surplus of about US$ 213.9 billion cut the overall deficit to about US$ 119.3 billion (Department of Commerce, April 2026).
Trade and the Balance of Trade
Trade and Its Scales
- Trade is the buying and selling of goods. It works at three scales:
- Local trade, within a settlement and its surroundings.
- Regional trade, between parts of one country.
- Foreign, international or overseas trade, across national borders, where the flows are called imports and exports.
- Foreign trade matters because it gives a country a source of what it lacks and an outlet for what it has in surplus.
Meaning of Balance of Trade
- BOT records a nation’s imports and exports within a specific period, usually a year.
- In its strict sense, it records only tangible goods, also called visible trade.
- Some accounts, and the headline trade release in India, also add services and quote a combined figure. The two must be kept apart.
- Three outcomes are possible:
| Outcome | Condition | Older label | Country type in older accounts |
|---|---|---|---|
| Trade equilibrium | Exports equal imports | Balanced | Rare in practice |
| Trade surplus | Exports exceed imports | Favourable or positive | Trade creditor nation |
| Trade deficit | Imports exceed exports | Unfavourable or negative | Trade debtor nation |
- A surplus puts an economy in a favourable position on paper, and a deficit in an unfavourable one.
- The labels date from a time when an excess of exports brought in gold, so they should not be read as verdicts.
- A country can carry a long-run deficit and still prosper, as Britain did for well over a century.
- Many poor countries run surpluses and still have financial difficulties.
- An exact balance is rarely reached, because trade passes through many independent firms and market values shift from year to year.
Balance of Trade within the Balance of Payments
- The Balance of Payments is the set of accounts recording a country’s economic transactions with the rest of the world over a period: commodities, services, incomes, and private and public investment.
- It shows the money flowing in and out of an economy.
- The overall balance is what the ideal of zero refers to, with money coming in equal to money going out. This is highly unlikely in practice.
- A negative overall balance indicates a deficit and a positive one a surplus. As the accounts must finally balance, the gap is met through a change in foreign exchange reserves.
- BOT is a part of the current account.
- The current account also takes in services, income from the net international investment position (NIIP), and transfers such as remittances and international aid.
- When a country’s current account is in surplus, its net international asset position rises accordingly.
- Invisible trade explains why a large trade deficit need not mean a large current account deficit. Its receipts include:
- Financial services such as insurance and banking.
- Transport services such as shipping and air freight.
- Spending by foreign tourists, and earnings on overseas investment.
- Remittances from emigrants, which are especially large for India.
| Account | Covers | India 2025-26 (RBI, US$ billion) |
|---|---|---|
| Merchandise balance | Goods only | −337.3 (2024-25: −286.9) |
| Net services | Software, business services, transport, travel | +216.6 (2024-25: +188.8) |
| Net secondary income | Mainly remittances | +143.6 (2024-25: +123.5) |
| Current account | All the above, with primary income | −25.2, or 0.6% of GDP (2024-25: −22.9, 0.6%) |
- The merchandise figure here is on the BOP basis, so it differs a little from the customs-based US$ 333.2 billion.
- Reserves fell by US$ 23.6 billion on the BOP basis in 2025-26.
Why a Trade Deficit Arises
- Domestic production falls short of consumption.
- Crude oil, pulses and edible oils are the standing cases, as output does not meet demand.
- Crude import dependence stood at 88.7% in 2025-26, the root of the petroleum bill.
- The logic holds even for large producers. A country producing a lot of milk may still import some if output falls short of total demand, though India, the largest producer, imports very little dairy.
- Crude oil, pulses and edible oils are the standing cases, as output does not meet demand.
- Domestic production costs more, and consumers choose foreign goods.
- In steel, India has enough capacity, but its cost of production is higher than China’s. Users such as automobile companies then buy cheaper Chinese steel of the same quality.
- Growth itself raises the bill. Investment needs machinery, and rising incomes raise demand for fuel, electronics and gold.
India’s Trade Balance
The Long Trend
- Trade was close to balance in 1950-51, when the deficit was only ₹2 crore.
- Imports rose fast through the 1950s, as machinery came in for planned industrial growth.
- Exports picked up in the 1960s, and the deficit shrank from ₹480 crore in 1960-61 to ₹99 crore in 1970-71.
- There were two rare surpluses, of about ₹104 crore in 1972-73 and ₹69 crore in 1976-77 (RBI).
- Since then, imports have consistently outpaced exports.
- Growth in value reflects a larger and more diverse economy, but also inflation and devaluation of the rupee.
| Year | Imports (₹ crore) | Exports (₹ crore) | Total trade (₹ crore) | Balance (₹ crore) |
|---|---|---|---|---|
| 1950-51 | 608 | 606 | 1,214 | −2 |
| 1960-61 | 1,122 | 642 | 1,764 | −480 |
| 1970-71 | 1,634 | 1,535 | 3,169 | −99 |
| 1980-81 | 12,549 | 6,710 | 19,259 | −5,839 |
| 1990-91 | 43,193 | 32,558 | 75,751 | −10,635 |
| 2000-01 | 2,30,873 | 2,03,571 | 4,34,444 | −27,302 |
| 2005-06 | 6,60,409 | 4,56,418 | 11,16,827 | −2,03,991 |
| 2010-11 | 16,83,467 | 11,42,922 | 28,26,389 | −5,40,545 |
| 2013-14 | 27,14,182 | 18,94,182 | 46,08,364 | −8,20,000 |
Recent Figures
| Year | Goods exports | Goods imports | Goods balance | Services balance | Overall balance |
|---|---|---|---|---|---|
| 2012-13 | 300.40 | 490.74 | −190.34 | +62.94 | −127.40 |
| 2015-16 | 262.29 | 381.01 | −118.72 | +69.42 | −49.30 |
| 2019-20 | 313.36 | 474.71 | −161.35 | +80.08 | −81.27 |
| 2020-21 | 291.81 | 394.44 | −102.63 | +85.05 | −17.57 |
| 2022-23 | 451.07 | 715.97 | −264.90 | +138.17 | −126.73 |
| 2024-25 | 437.51 | 721.32 | −283.81 | +189.40 | −94.41 |
| 2025-26 | 441.78 | 774.98 | −333.20 | +213.89 | −119.30 |
- Values are in US$ billion (DGCI&S to 2024-25; Department of Commerce estimate of April 2026 for 2025-26).
- 2012-13 stands out: the balance-of-payments basis gave a deficit of about US$ 195.6 billion, and the current account deficit hit a record 4.8% of GDP. Oil and gold together made up most of the gap.
- 2020-21 was the low point of the pandemic, when imports collapsed.
- April–September 2026: goods exports of US$ 259.89 billion against imports of US$ 437.53 billion, a goods deficit of US$ 177.64 billion. The overall deficit was US$ 74.93 billion.
- A later revision (July 2026) put total exports of goods and services in 2025-26 at about US$ 863.1 billion, against the first estimate of US$ 860.09 billion.
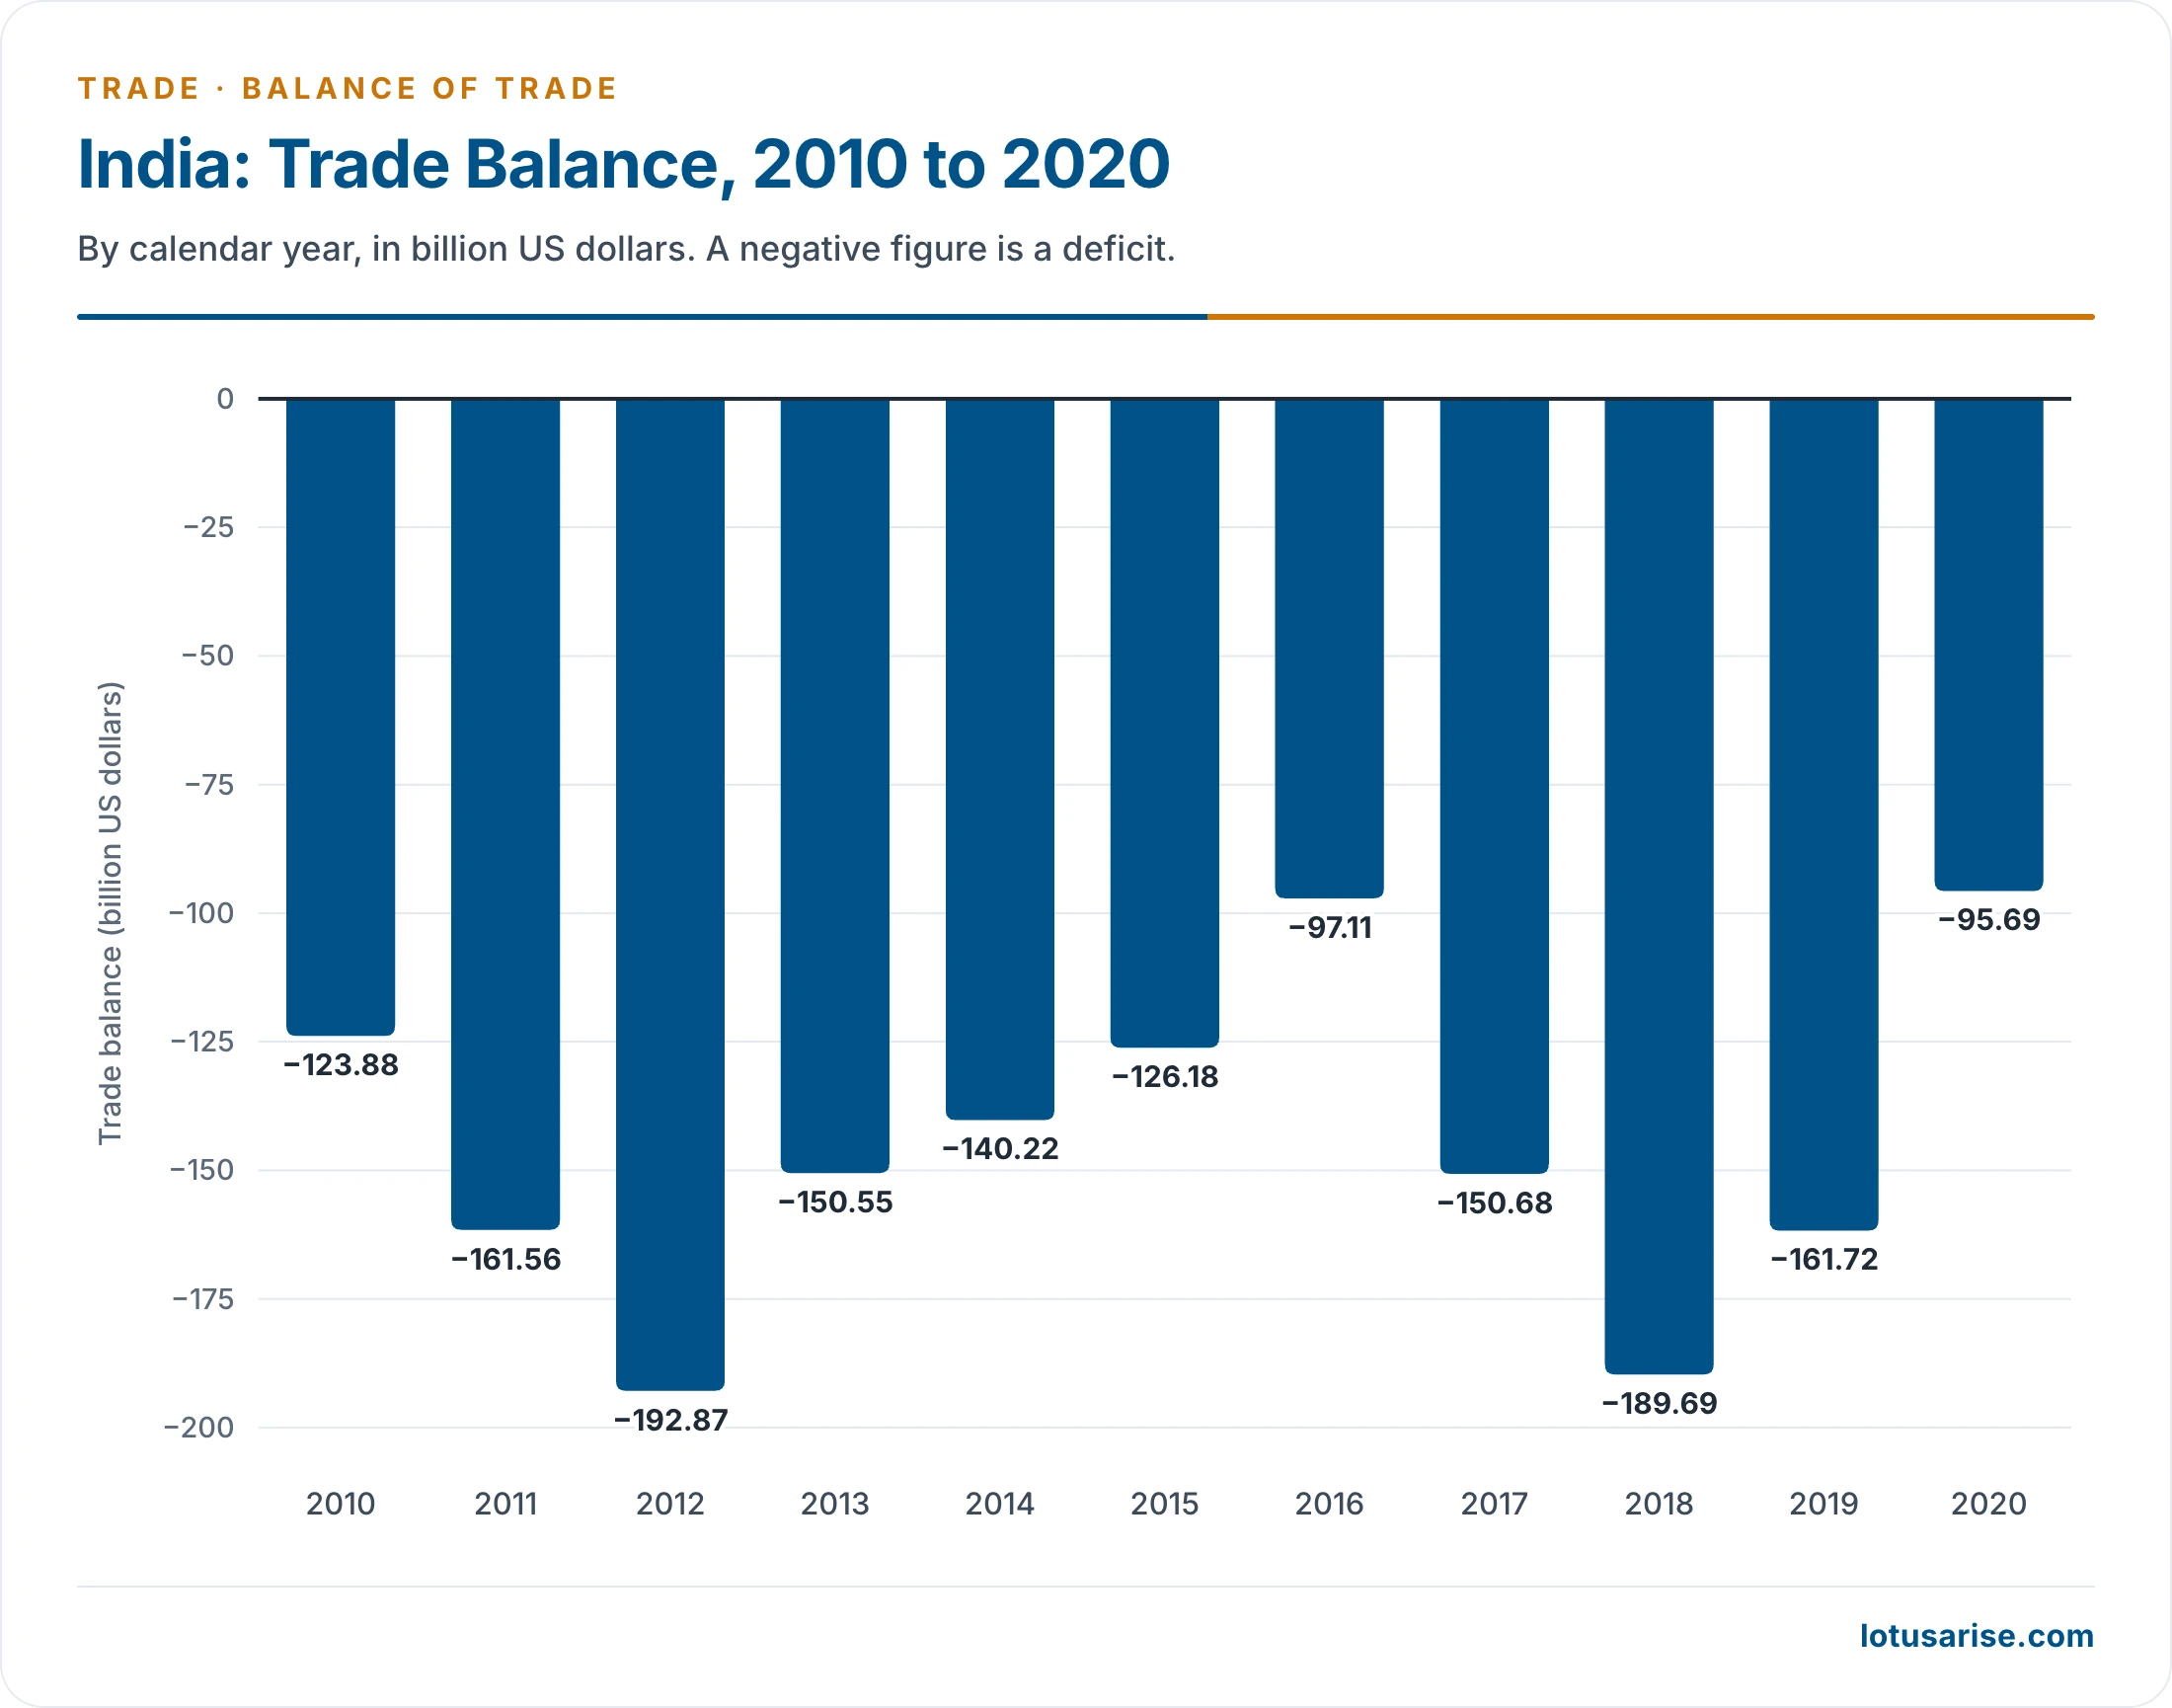
- This chart runs by calendar year, so its bars differ a little from the fiscal-year table.
Why the Deficit Persists
- Energy: petroleum products, crude and related imports cost about US$ 173.6 billion in 2025-26, the largest single item.
- Electronics: imports crossed US$ 100 billion, reaching about US$ 116.4 billion in 2025-26, because assembly has grown faster than component making.
- Gold: about US$ 72.4 billion in 2025-26, up 25%. Demand is cultural as well as financial, and prices were high.
- Machinery and intermediates: machinery alone cost about US$ 61.8 billion. Fast growth pulls in capital goods.
- Weak goods exports: they have stayed near US$ 440–450 billion since 2022-23. Oil exports fell with prices, and US tariffs of up to 50% from August 2025 hit labour-intensive goods before a February 2026 framework cut the rate to 18%.
- China: the single largest bilateral gap, at US$ 112.16 billion in 2025-26.
- Trade agreements: some have raised imports faster than exports, with studies pointing to ASEAN, Japan and Korea.
What Eases the Deficit
- Services and remittances carry the external account. This is why a goods deficit above US$ 330 billion came with a current account deficit of only 0.6% of GDP in 2025-26.
- Reducing import dependence: domestic oil and gas, ethanol blending, renewables and strategic reserves on the energy side, and oilseed and pulse missions on the farm side.
- Manufacturing: production-linked incentives, which helped electronics exports grow from US$ 38.7 billion to about US$ 48 billion between 2024-25 and 2025-26.
- Market diversification through new trade agreements and the measures of the Foreign Trade Policy.
- Lower logistics cost through better ports, corridors and customs procedures.
India in World Trade
- Older shares: 2.2% of world trade in 1948-49, falling to 1% in 1963-64 and 0.4% in 1995-96.
- Older ranks: 16th in 1953, 20th in 1963, 41st in 1983 and 50th in 1996.
- Other developing countries overtook India in this period, and the large home market kept trade small relative to size.
- Recovery since 2000-01: a share of 1.6% and 19th place among exporters by about 2013.
- Now (2024): India holds 1.8% of world goods exports (18th) and 2.8% of goods imports (9th).
- It stands far higher in services, with 4.3% of world commercial services exports (8th).
- Trade openness, or trade as a share of GDP, was about 44.6 in 2024-25, against 55.8 in 2011-12.
Basis, Composition and Direction
What Drives Overseas Trade
| Factor | How it works | Examples |
|---|---|---|
| Natural resources | Relief, geology, climate and soil differ, so endowments differ | Base of all exchange |
| Marketable surplus | Output above home need goes abroad | Tea from India, coffee from Brazil, jute from Bangladesh, pulp and paper from Norway and Sweden, wood from Australia, oil from West Asia |
| Scarcity | No country has everything | Japan and Britain import raw materials |
| Transport and communication | Cheap bulk carriage and cold chains open markets | Coal and ore by sea, milk, meat and fruit under refrigeration |
| Economic disparity | Early-stage economies sell primary goods and buy finished ones | India’s long reliance on raw materials |
| Trade policy | Openness encourages trade, and restrictions discourage it | Curbs on oilseed exports, duties to protect home industry |
| War and peace | Conflict disrupts routes | The 2026 Strait of Hormuz disruption |
| Political relations | Cordial ties raise trade | India–Russia trade high, India–Pakistan trade low |
Composition of Exports
- India’s export basket has moved from raw materials to manufactures and services.
- Before Independence, it sold raw cotton, tea and iron ore to Britain and bought finished goods.
- Today it sells items from agriculture, industry, handicrafts, handloom and cottage sectors.
- Software and electronics have grown since the 1990s, and they go mainly to advanced economies.
| Group | 2025-26 (US$ billion) | Share of goods exports |
|---|---|---|
| Engineering goods | 122.6 | 28.0% |
| Petroleum products | 53.8 | 12.3% |
| Electronic goods | 48.0 | 11.0% |
| Drugs and pharmaceuticals | 31.1 | 7.1% |
| Chemicals | 28.7 | 6.6% |
| Gems and jewellery | 28.2 | 6.4% |
- The classical items of 2013-14 show how the basket looked a little over a decade ago:
| Item | Value 2013-14 (₹ crore) | Features and buyers in that account |
|---|---|---|
| Gems and jewellery | 2,48,465 | 13.1% of exports, up from ₹7 crore in 1960-61. Rough stones imported, cut and polished, then sold to the USA, Switzerland, Japan, Belgium, Hong Kong and West Asia |
| Chemicals and allied products | 2,50,325 | About 13.2% of exports. Russia, the USA, Britain, Netherlands, Bangladesh, UAE |
| Engineering goods (2012-13) | 3,08,682 | Just ₹3 crore in 1950-51. Saudi Arabia, Japan, Iran, Sri Lanka, Uganda |
| Readymade garments | 90,402 | 4.8% of exports, ₹1,067 crore in 1985-86. Design and low labour cost |
| Cotton yarn, fabrics, made-ups | 53,914 | USA, Russia, Australia, Britain, Germany |
| Leather and manufactures | 34,517 | Footwear leads; large livestock base. China a rising rival |
| Marine products (2012-13) | 18,833 | Growth after 1975. Over 80 countries, with Japan and the USA dominant |
| Spices | 15,981 | 1,029.3 thousand tonnes |
| Coffee | 4,797 | 278.9 thousand tonnes. USA, Russia, Europe |
| Tea | 4,832 | 247.6 thousand tonnes. Share falling before Sri Lanka and China. Britain the old buyer |
| Jute manufactures | 2,296 | Hit by Partition, substitutes and rivals. USA, Australia, Canada, Europe |
| Iron ore | 956 | Falling by policy, to feed home steel. Japan the main buyer then, and China later |
| Mica | 304 | India long the leading producer and exporter |
- Apparel and textiles, among India’s major industries, earned about US$ 36.6 billion in 2024-25, or 8.37% of goods exports.
- Calendar 2024 by customs heading (DGCI&S): mineral fuels US$ 75.85 billion, electrical and electronic equipment 40.17, machinery 32.52, pearls and precious stones 29.93, pharmaceuticals 23.37, vehicles 22.11, organic chemicals 21.02 and cereals 12.11.
- Services have become the second leg of exports, at about US$ 418 billion in 2025-26, nearly as large as goods.
Composition of Imports
- At Independence, about 70% of imports were finished consumer goods or inputs for factories.
- Machinery followed during early industrial planning, and foodgrains were large until the Green Revolution.
- Oil then became the largest item. Its share of the import bill jumped after the oil crises of the 1970s, and stood at 36.8% in 2013-14. The Gulf War and the break-up of the USSR in the early 1990s also hit supplies.
- Imports are now broad-based, with a growing share of electronics and intermediates.
| Group | 2013-14 (₹ crore) | Notes then | Latest (US$ billion) |
|---|---|---|---|
| Petroleum, oil, lubricants | 10,00,064 | Iran, Saudi Arabia, UAE, Iraq, Kuwait, Venezuela, Indonesia, Malaysia | 173.6 (2025-26). Russia, Iraq and the Gulf now lead |
| Electronic goods | n/a | Small then | 116.4 (2025-26). China leads |
| Gold and silver | 3,02,922 (2012-13) | Curbs in the early 2010s, later eased | Gold 72.4 (2025-26) |
| Pearls, precious stones | 1,44,557 | Rough stones for re-export; ₹1 crore in 1960-61 | HS 71, with gold, 90.50 (calendar 2024) |
| Machinery | n/a | USA, Britain, Germany, Russia, Japan; now only high technology | 61.8 (2025-26) |
| Edible oils | 56,489 | 10,434 thousand tonnes; USA, Brazil, Malaysia | Fats and oils 17.01 (calendar 2024) |
| Iron and steel | 47,912 | 7,406 thousand tonnes; Japan, Germany, Belgium, Britain, Korea | 17.69 (calendar 2024) |
| Fertilizers | 38,231 | 22,154 thousand tonnes; USA, Germany, Japan | 7.80 (calendar 2024) |
| Chemicals | 22,498 | USA, Japan, Germany, Netherlands | Organic 26.11 (calendar 2024) |
| Medicines | 17,944 | Germany, Italy, China, Switzerland | Bulk drugs lean on China |
| Paper, pulp | 15,067 and 8,378 | Russia, Sweden, Germany, China, Korea | n/a |
| Raw cotton, wool, jute, synthetic fibre | 2,371; 1,962; 146; 1,889 | Egypt, Uganda, USA; Australia; Bangladesh | n/a |
- Other metals, such as copper, lead, tin, zinc and aluminium, also figure, with copper at US$ 10.50 billion in calendar 2024.
- The gold and silver trade shows how little of the demand is met at home.
Direction of Trade
- Before Independence, Britain was the leading partner, in a colonial pattern of raw materials out and manufactures in.
- India’s older links reach back to China, Myanmar, Indonesia, Malaysia, Thailand, Iran, Iraq, Afghanistan, Saudi Arabia, Egypt and Greece.
- Since Independence, the pattern has widened to almost every region, with Asia now taking the largest share.
| Region | Share 2012-13 (%) | Within it |
|---|---|---|
| Asia | 50.76 | West Asia 20.76, North-East Asia 13.21, ASEAN 10.96, South Asia 4.91, East Asia (Oceanic) 0.91 |
| Europe | 18.6 | EU 16.75, EFTA 0.46, others 1.4 |
| America | 17.75 | North America 13.24, Latin America 4.51 |
| Africa | 9.7 | |
| CIS and Baltics | 1.24 | |
| Unspecified | 1.95 |
Largest Trading Partners with India
| Partner, 2025-26 | Exports | Imports | Total trade | Balance |
|---|---|---|---|---|
| China | 19.47 | 131.63 | 151.10 | −112.16 |
| United States | 87.32 | 53.49 | 140.80 | +33.83 |
| UAE | 37.36 | 63.89 | 101.25 | −26.54 |
| Russia | 4.49 | 55.37 | 59.86 | −50.88 |
| Saudi Arabia | 10.28 | 30.79 | 41.07 | −20.51 |
| Singapore | 11.86 | 24.24 | 36.10 | −12.38 |
| Hong Kong | 8.08 | 24.33 | 32.41 | −16.25 |
| Germany | 11.53 | 19.51 | 31.03 | −7.98 |
| Iraq | 2.96 | 24.56 | 27.52 | −21.60 |
| Japan | 6.04 | 21.44 | 27.48 | −15.40 |
- Values are in US$ billion, from official trade data for April 2025 to March 2026.
- China overtook the United States as the largest partner in 2025-26, and stayed ahead in April–September 2026 with trade of US$ 91.76 billion against US$ 83.14 billion.
- The United States stays the largest export market, at 19.78% of goods exports, and China the largest source of imports, at 16.97%.
- The rise of Russia reflects discounted crude bought since 2022.
- Surpluses in 2025-26 include the United States, the Netherlands (+11.71), the UK (+1.76), Italy and Belgium.
- Exports also reach the Netherlands (US$ 17.50 billion), the UK (13.44) and Bangladesh (10.59).
- India’s largest trade partners for 2019-20 make a useful comparison, with total trade as the sum of imports and exports, in US$ billion:
| Partner, 2019-20 | Exports | Imports | Total trade | Balance | Basis |
|---|---|---|---|---|---|
| United States | 53.09 | 35.82 | 88.91 | +17.27 | Full year |
| China | 16.61 | 65.26 | 81.87 | −48.65 | Full year |
| UAE | 28.85 | 30.26 | 59.11 | −1.41 | Full year |
| Saudi Arabia | 6.24 | 26.86 | 33.10 | −20.62 | Full year |
| Hong Kong | 10.97 | 16.94 | 27.91 | −5.97 | Full year |
| Iraq | 1.00 | 23.74 | 24.74 | −22.74 | Part-year exports |
| Singapore | 8.92 | 14.75 | 23.67 | −5.83 | Full year |
| Germany | 8.29 | 13.69 | 21.98 | −5.40 | Full year |
| South Korea | 4.85 | 15.66 | 20.51 | −10.81 | Full year |
| Indonesia | 4.13 | 15.06 | 19.19 | −10.93 | Full year |
| Switzerland | 1.21 | 16.90 | 18.11 | −15.69 | Full year |
| Japan | 4.66 | 12.43 | 17.09 | −7.77 | Part-year exports |
| Malaysia | 6.36 | 9.78 | 16.14 | −3.42 | Full year |
| Belgium | 5.81 | 8.26 | 14.07 | −2.45 | Part-year imports |
| United Kingdom | 8.74 | 5.19 | 13.93 | +3.55 | Part-year imports |
| Australia | 3.26 | 9.78 | 13.04 | −6.52 | Part-year exports |
| Nigeria | 2.22 | 9.95 | 12.17 | −7.73 | Part-year |
| Qatar | 0.90 | 9.69 | 10.59 | −8.79 | Part-year exports |
| South Africa | 3.59 | 5.95 | 9.54 | −2.36 | Part-year |
| Iran | 2.78 | 6.28 | 9.06 | −3.50 | Part-year |
| Kuwait | 1.25 | 4.97 | 6.22 | −3.72 | Part-year |
| Venezuela | 0.13 | 5.70 | 5.83 | −5.57 | Part-year |
- Where a row is marked part-year, the figure was taken before the year closed, so the row understates that partner and its rank is only indicative.
| Top export destinations, 2019-20 | US$ billion | Share of exports | Top import sources, 2019-20 | US$ billion | Share of imports |
|---|---|---|---|---|---|
| United States | 53.09 | 16.94% | China | 65.26 | 13.75% |
| UAE | 28.85 | 9.21% | United States | 35.82 | 7.55% |
| China | 16.61 | 5.30% | UAE | 30.26 | 6.37% |
| Hong Kong | 10.97 | 3.50% | Saudi Arabia | 26.86 | 5.66% |
| Singapore | 8.92 | 2.85% | Iraq | 23.74 | 5.00% |
| United Kingdom | 8.74 | 2.79% | Hong Kong | 16.94 | 3.57% |
| Netherlands | 8.37 | 2.67% | Switzerland | 16.90 | 3.56% |
| Germany | 8.29 | 2.65% | South Korea | 15.66 | 3.30% |
| Bangladesh | 8.20 | 2.62% | Indonesia | 15.06 | 3.17% |
| Nepal | 7.16 | 2.28% | Singapore | 14.75 | 3.11% |
India’s Trade Surplus
- India had a surplus with nine of the 20-odd countries in the Indo-Pacific group studied by the Confederation of Indian Industry (CII) in 2020.
- The region runs from the western shores of the American continent to the eastern coast of Africa.
- Trade with these economies rose eight times in 19 years, from US$ 33 billion in 2001 to US$ 262 billion in 2020. The United States was the largest partner, with 29%.
- The group comprised Australia, Bangladesh, Chile, Colombia, France, Fiji, India, Indonesia, Japan, Kenya, South Korea, Maldives, Mauritius, Malaysia, Mexico, Singapore, Sri Lanka, Thailand, Vietnam, the UAE and the US.
- It holds 44% of world surface area and 62% of global GDP, and more than 50% of global trade passes through its waters.
- The surplus held in all of 2016–2020 with eight of them: Kenya, Mauritius, France, Fiji, Bangladesh, Sri Lanka, Maldives and the US.
- These economies supplied 36% of India’s global imports in 2020.
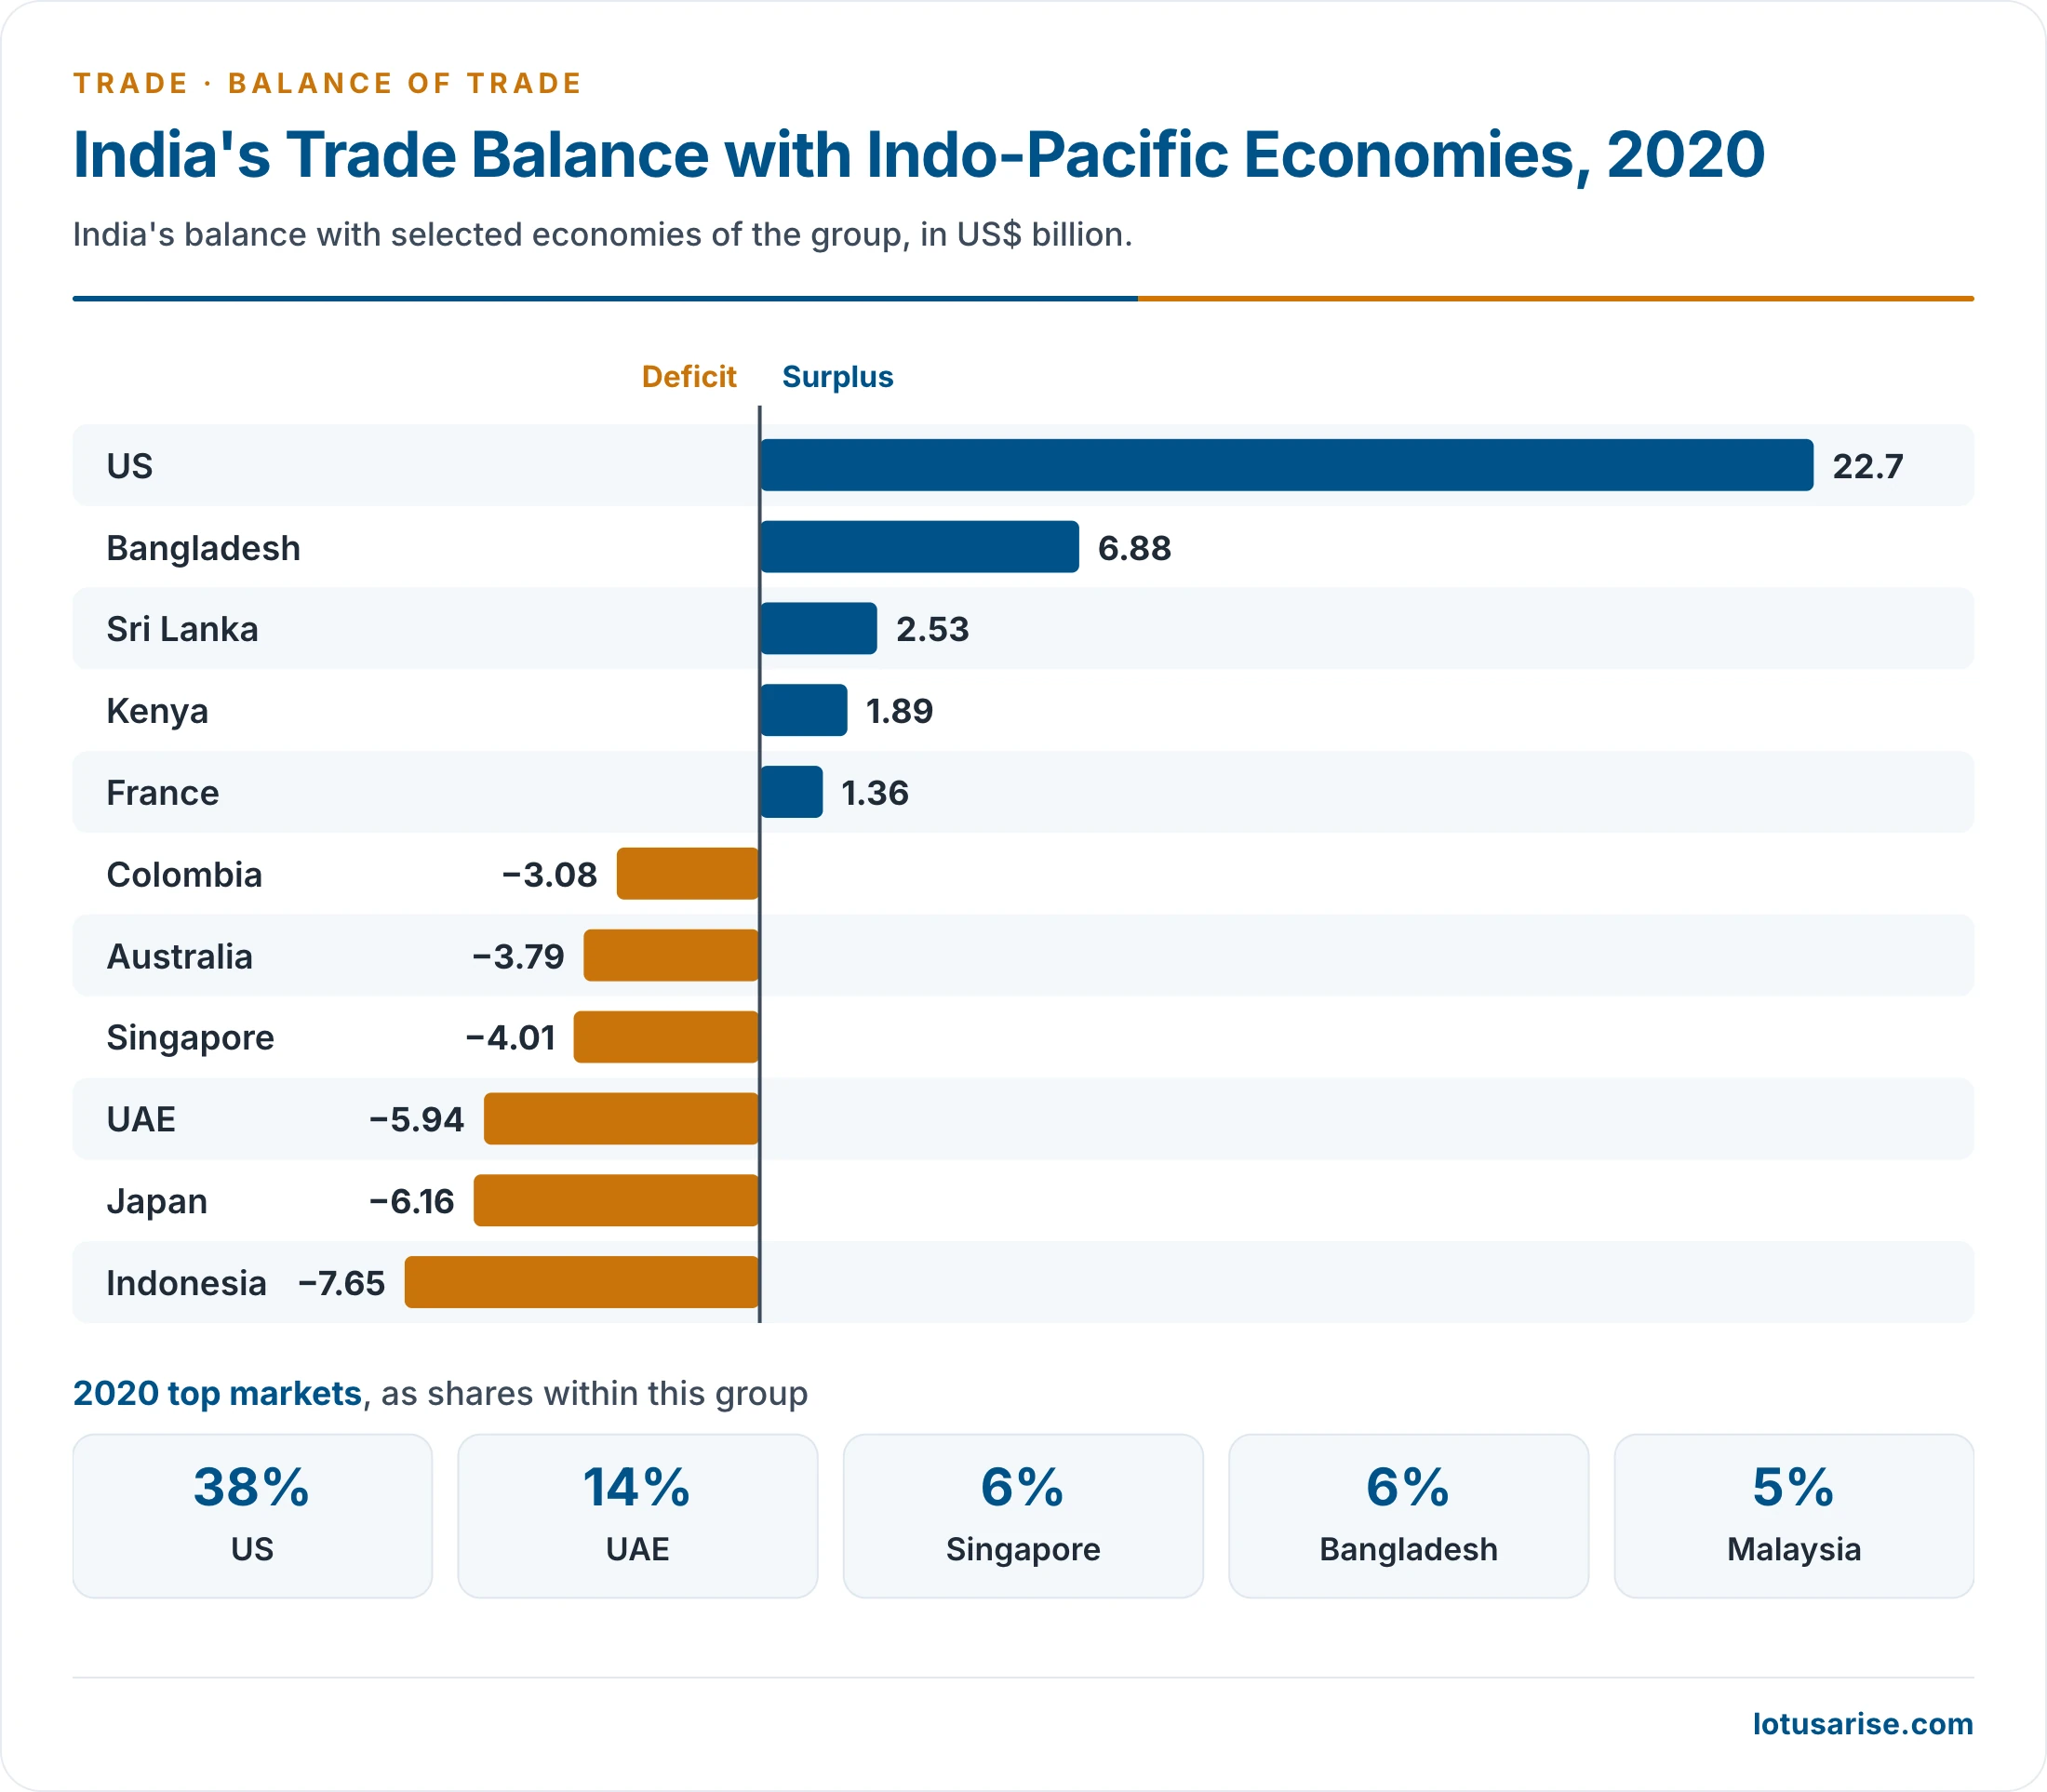
- The panel gives India’s 2020 balance with economies in that group, so its market shares (US 38%, UAE 14%) are shares within the group, and the US share of all Indian exports was much smaller.
India’s Trade Deficit
- North-East Asia (NEA), made up of China, Japan, Korea RP, Hong Kong, Taiwan and others, shows how concentrated the deficit is. In 2015-16:
- Trade with NEA was US$ 124.95 billion, 19.42% of India’s total trade.
- Exports to it were US$ 30.84 billion (11.76% of India’s exports), and imports from it US$ 94.11 billion (24.7% of India’s imports).
- The deficit with NEA was US$ 63.28 billion, or 53.3% of India’s total trade deficit of US$ 118.72 billion.
- China held 56.6% of NEA’s trade with India, Hong Kong 14.5%, Korea 13.3% and Japan 11.6%. Taiwan, Mongolia, Macau and DPR Korea made up the remaining 4%.
- China was 10.99% of India’s total trade but over 44.38% of its trade deficit.
- The NEA economies are among the most dominant in the world, with total exports of US$ 4,233 billion and imports of US$ 3,548.7 billion, or US$ 7,781.6 billion of trade.
- China, Korea, Taiwan and Hong Kong are high-growth economies and potential investment partners.
- Engagement with NEA is integral to India’s Act East Policy, which seeks to widen economic ties beyond the traditional spheres of North America and Europe. It succeeded the Look East policy of the 1990s.
- ASEAN is the other major eastern partner, and India’s trade agreement with it took effect in goods in 2010. It has also added to India’s deficit.
Balance with China
| Year | Deficit (US$ billion) | Notes |
|---|---|---|
| 2019-20 | 48.65 | Exports 16.61, imports 65.26 |
| 2021-22 | Over 73 | A then-record gap |
| 2022-23 | 83.2 | |
| 2023-24 | About 85 | Exports 16.65, imports 101.75 |
| 2024-25 | 99.2 | Exports 14.25, imports 113.45 |
| 2025-26 | 112.16 | Exports 19.47, imports 131.63 |
| April–September 2026 | 68.93 | Exports 11.41, imports 80.34 |
- Why it is so large: China supplies electronics, machinery, solar cells and wafers, and bulk drug ingredients, many of which feed India’s own assembly and exports. India sells it mostly lower-value goods.
- Why it matters: it joins a trade gap with a strategic dependence, which is why import substitution has focused on electronics, solar and active pharmaceutical ingredients.
Salient Features of India’s Foreign Trade
| Feature | Older account | Now |
|---|---|---|
| Negative balance | Persistent since Independence, as growth needed heavy imports | Goods deficit of about US$ 333 billion, offset in part by services |
| Export diversity | Tea, jute, cotton textiles and leather gave way to over 7,500 commodities | Engineering, petroleum products, electronics and pharmaceuticals lead |
| Worldwide reach | Exports to about 190 countries and imports from 140 | Still global, though the top 25 partners hold 77.6% of goods trade |
| Changed imports | Foodgrains and manufactures gave way to oil | Oil, electronics and gold lead |
| Maritime trade | About 95% moves by sea | About 95% by volume and 70% by value |
| Few ports | 13 major ports handled most of it | The major sea ports handled 53.5% of port cargo in 2024-25, and non-major ports such as Mundra the rest |
| Small world share | Under 1%, with over 17% of world population | 1.8% of goods exports and 4.3% of services exports (2024) |
| State trading | State agencies handled most trade | Private exporters dominate since the 1991 reforms |
- Land routes are limited.
- Lofty mountains separate India from China, Nepal and Myanmar.
- The easy land route to Pakistan has carried little trade because of strained relations, though exports there surged for a while from 2004.
- A large country trades much within itself, so a low foreign trade share partly reflects a big internal market. Trade among small European states counts as foreign trade.
Internal and Inter-regional Trade
- Inter-regional trade moves goods between parts of India, reflecting differences in resources and in the stage of development.
- Coal, ores, cement and fertilizer are carried by rail from mineral and port regions to industrial and farm regions.
- Foodgrains flow from surplus States of the north-west to deficit States of the east and south.
- Manufactures flow outward from the industrial regions and ports.
- Brian J. L. Berry (1966) used rail commodity flows between 36 trade blocks to outline India’s functional economic regions.
- Rural market centres, including periodic markets, link villages with towns. They gather farm surplus for regional trade and distribute manufactures in return.
- Goods and Services Tax, in force since 2017, and better road and rail links have lowered barriers within the country.
Previous Year Questions
2023Highlight the salient features of India’s trade policy. Discuss the status of India’s balance of trade with China.2021Critically assess the status of the balance of trade in India and suggest some measures to combat the issues.2019With special reference to India, examine the changes in the nature and patterns of international trade. Mention the major influencing factors.2018Account for the persisting negative trade balance of India.2018Discuss the changing composition of international trade through major seaports of India.2016Analyse the pattern of India’s trade with the South-East Asian countries.2015How has India’s ‘Look East’ policy taken shape in the past two decades and how may it affect India’s external trade?2000Analyse the recent trends in Indian International trade.1999Role of rural market centres in fostering intra and inter-regional trade in India.1997Discuss the nature of commodity flows in India.1995Role of rural market centres in promoting intra and inter-regional trade.1993Discuss briefly the overall pattern of inter-regional trade in India.





Need updated data! Great content otherwise. Keep it up.
Sir your content is best , but please update it …..