

- Aluminium smelting is India’s second most important metallurgical industry, after iron and steel.
- India had 41.45 lakh tonnes of smelter capacity and 74.75 lakh tonnes of alumina capacity in 2023-24, and produced 4,159 thousand tonnes of aluminium. It ranked 2nd in the world, as it also did in 2020.
- Its geography rests on one chain: bauxite to alumina near the mines, alumina to metal near cheap power.
Aluminium Industry
Character and Uses
- Properties: a good conductor of electricity and heat, elastic and flexible, and easily shaped into any form.
- Uses:
- Production and distribution of electricity.
- Household utensils and electric appliances.
- Aeroplanes, railway coaches and bus bodies.
- Nuclear and defence accessories.
- Building, packaging and coinage.
- It increasingly replaces steel, copper, zinc and lead in many uses.
- Fastest growing metal: it grew nearly 20 times in sixty years, against 6 to 7 times for other metals, on one older comparison. It remains the fastest growing non-ferrous metal in India.
- Two segments:
- Upstream: primary aluminium made from raw materials, starting with bauxite mining.
- Downstream: primary metal processed into semi-finished goods such as rods, bars, castings and forgings, along with sheet, foil and extrusions.
- Consumption pattern in 2003 differed sharply from the world’s:
| Sector | World (%) | India (%) |
|---|---|---|
| Electrical and electronics | 9 | 32 |
| Transport | 31 | 18 |
| Construction | 18 | 16 |
| Packaging | 17 | 12 |
| Consumer durables | 6 | 6 |
| Industrial machinery | 9 | 4 |
| Powders and chemicals | – | 6 |
| Others | 10 | 6 |
- Per capita use: barely 500 grams in an older count, against 5.9 kg in the USA and 3.6 kg in Brazil. Industry estimates put it near 4 kg in 2025, against about 11 kg worldwide.
Raw Material: Bauxite
- Bauxite is the raw material. It is bulky, so moisture and impurities should be removed before the ore travels long distances.
- Output is now far more concentrated than older accounts show. Total resources were 4,958 million tonnes in 2020, and output was 23.97 million tonnes in 2023-24.
| State | Older account | Now |
|---|---|---|
| Odisha | Largest, over half of output; 1,370.5 million tonnes recoverable | 73.4% of output (2023-24); 41% of resources (2020) |
| Jharkhand | 63.5 million tonnes recoverable, all grades | 8.5% of output; 289 million tonnes of resources |
| Maharashtra | About 10% of output; 87.7 million tonnes recoverable | 4.4% of output; 5% of resources |
| Chhattisgarh | More than 6% of output | 4.3% of output; 20% of resources |
| Madhya Pradesh | A main producer | 2.5% of output; 4% of resources |
- Where the ore lies:
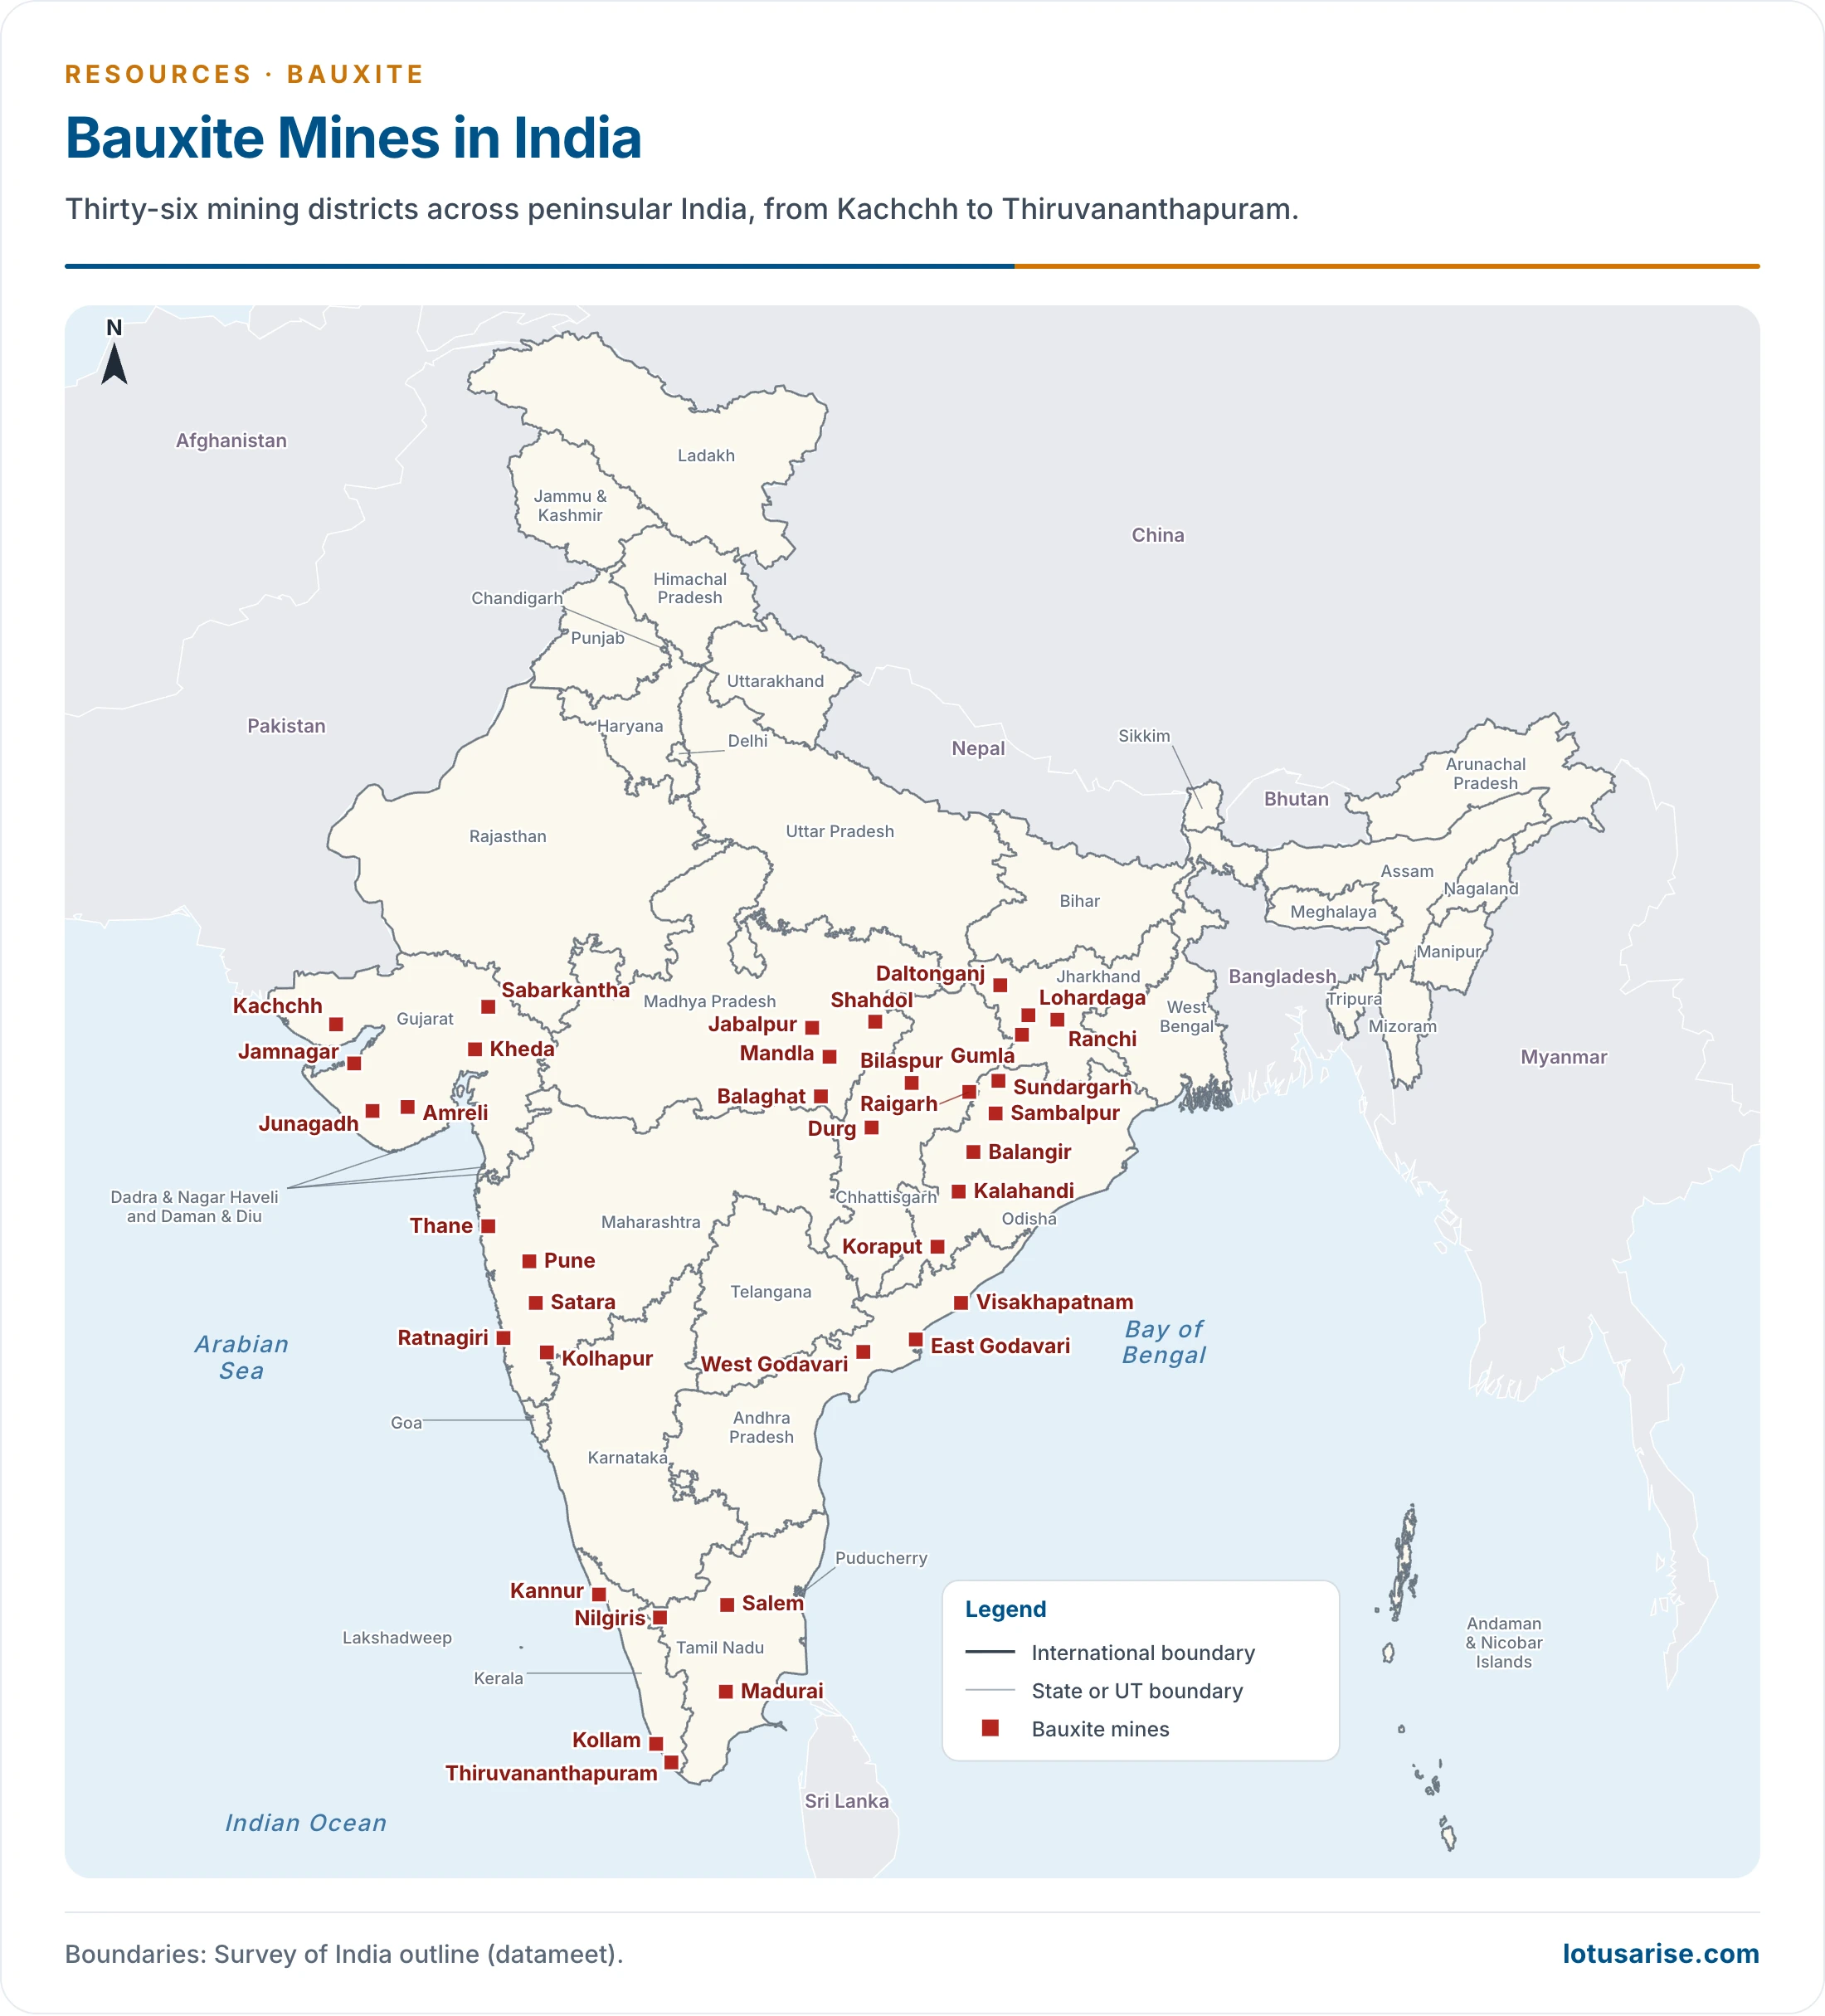
- Odisha: the main belt is in Kalahandi and Koraput, and it continues into Andhra Pradesh.
- Jharkhand: spread over Ranchi, Lohardaga, Palamu and Gumla, with some in Dumka and Munger. Lohardaga and its surroundings have high-grade ore.
- Maharashtra: the largest deposits are in Kolhapur, capping the plateau basalts. Udgeri, Dhangarwadi, Radhanagari and Inderganj have rich ore, with 52–89% alumina.
- Chhattisgarh: the Maikala range in Bilaspur and Durg, and the Amarkantak plateau of Surguja, Raigarh and Bilaspur.
- Madhya Pradesh: the Amarkantak plateau, the Maikala range in Shahdol, Mandla and Balaghat, and Katni, formerly part of Jabalpur district.
- Smaller sources:
- Andhra Pradesh: Visakhapatnam, East Godavari, West Godavari.
- Keralam (Kerala): Kannur, Kollam, Thiruvananthapuram.
- Rajasthan: Kota.
- Uttar Pradesh: Banda, Lalitpur, Varanasi.
- Jammu and Kashmir: Jammu, Poonch, Udhampur.
- Goa.
Location Factors
- The two stages locate differently:
- Alumina refineries stand near the mines, because the ore loses much weight.
- Smelters need very large amounts of electricity, so they stand near cheap power, and most Indian smelters also stand near their refineries.
- Input ratios: about 6 tonnes of bauxite give 2 tonnes of alumina, which give 1 tonne of aluminium.
- Other inputs per tonne of metal: about 0.26 tonnes of caustic soda and 0.09 tonnes of lime, with small amounts of cryolite, aluminium fluoride, calcium fluoride, calcined anthracite and soda ash.
- Electricity: an older figure is 18,573 kWh per tonne. Power makes up about 30–40% of production cost, or 30–35% on a lower estimate, and this makes affordable power essential.
- Power sources:
- Smelters often stand close to large power stations, and hydroelectric sites were favoured for lower carbon footprints: Hirakud, Rihand at Renukoot, and Mettur.
- Indian smelters now mostly run on their own captive thermal power, which ties them to coal.
- Site shortage: the industry’s need for very cheap power has long limited the sites that suit it.
- Odisha is now the centre of gravity, with Jharsuguda, Angul, Aditya and Hirakud smelters and three large refineries.
| Refinery | State | Company | Alumina capacity (thousand tonnes) |
|---|---|---|---|
| Damanjodi | Odisha | NALCO | 2,275 |
| Lanjigarh | Odisha | Vedanta | 2,000 |
| Utkal Alumina | Odisha | Hindalco | 1,500 |
| Renukoot | Uttar Pradesh | Hindalco | 700 |
| Muri | Jharkhand | Hindalco | 450 |
| Belagavi | Karnataka | Hindalco | 350 |
| Korba | Chhattisgarh | BALCO | 200 |
Aluminium Production Process
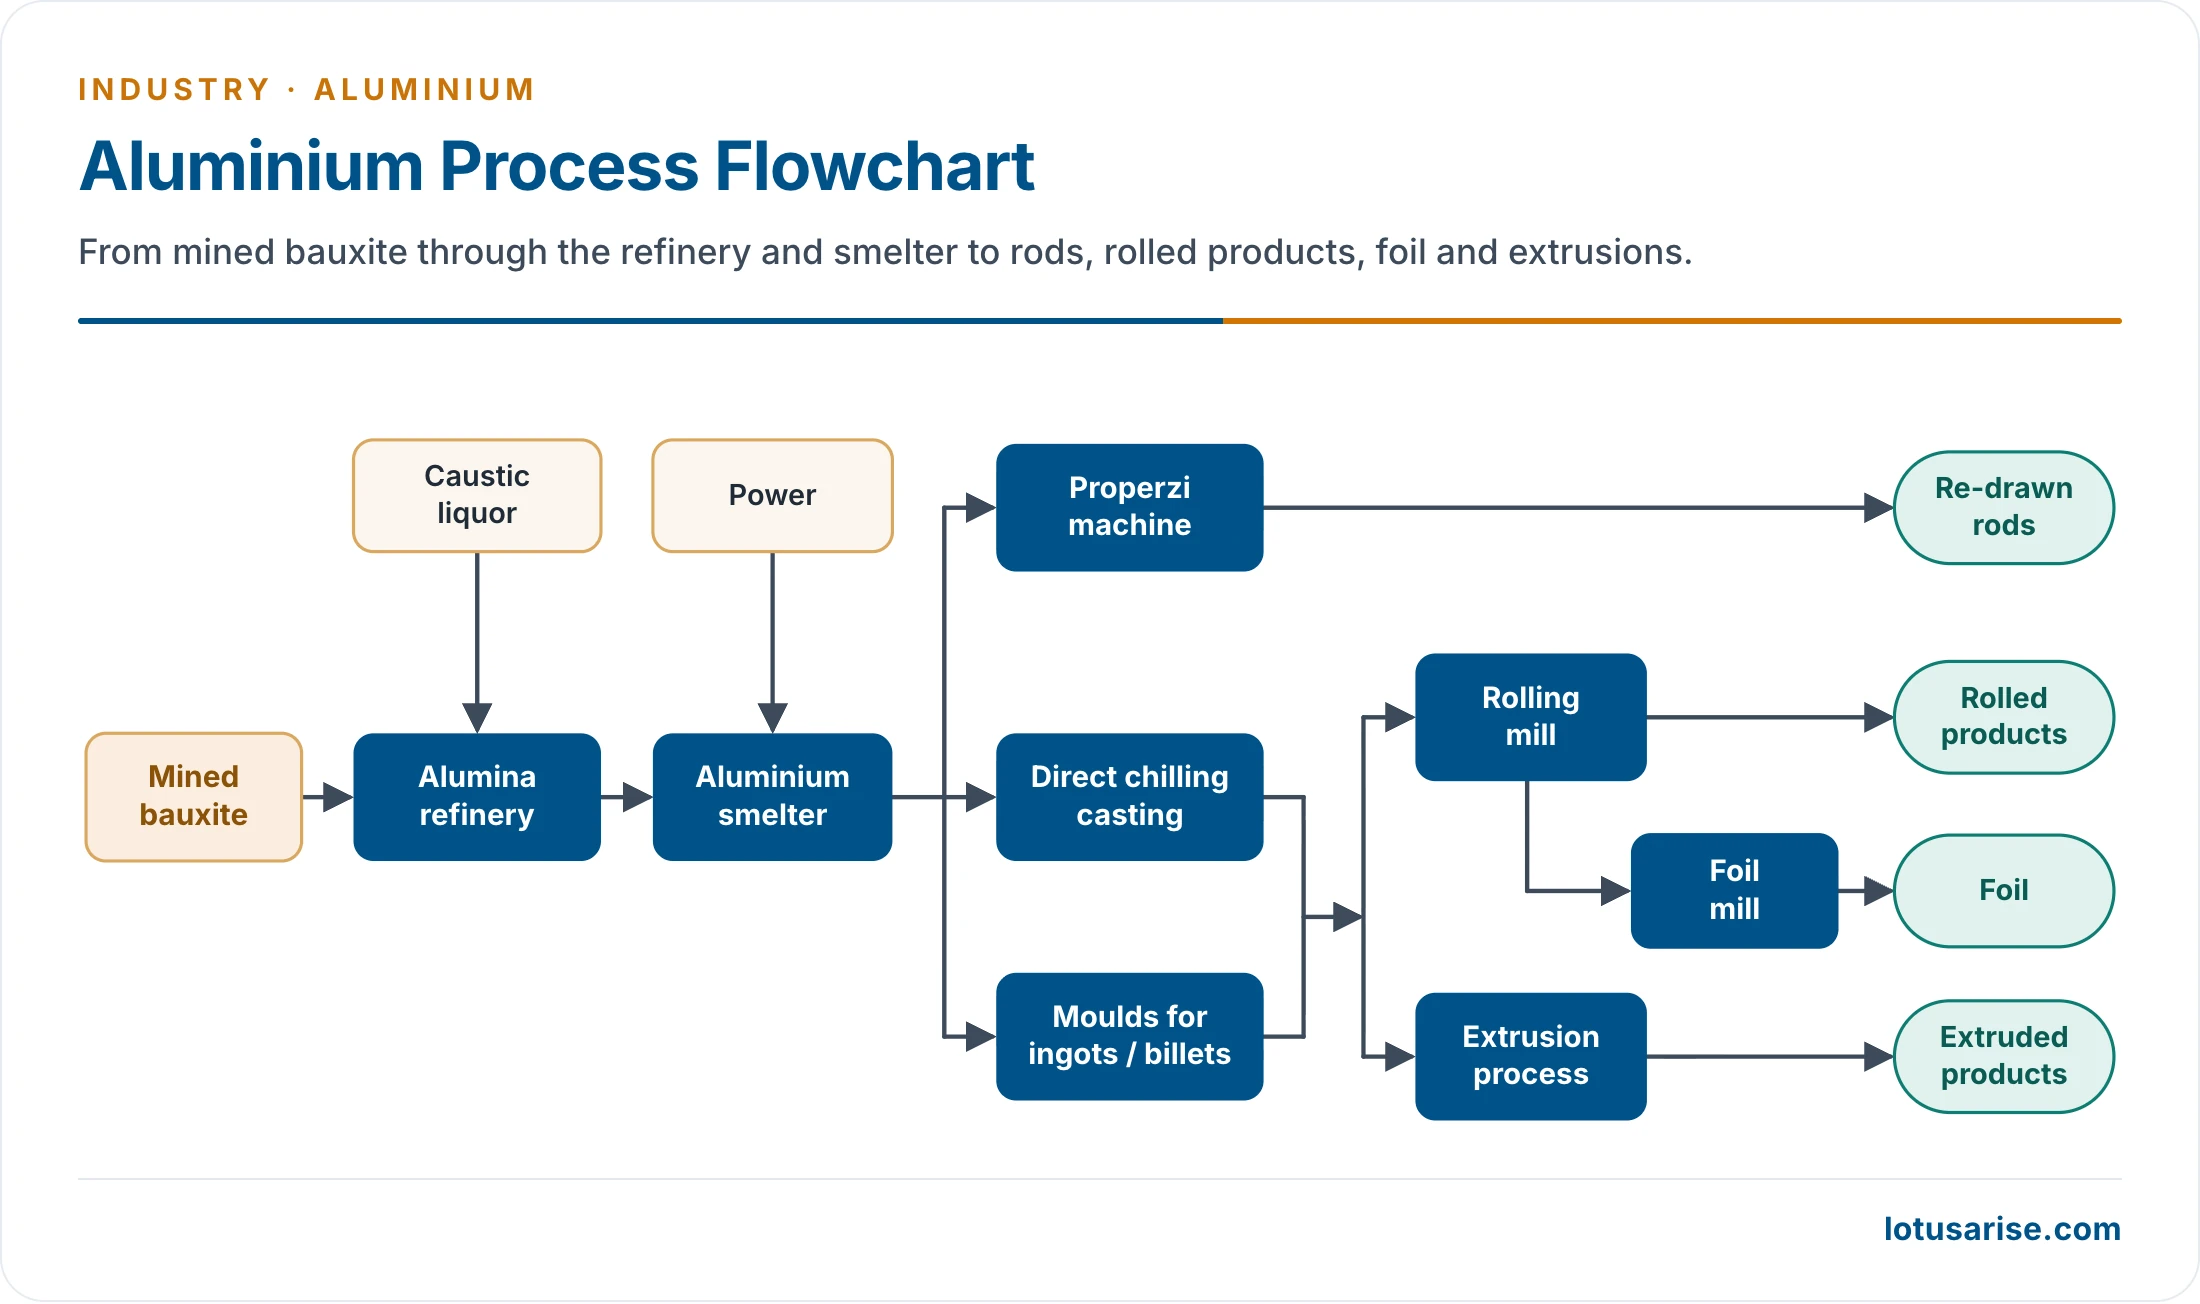
- Refining (Bayer process, Carl Josef Bayer): crushed and milled bauxite meets caustic soda in a pressure vessel at about 170–180°C. Filtering leaves behind red mud. Crystallisation gives aluminium hydroxide, and a rotary kiln turns that into alumina.
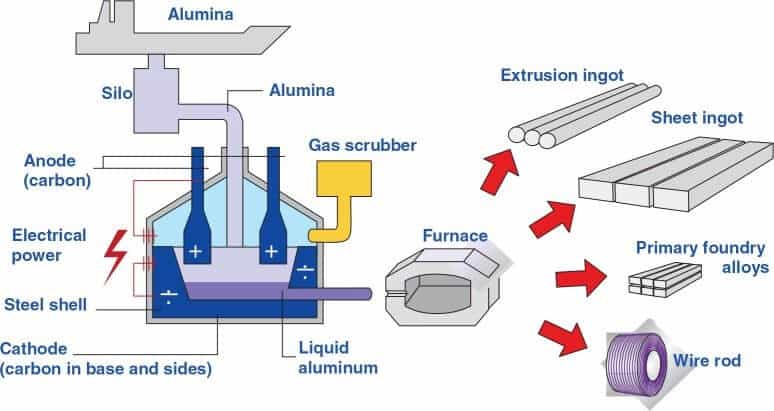
- Smelting (Hall-Héroult process, Charles Martin Hall and Paul Héroult): alumina is reduced to metal by electrolysis in carbon-lined cells, at a smelter. This step takes the huge electricity load.
- Finishing: molten metal is cast into ingots, billets and slabs, then rolled, extruded or drawn into sheet, foil, rods and wire.

Aluminium Smelting Plants in India
| Location | State | Company | Smelter capacity, 2023-24 (thousand tonnes) |
|---|---|---|---|
| Jharsuguda | Odisha | Vedanta Aluminium (VAL) | 1,750 |
| Korba | Chhattisgarh | Bharat Aluminium Co (BALCO) | 590 |
| Angul | Odisha | National Aluminium Co (NALCO) | 460 |
| Renukoot | Uttar Pradesh | Hindustan Aluminium Co (HINDALCO) | 410 |
| Aditya | Odisha | HINDALCO | 360 |
| Mahan | Madhya Pradesh | HINDALCO | 359 |
| Hirakud | Odisha | HINDALCO | 216 |
| Alupuram | Keralam | HINDALCO | Smelter closed in 2003 |
| Mettur | Tamil Nadu | Madras Aluminium (MALCO) | Smelter closed in 2008 |
- Korba has since grown. A new potline of 0.435 million tonnes, using 525 kA cells, took BALCO to 1 million tonnes in October 2025.
- Production:
| Year | 1950-51 | 1960-61 | 1970-71 | 1980-81 | 1990-91 | 2000-01 | 2006-07 | 2011-12 | 2021-22 | 2023-24 |
|---|---|---|---|---|---|---|---|---|---|---|
| Thousand tonnes | 4.0 | 18.5 | 168.8 | 199.0 | 451.1 | 620.4 | 1,061.2 | 963.2 | 4,016 | 4,159 |
- Output rose slowly during the first three Plans, then reached a first peak in 2006-07. Power shortages and interrupted bauxite supply then held it back, before large new smelters opened in Odisha and elsewhere.
Evolution of Aluminium Industries in India
- It is among the youngest of metal industries. Commercial production became possible only with the electrolytic process of 1886.
- Bauxite is abundant across the earth’s crust, but sizeable concentrations are rare.
- Fabrication of utensils from imported metal began in India in 1929.
- 1937: the Aluminium Corporation of India was formed, but its first venture was delayed. It was the first real attempt to make aluminium in India.
- 1938: the Indian Aluminium Company (INDAL) began production at Alupuram, Kerala. In 1940 the government gave it support through import tax exemption and a heavy duty on imported aluminium.
- 1942: the Aluminium Corporation began producing alumina at Jaykaynagar, West Bengal, and metal followed in 1944.
- The Second World War gave the industry its push. These two firms remained the only producers until 1960.
- Second Five Year Plan:
- INDAL added Hirakud, Odisha. It had rolled sheets from imported alumina since 1943, and had refined Indian bauxite since 1948.
- HINDALCO was set up at Renukoot, Uttar Pradesh, in 1958.
- Third Five Year Plan:
- MALCO, operating since 1965, at Mettur, Tamil Nadu.
- BALCO, established in 1965, at Korba, Chhattisgarh, in the public sector.
- 1970: INDAL set up a plant at Belgaum (Belagavi), Karnataka.
- 1981: NALCO was formed. Commercial production began in 1988-89.
- Reform: the industry was decontrolled in 1989 and gained further from liberalisation in 1991.
Aluminium Industries in India
- On this chart, “Alluminium Cooperation” should read Aluminium Corporation.
- Hindustan Aluminium Company (HINDALCO), Renukoot:
- Set up in 1958. All of its production facilities for alumina, metal and fabricated goods are at the Rihand dam in Sonbhadra, Uttar Pradesh.
- It was long described as India’s largest integrated primary producer and Uttar Pradesh’s biggest industrial enterprise.
- Bauxite: from Lohardaga (Jharkhand) and Amarkantak, on the Madhya Pradesh–Chhattisgarh border.
- Renukoot is Hindalco’s largest smelter, within a group capacity of 13.45 lakh tonnes.
- Jaykaynagar, near Asansol, West Bengal (Aluminium Corporation of India):
- The first to make aluminium from Indian bauxite. Registered in 1937, it made alumina from 1942 and metal from 1944.
- It ran a captive coal mine and thermal station, along with alumina, reduction, sheet rolling and utensil units.
- Kolkata provided its market.
- Bharat Aluminium Company (BALCO), Korba:
- Established in 1965, with Soviet help. Its first plant, of one lakh tonnes, made alumina from 1973 and metal from about 1975.
- Bauxite came from the Phutkapahar region and Amarkantak.
- Other units: Bidhanbag near Asansol, gained by nationalisation in 1984, and Ratnagiri (Maharashtra), listed with 50,000 tonnes.
- Disinvestment: the government sold 51% to Sterlite Industries in March 2001. It is now in the Vedanta group, with the government holding the rest.
- National Aluminium Company (NALCO):
- Formed in 1981. Its integrated complex has its refinery at Damanjodi, near Jeypore in Koraput district, with bauxite from Panchpatmali.
- Smelter: at Angul, then in Dhenkanal district. It started at about 2,18,000 tonnes and now has 4.6 lakh tonnes.
- State-of-the-art facilities, and long called India’s largest bauxite–alumina–aluminium complex.
- Exports: more than 3.75 lakh tonnes of alumina, through Visakhapatnam port.
- Expansion: bauxite mining went from 48 to 63 lakh tonnes and alumina from 15.75 to 21 lakh tonnes, with captive power of 1,200 MW.
- Standing: it has been called the world’s lowest-cost producer, among the top 10 companies, and second to Hindalco in India. By 2023-24 smelter capacity, Vedanta (with BALCO) and Hindalco were both larger.
- Plans: a fifth refinery stream to reach 3.1 million tonnes of alumina, and a new 0.5 million tonne smelter at Angul by about 2030-31.
- Madras Aluminium Company (MALCO), Mettur: operating since 1965, with power from the nearby Mettur dam. Its smelter has been closed since December 2008.
- Indian Aluminium Company (INDAL): plants at Alupuram and Hirakud. It merged into Hindalco in 2004.
- Vedanta Aluminium, Jharsuguda: the largest smelter site in India, with 17.5 lakh tonnes of capacity. It cast 1.83 million tonnes in 2024-25.
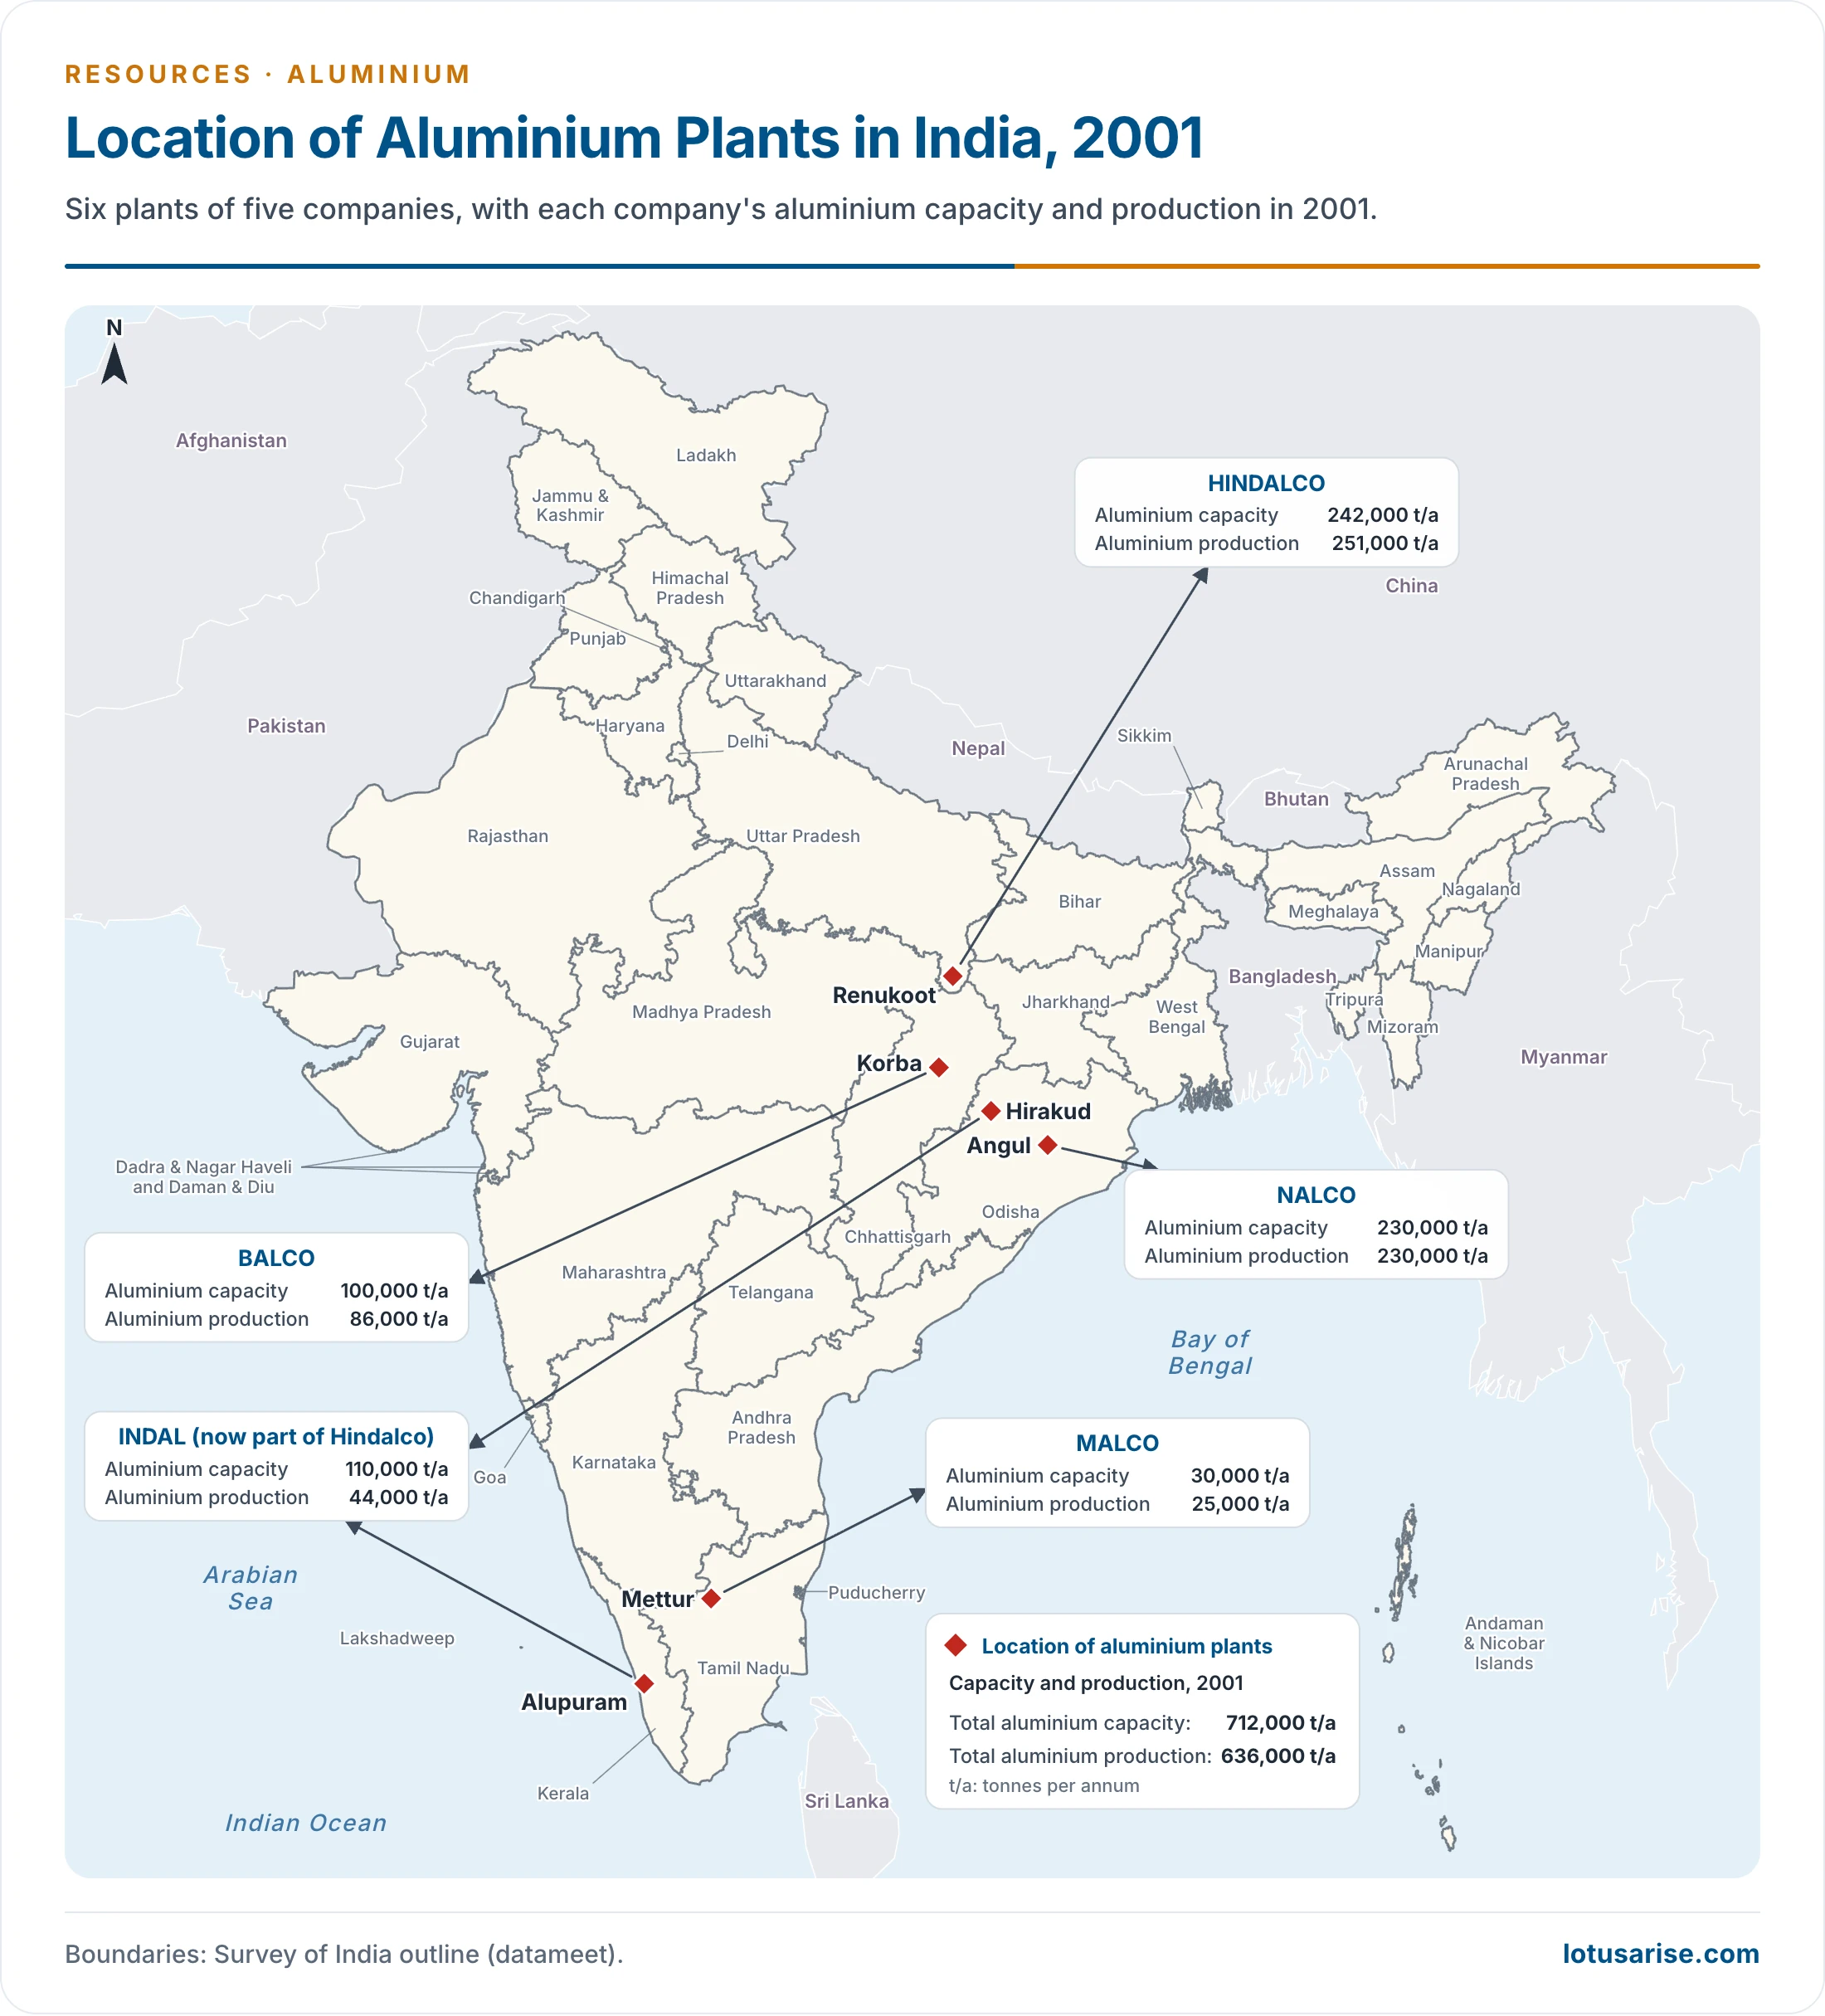
- The capacities on this map are for 2001, when the total stood at 7.12 lakh tonnes. The total was 41.45 lakh tonnes in 2023-24, Jharsuguda does not appear, and INDAL is now part of Hindalco.
Problems of Aluminium Industry in India
- Power: high cost and shortage of power are the major hurdles, and the lack of cheap power has been a main brake on growth.
- Production bottlenecks:
- Dislocation of supply from the grid.
- Total stoppage of power.
- The response has been for smelters to build their own thermal power plants, which raises their exposure to coal cost and carbon rules.
- Old technology: smelters that are decades old use more power and cost more to run.
- Bauxite left unused:
- Vast east coast deposits long lay idle after their discovery.
- Refineries at Damanjodi, Lanjigarh and Rayagada now use this belt.
- Mining can still be refused. All 12 gram sabhas rejected bauxite mining in the Niyamgiri hills in 2013, after a Supreme Court order, and Gandhamardan was abandoned earlier.
- India imported 4.49 million tonnes of bauxite in 2023-24.
- Controlled prices: the industry once sold to State electricity boards at unremunerative prices, and control reached commercial grade metal too. This eroded profits until the decontrol of 1989.
- Costly inputs: high input costs make it hard to compete abroad.
- Imported inputs: essential materials such as cryolite and fluoride are still imported.
- Demand and supply:
- An older picture had demand above 1 million tonnes a year against output of about 0.5 million tonnes, with a shortage of primary metal for core sectors.
- Output is now over 4 million tonnes. Imports have grown too, mainly because demand has risen across many sectors.
- Barriers to entry:
- Economies of scale: costs, chiefly power, fall as size rises, so small plants struggle.
- Huge capital: small entrepreneurs cannot enter easily.
- Long set-up time: a plant of BALCO’s size takes about 3–4 years to work.
- Control over mines: existing players hold the known bauxite mines, which affects ore prices for others.
- Scarcity of power: as above, a basic constraint on growth.
- Government factors: environmental clearance and the allotment of mines take long.
- Land: existing players can expand on brownfield sites more easily than a newcomer can start a greenfield one.
- International competition: India’s bauxite grade is good, but output and product quality have lagged Australia, Canada, France and the USA.
- Labour: strikes and unrest have also held the industry back.
- Outlook: the Ministry of Mines’ vision document of 4 July 2025 aims at a sixfold rise in output by 2047, bauxite capacity of 150 million tonnes, and a doubling of recycling.
Previous Year Questions
- No direct PYQ has been asked on this sub-topic yet.





*2nd most important metallurgical industry
*Gujrat ranks 2nd in Bauxite production ,you didnt mention it here .
https://lotusarise.com/bauxite-distribution-in-india-upsc/
China is leading (1st) in aluminium production.
very useful and informative blog for beginners like me thank you for sharing.
Very well written document with diagrams and data and current prospects of the industry.
Very Useful Information About Best Aluminium Industry in India
I’m Really Enjoyed it…