

- The pulp and paper industry covers firms that turn wood and other cellulose into pulp, paper, paperboard and related products.
- A forest-based industry: large parts of its raw material still come from forests, though some treat it as a chemical industry for its process, and others as agro-based for its use of crop residues.
- Paper is a core industry. Consumption per head serves as a measure of literacy, education, industrial culture and general well-being.
Paper in the World and in India
World Picture
- One of the world’s largest industries, dominated by North America, Northern Europe and East Asia, with significant output in Latin America and Australasia.
- World output of paper and paperboard:
- Older figures put it at about 390 million tonnes, with 490 million tonnes expected by 2020. Global consumption was 371 million tonnes in 2009.
- Output was about 420 million tonnes in 2023, well short of that forecast.
- Packaging now leads, at about 265 million tonnes in 2022, while graphic papers fell to 84 million tonnes in 2023, their lowest since 1987.
- India and China were expected to become the key countries in the industry’s growth.
Indian Standing
| Measure | Older figure | Recent figure |
|---|---|---|
| Mills | 17 (1950-51); 759 (2012-13), 652 of them working | Over 900, of which 526 working (2025) |
| Capacity | 1.37 lakh tonnes (1950-51); 12.7 million tonnes (2012-13) | About 25 million tonnes (2025) |
| Consumption per head | About 2 kg, then 5.5 kg | About 15 kg (2025) |
| World average per head | Nearly 50 kg | 58 kg (2025) |
| Revenue | Rs 16,000 crore | Rs 80,000 crore (2023-24) |
| Imports of paper and board | 55.6 thousand tonnes (1960-61); 2.76 million tonnes with manufactures (2013-14) | 2.05 million tonnes of paper and paperboard (2024-25) |
- Rank: India is about the 15th-largest producer, with about 5% of the world market, and the fastest-growing major paper market.
- Consumption elsewhere (2025): USA about 320 kg, European Union 129 kg, China 75 kg and Asia 45 kg.
- Highly developed countries were put at more than 200–300 kg in older accounts.
- An increase of 1 kg per head adds about 1 million tonnes to Indian demand.
- Jobs (older): about three lakh direct and 10 lakh indirect.
- Policy: licensing ended in July 1997, and foreign investment of up to 100% needs no prior approval.
Growth and Development
- Handmade beginnings: papermaking in India goes back to about the 10th century, under Muslim rulers, as a cottage craft of traditional makers called kagzis, who worked with rags, ropes and old gunny.
- Factory paper later crushed most of this craft, though many small units still make handmade paper.
- Early factories:
- A factory near Chennai (1816) failed.
- William Carey’s mission press at Serampore on the Hugli made its own paper from about 1812-13, and took up a machine in 1832. This venture too did not last as a modern industry.
- The first lasting effort was Royal Bengal Paper Mills at Ballygunge near Kolkata (1870).
- Later mills:
| Year | Place | Mill |
|---|---|---|
| 1879 | Lucknow | |
| 1882 | Titagarh | |
| 1887 | Pune | Deccan Paper Mills |
| 1892 | Raniganj | Bengal Paper Mills |
| 1892 | Kankinara | |
| 1918 | Naihati |
- Other early units stood at Serampore and at Shyamnagar (Indian Paper Pulp).
- Protection and war: preferential treatment and tariff protection helped the young industry, and World War II gave it fresh life. Progress stayed sluggish until Independence.
- Planned development: growth came fast after 1951.
- 1950-51: 17 units produced 0.16 million tonnes.
- A later position: 43 large integrated mills, plus over 300 small and medium mills with capacity of about 18.38–20 lakh tonnes.
- 2012-13: of 12.7 million tonnes of capacity, about 1.37 million tonnes lay idle with 107 units shut, mostly over pollution. Output stood at about 11.8 million tonnes.
- Flagship demand: Sarva Shiksha Abhiyan and the Right to Education gave paper a steady market.
- Rise of the small sector:
- It came to hold about 50% of capacity and output in older accounts.
- During the paper famine of the early 1970s, the government saw the worth of small units.
- Short gestation period
- Cheap second-hand machinery, readily available from abroad
- Non-conventional raw materials: rice and wheat straw, bagasse and jute stalks
- Freedom to set up in almost any part of the country
- Liberal incentives brought these units into production and averted the crisis.
| Mill class (2012-13) | Scale (tonnes a day) | Mills | Share of capacity |
|---|---|---|---|
| Large | 100–1,100 | 119 | 36% |
| Medium | 50–100 | 117 | 29% |
| Small | 5–50 | 523 | 35% |
- Output by grade (thousand tonnes): kraft paper rose from 899 in 2005-06 to 1,263 in 2011-12, and writing and printing paper from 1,974 to 2,867.
- Current market by grade: packaging paper and board about 57–65%, printing and writing about 23–30%, newsprint about 8% and specialty paper about 5%.
- E-commerce and the move away from single-use plastic drive packaging.
Foreign Trade
- Imports: output has fallen short of demand, so large quantities of paperboard and better grades (insulation, parchment and tissue paper) come from Sweden, Canada, Japan, France, Belgium and the USA.
- Paper pulp and waste paper are also imported, from Norway, Sweden, Canada and the Netherlands.
- Older import trend: pulp and waste paper rose from 80.3 thousand tonnes in 1960-61 to 3.29 million tonnes in 2012-13.
- About 25% of wood pulp needs were imported in 2024, from countries such as Brazil and Indonesia.
- New competition: cheaper paper from China and ASEAN countries, helped by free trade agreements, has hurt home producers. The industry association has asked for a duty of 25% in place of 10%.
- Exports: some printing and writing paper, kraft paper, paperboard, and packing and wrapping paper go to the Middle East, East Africa and South-East Asia.
- Newsprint: output of about 5.04 lakh tonnes against imports of 6.65 lakh tonnes in 2023-24.
Growth Pattern
- Paper can be made from many raw materials, so growth has taken a sporadic pattern across several types of unit:
- Large integrated paper mills
- Small mills on non-conventional materials such as bagasse, alone or mixed with pulp
- Small units on waste paper
- Units within large integrated sugar complexes
- Large integrated newsprint units
- Handmade paper units under the Khadi and Village Industries Commission
Manufacture, Raw Materials and Location
Manufacturing
- Paper is made in two stages:
- First stage: pulp is extracted from cellulose. This needs gross raw material, so pulp units sit amid cellulose-producing areas.
- Second stage: pulp is pressed into paper. Pulp is now the raw material, so paper units can locate near urban markets.
- Pulp comes from wood, bamboo, sabai grass, bagasse and crop straw, which explains the industry’s wide distribution.
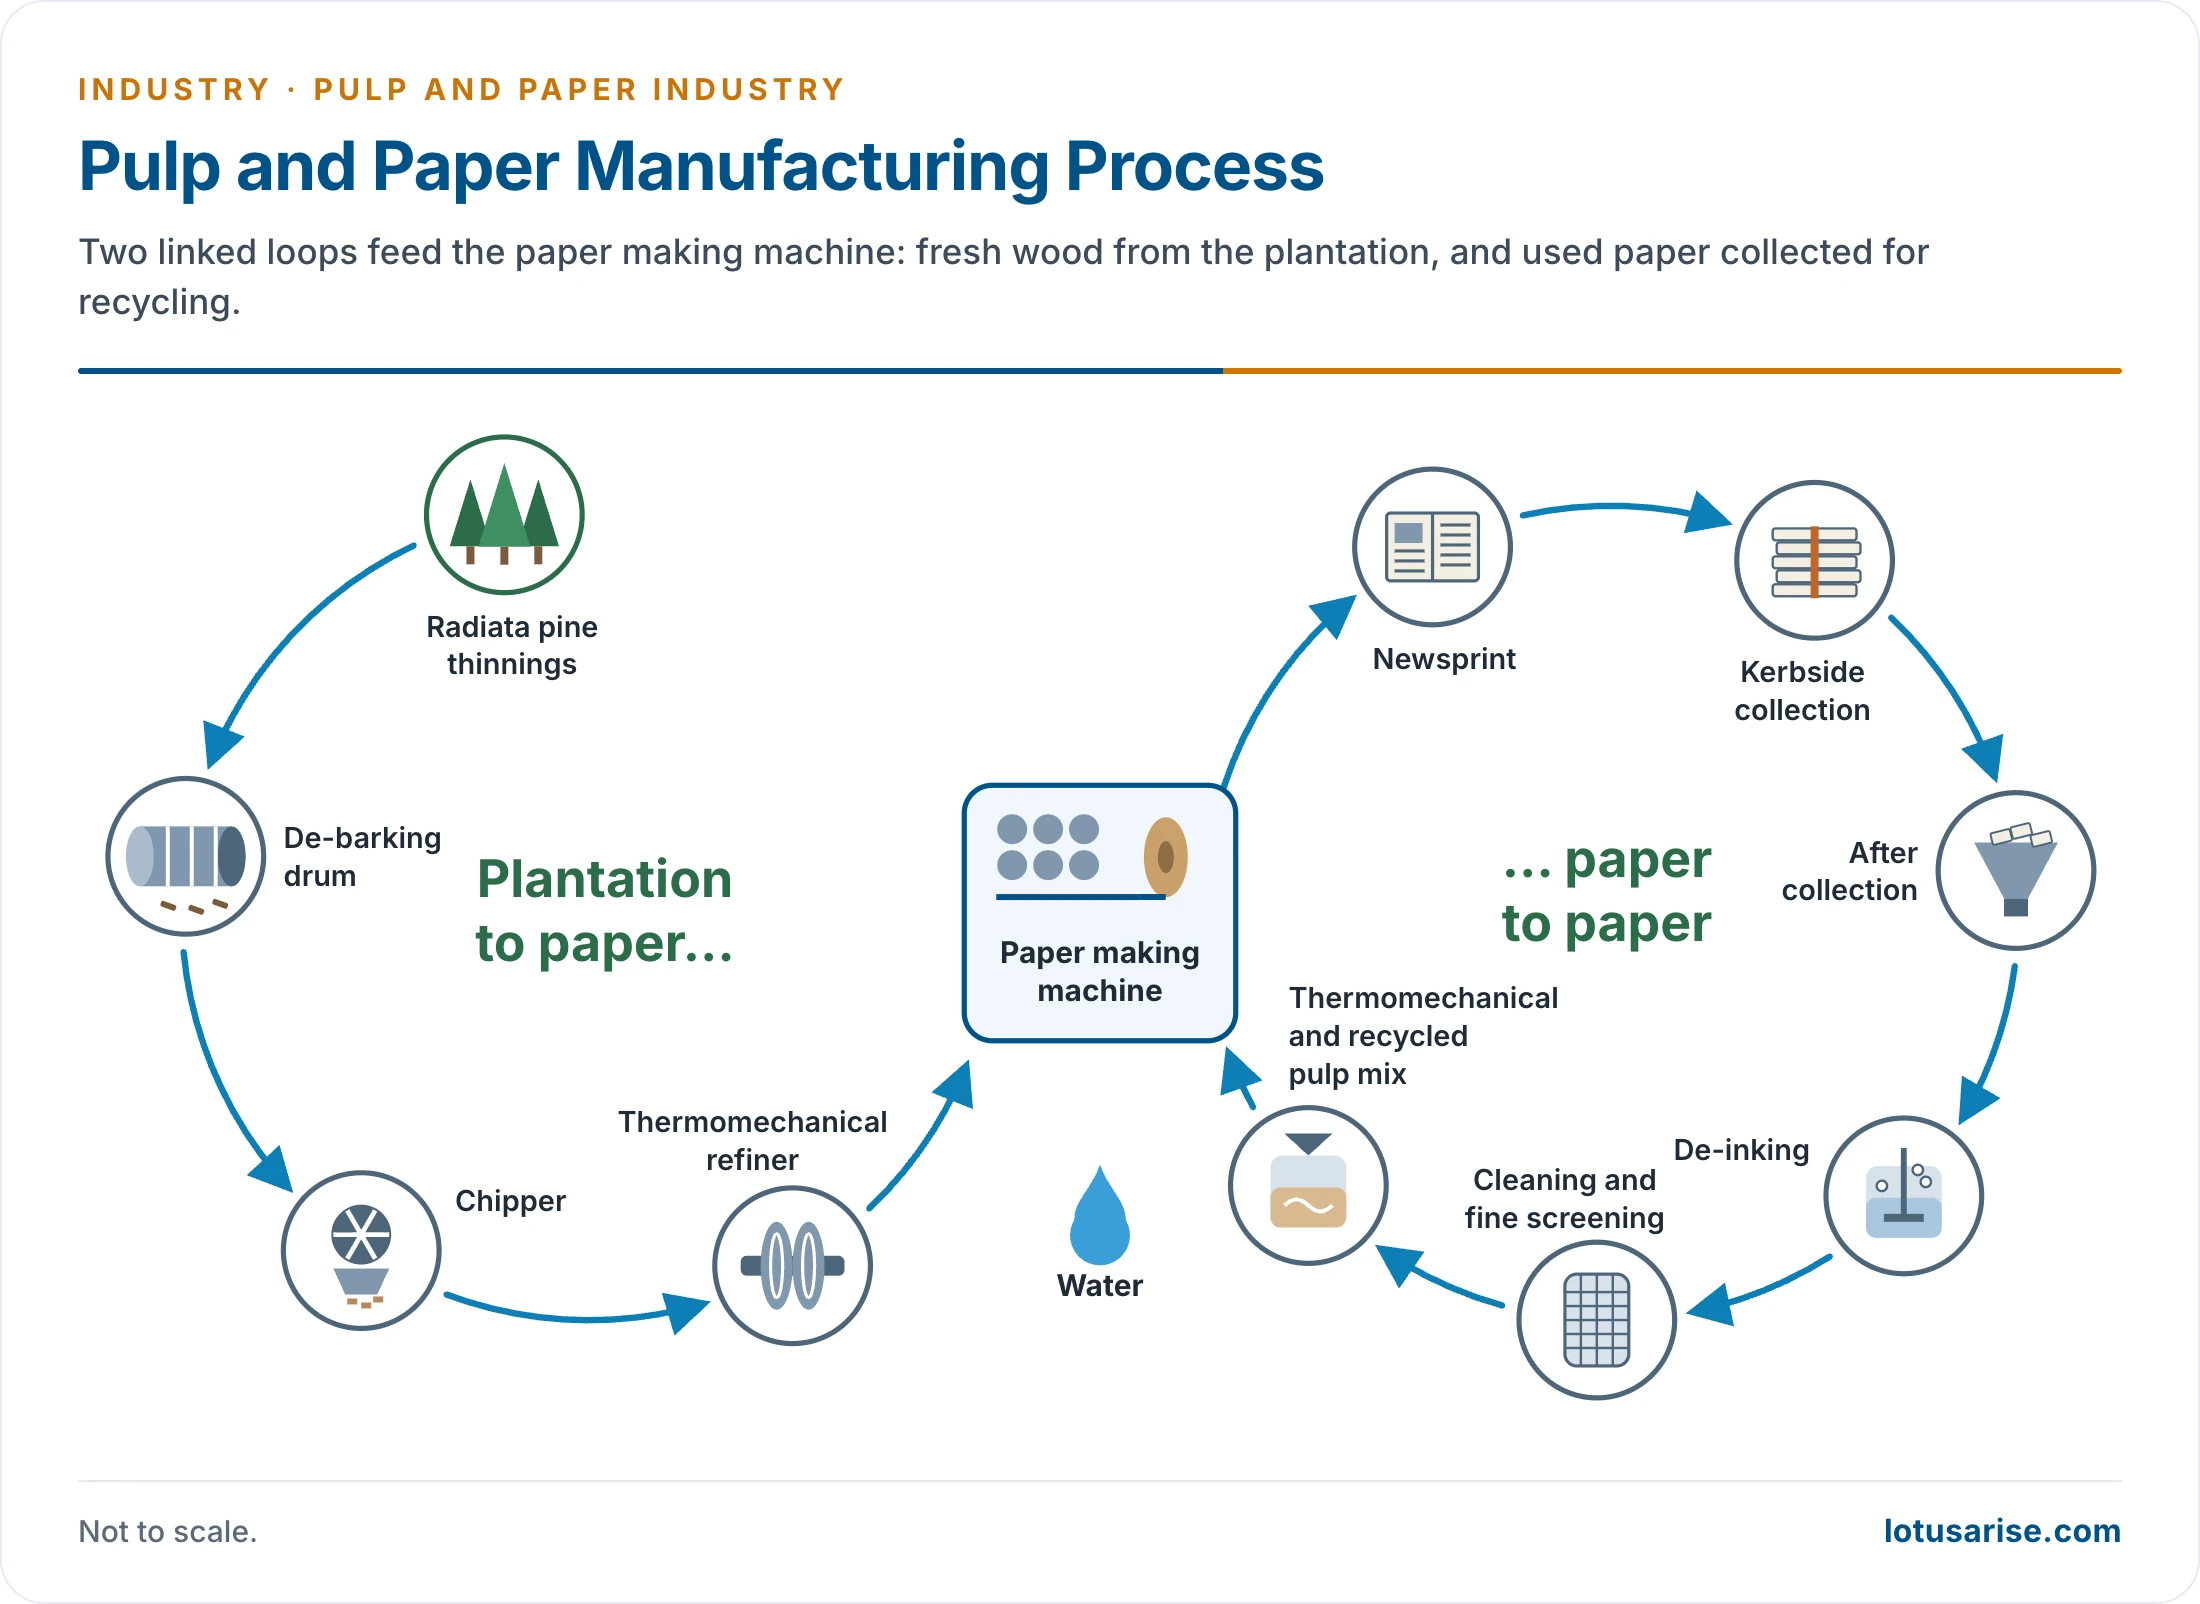
- This cycle is a general one, showing softwood thinnings and recycled newsprint. Indian mills add bamboo, hardwood plantation timber and crop residues.
Raw Materials
- The balance has shifted away from forests:
- Wood use fell from about 80% in the 1980s to about 20% at present by one estimate.
- Current raw material base: recycled paper 52%, wood fibre 28%, agro-residues 20% (2025).
- An older split of installed capacity was 43% forest-based, 28% agro-based and 29% others.
- Raw materials make up 45–50% of the cost of production.
- Bamboo:
- About 2.3–2.4 tonnes make one tonne of paper.
- It was long the main material, at 60–70% of cellulosic needs in older accounts.
- Strengths: long fibre, dense stands and quick regrowth. It matures in 2–3 years, which gives a continuous, renewable flow.
- Limit: stocks may be depleted if cutting outruns regrowth. Supply was estimated at 20–30 lakh tonnes a year.
- Producing States: Assam, Odisha, Andhra Pradesh, Telangana, Madhya Pradesh, Tamil Nadu, Karnataka and Maharashtra.
- Botanically a grass, it counts in law as minor forest produce, and a 2017 amendment freed bamboo grown outside forests from felling and transit permits.
- Sabai grass:
- Until bamboo took over, it was the only raw material. Its share has shrunk to 7–9% of the cellulosic total.
- Strength: long fibre, and little need for chemicals.
- Weakness: it grows in tufts mixed with other plants, so impurities are hard to remove, and its supply is much smaller than that of bamboo.
- With allied grasses, it gives roughly a million tonnes yearly, gathered in the Shiwaliks and the Tarai.
- Bagasse:
- The fibrous residue of crushed cane, mainly from sugar mills.
- Older figure: about 50–60 lakh tonnes a year, half of it used for paper.
- About 96–97% of bagasse is now burnt for steam in sugar mills, by a 2025 estimate.
- Salai wood: widely used for newsprint, as at Nepanagar.
- Others: waste paper, rags, rice and wheat straw, jute sticks, and soft wood from eucalyptus, pine, wattle and mulberry.
- Recycled fibre:
- About 70–75% of paper and board used in India is of recycled grade, which needs about 20 million tonnes of waste paper a year.
- India’s waste paper recovery is only 43%, against 55–60% worldwide.
- Gujarat and Uttar Pradesh hold about 22% and 18% of national recycling.
- Chemicals and inputs: caustic soda, soda ash, sodium sulphate, chlorine, sulphuric acid, sulphur, lime, ferric alumina, ammonium sulphate, resin and clay, with sizing and colouring agents.
- Coal: about 3.5–4.1 tonnes for each tonne of paper.
- Soft water is needed in large quantity.
Location Factors
- Nearness to raw material: bamboo and softwood fix many mills, for example in South Gujarat, Odisha and Madhya Pradesh.
- Abundant coal: energy needs and the cost of hauling coal can outweigh a lack of raw material. Paper making started in Bengal because of coal.
- Nearness to market: some mills sit near markets with cheap labour.
- Kolkata draws raw material from the North-Eastern States, and has cheap labour, coal and water at hand.
- Water supply: mills need clean water free of chemicals and pollutants. This is one reason they are set up near forests, away from polluted rivers.
The Weight-Loss Logic
- It is a raw material-intensive, weight-losing industry. In Alfred Weber’s terms, the ratio of raw material to product is about 4:1 and the material index is above 1.
- In its early stage, the industry therefore gains by locating near raw material.
- Bamboo and coal together: about 2.5 tonnes of bamboo and 4 tonnes of coal go into a tonne of paper. Both are heavy and weight-losing, so a site should serve both.
- Chemicals are needed in small amounts and travel easily.
- Forest belts: mills tend to cluster near the forests of the Western Ghats, Eastern Ghats and central India, and in the Tarai–Bhabar at the Himalayan foothills.
- Himalayan softwoods are vast, but rugged terrain and poor transport keep them out of reach, so the Himalayan region itself has no paper mill based on them. Units at Barotiwala and Kala Amb stand only in the foothills.
- Older hopes rested on temperate wood in the Himalaya and Jammu and Kashmir, as well as on hardwood in Madhya Pradesh and West Bengal and on the west coast.
- Regeneration: softwood forests take about 50–60 years to regrow, against 1–3 years for bamboo.
- Plantations: eucalyptus and other fast-growing trees are being planted to close the gap. Eucalyptus has been discouraged in the east of the country, since it draws heavily on sub-soil water.
How the Pattern Has Shifted
- The Bengal start:
- When sabai and other grasses were the main material, they travelled long distances to Bengal from Uttar Pradesh, Punjab, Bihar and Nepal.
- The coal mines of Bengal still kept mills there, despite this unfavourable position.
- The Hugli riverine tract was preferred for two reasons: coal in large quantity and a large market nearby.
- The bamboo shift:
- Bamboo made Bengal’s position better, as supplies lay near the Hugli tract alongside coal and consumers.
- More and more plants have since moved to bamboo.
- Why bamboo beat sabai:
- Sabai is mixed with other growth, hard to clean and limited in supply.
- Bamboo grows fast and densely and regrows in a year or two.
- Paper can be made wholly from bamboo, without any wood pulp, though it lacks strength, which limits its use for some printing and writing grades.
- South India: mills in Karnataka and Keralam (Kerala) use the bamboo that grows abundantly there.
- Uttar Pradesh and Haryana: mills depended on sabai and murj grass. Lucknow and Saharanpur have excellent transport links for both raw materials and markets.
- Hardwood: a method of making paper from hardwood brought a revolution, and new mills in Madhya Pradesh were set up to use it.
- Newsprint at Nepanagar: the mill uses salai wood for pulp, along with pulp imported from Canada and Scandinavia.
- Dispersal: raw materials and chemicals are available in most parts of the country, so mills are widely dispersed.
Distribution
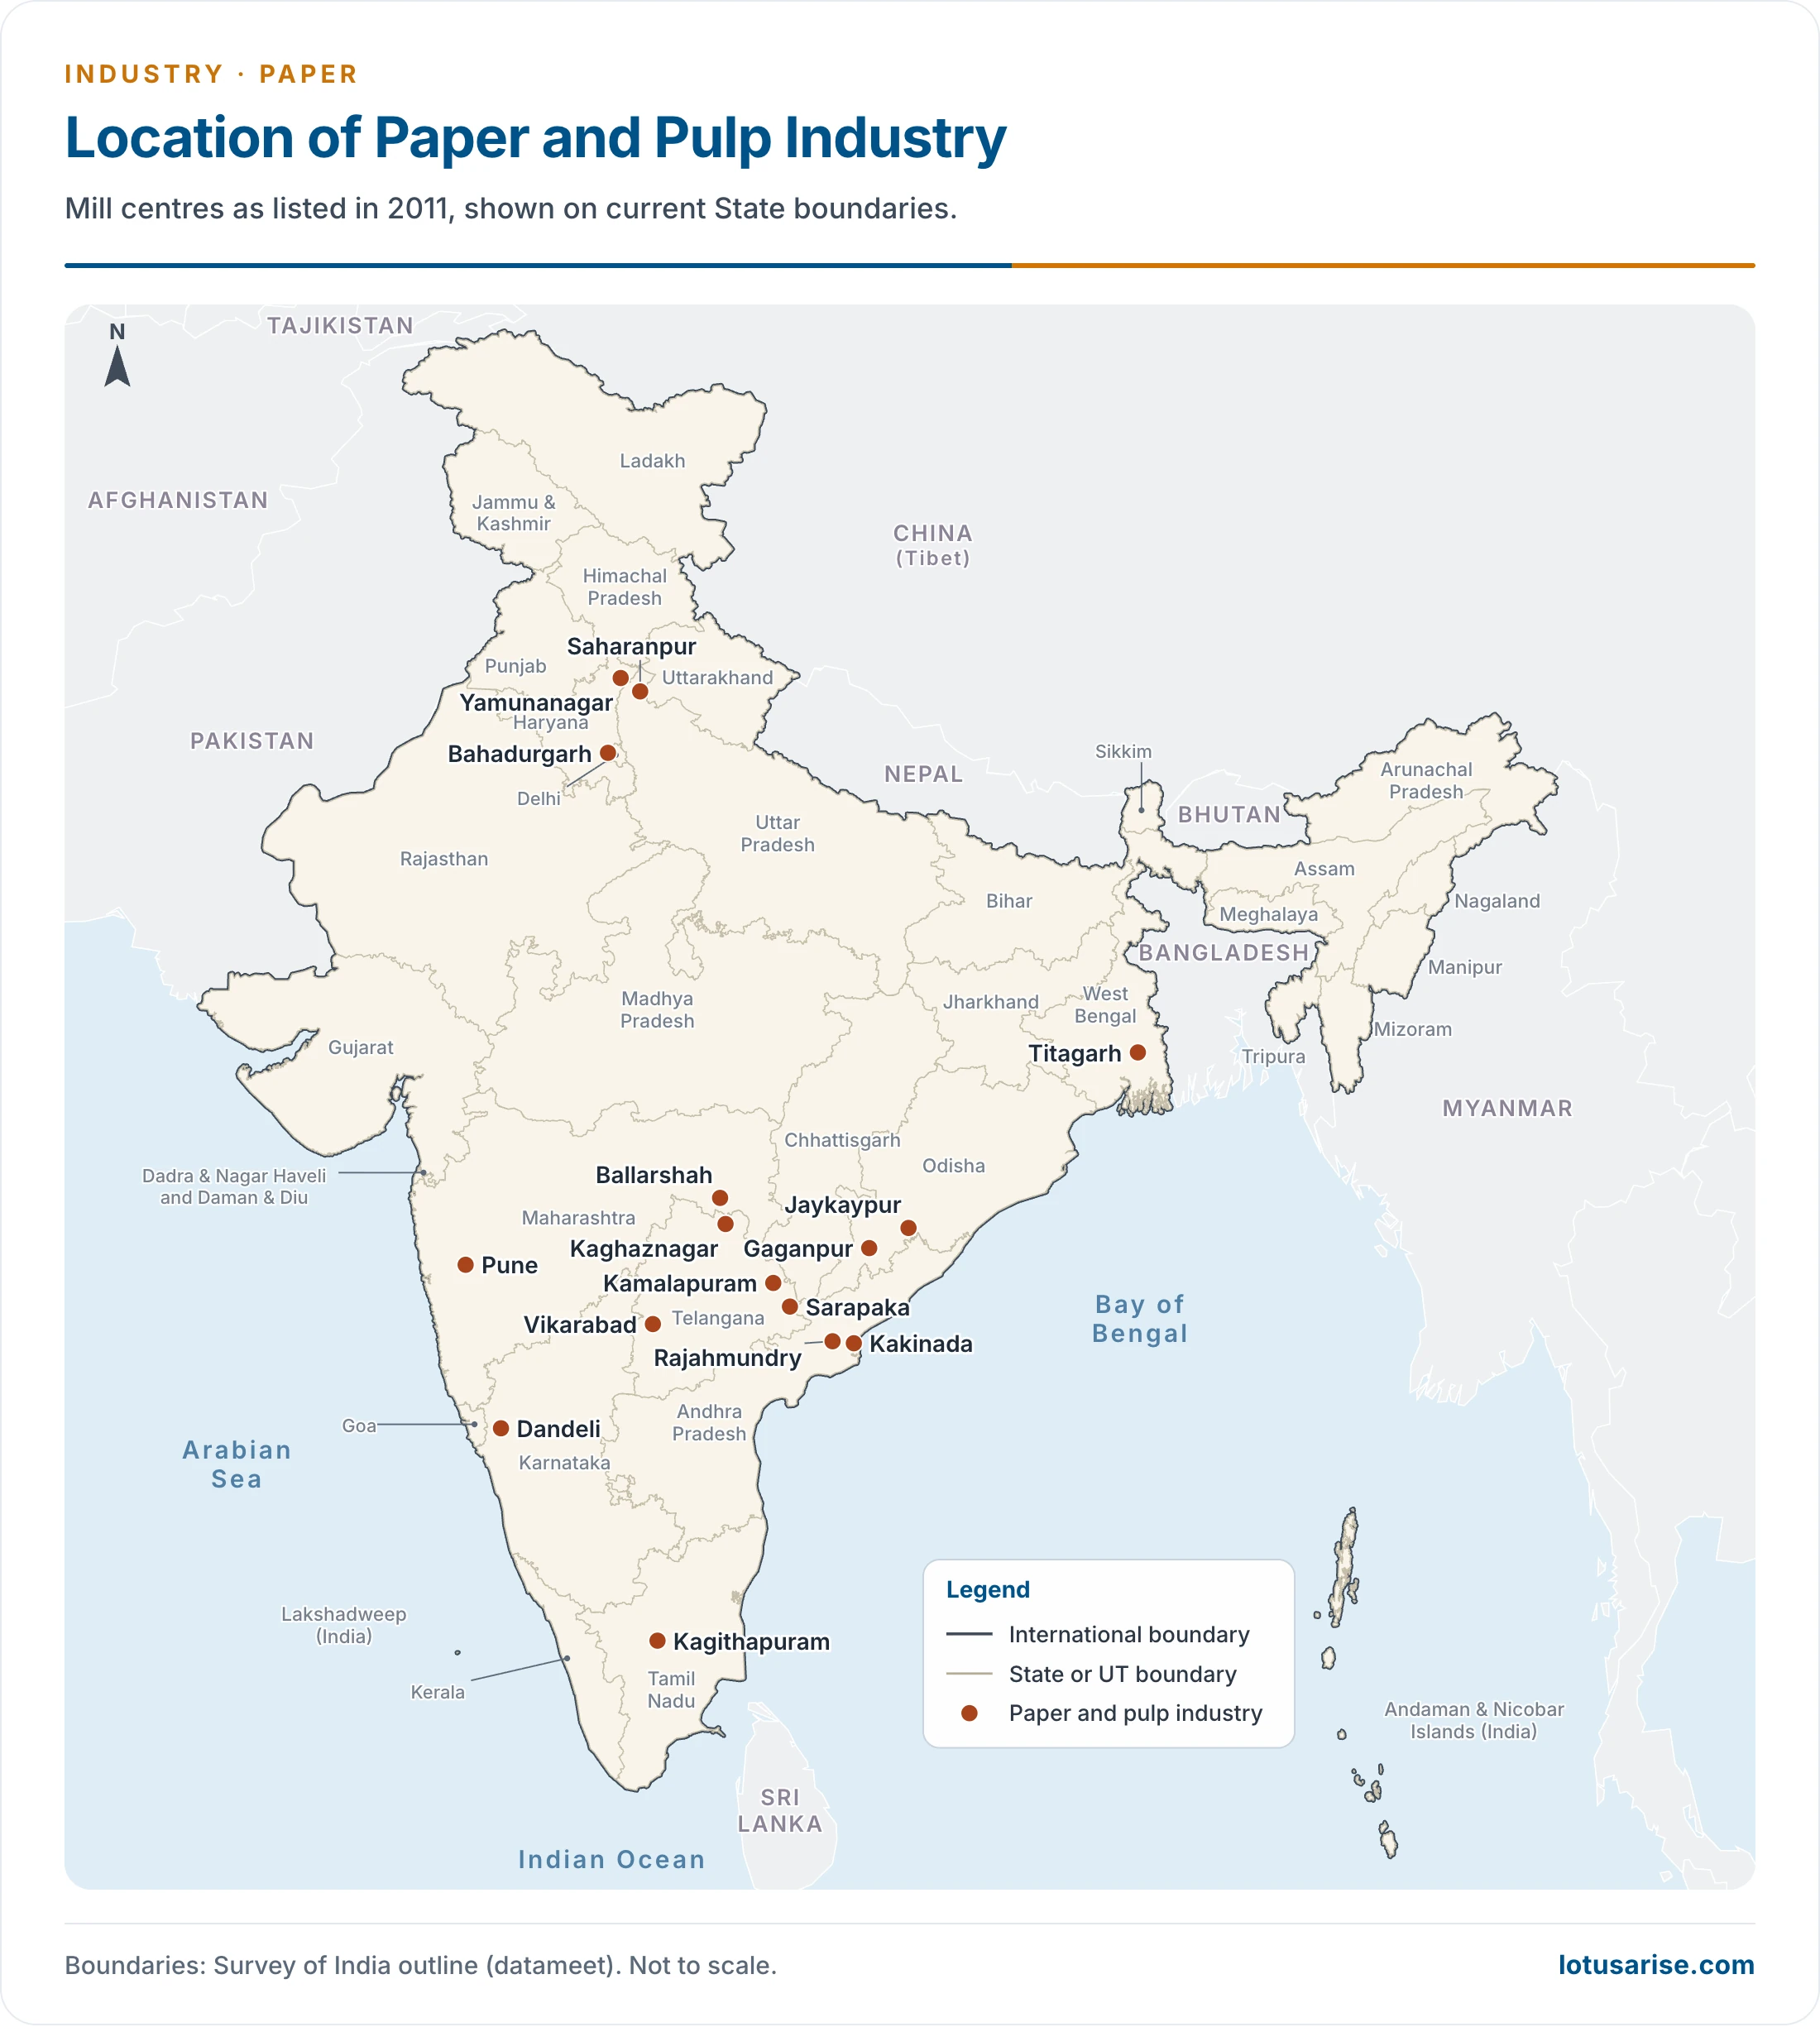
- Older shares: West Bengal, Odisha, Madhya Pradesh, Andhra Pradesh, Maharashtra and Karnataka once held nearly 65% of capacity. Tamil Nadu, Keralam, Assam, Haryana, Bihar and Gujarat came next.
- A later ranking gave Maharashtra, Andhra Pradesh, Gujarat, Uttar Pradesh and West Bengal over half of output.
- Current specialisation (2025 estimate):
- Packaging grades: Gujarat and Tamil Nadu
- Specialty papers: Andhra Pradesh and Odisha, the former with clonal plantation programmes
- Printing paper: Uttarakhand, around Kashipur
- Newsprint and commercial printing: Maharashtra and West Bengal
- Wood fibre and agro-forestry: Tamil Nadu
- Bagasse and recycling: Uttar Pradesh
Major States
- West Bengal:
- The pioneer, contributing substantially since the 19th century. It led until the mid-1980s, then slid to fifth place with 22 mills and about 7% of capacity.
- Location: along the Hugli, on bamboo from Assam, Odisha and Jharkhand and on sabai from Chhattisgarh and Madhya Pradesh, with coal from Jharia and Raniganj.
- Some mills use waste paper and agro-residues, and others sabai and eucalyptus.
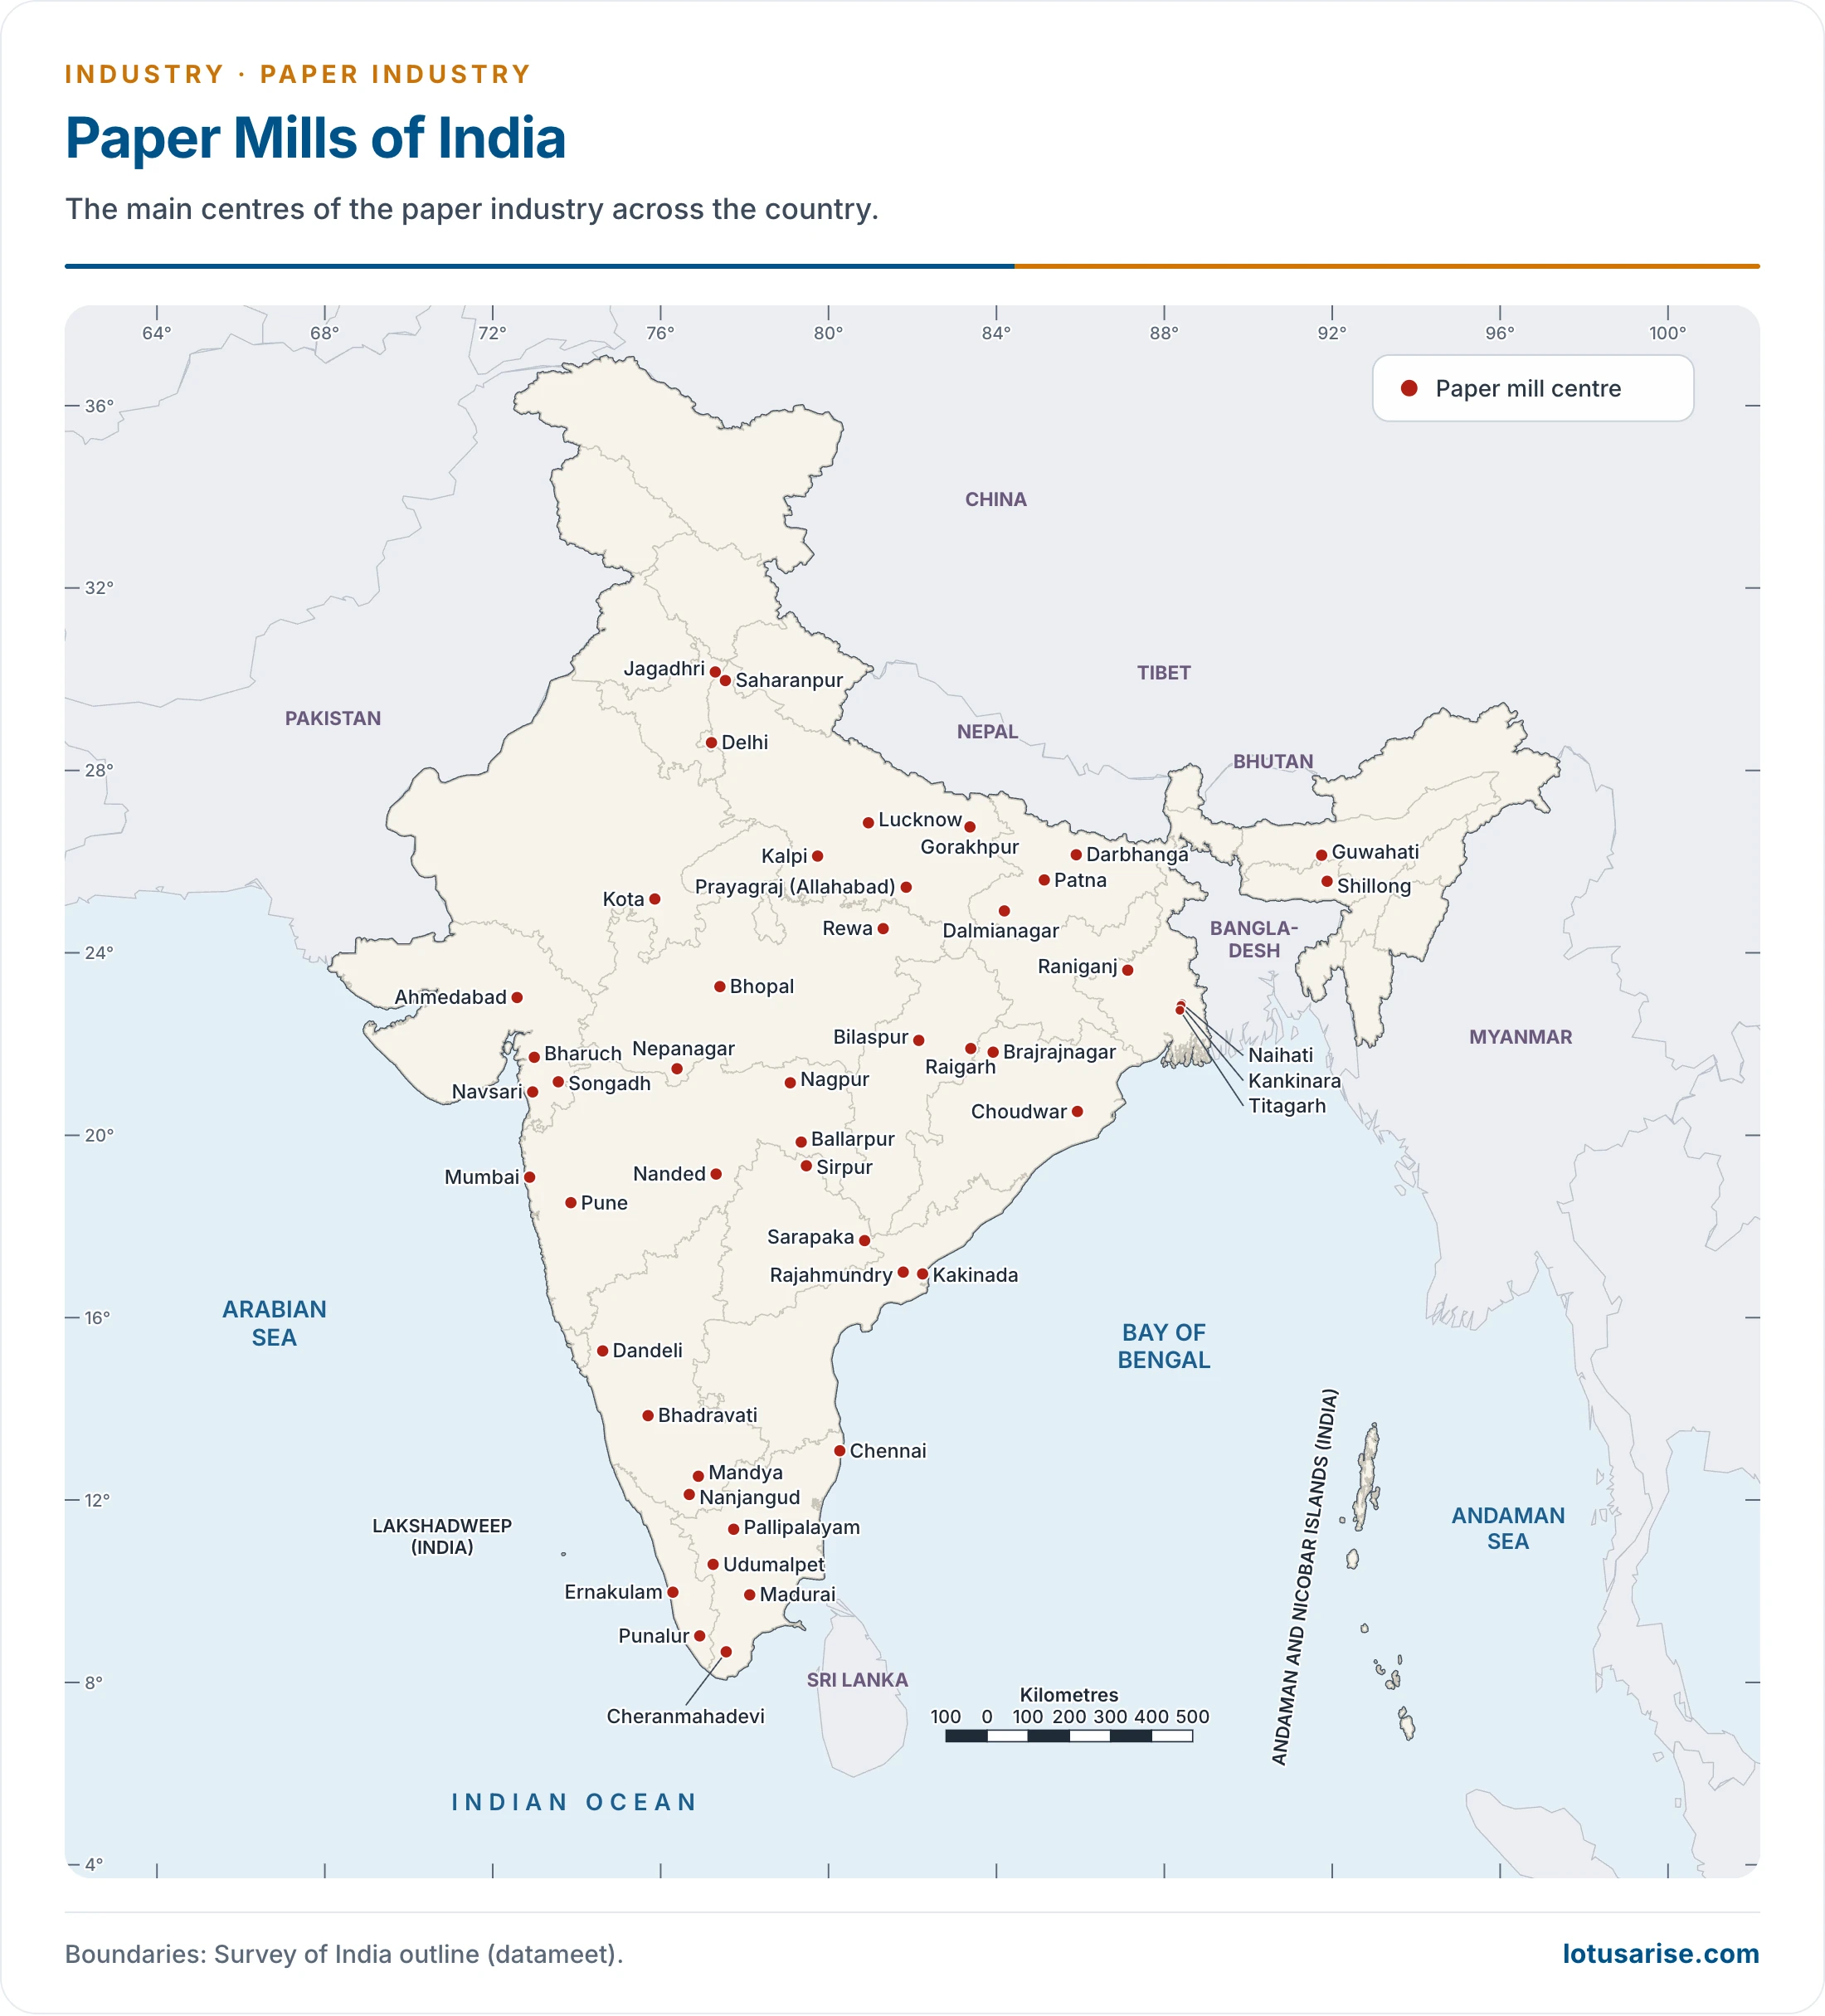
- Centres: Kolkata, Tribeni, Titagarh, Alambazar, Kankinara, Bansberia, Baranagar, Raniganj, Sheoraphuli, Chandrabati and Naihati.
- Maharashtra:
- It rose from fourth in the mid-1980s to first by 1996, with 63 mills, 16.52% of capacity and 18% of output in older counts.
- At least 15 mills were noted earlier, most of them old and worn out.
- Short of raw material and coal, it uses rags, waste paper and pulp from Sweden and Canada, with hydroelectricity in place of coal.
- Ballarpur has the largest mill.
- Centres: Kalyan, Khopoli, Pune, Nagpur, Bhiwandi, Mumbai, Kamptee, Sangli, Pimpri, Nandurbar, Vikhroli and Chinchwad.
- Andhra Pradesh and Telangana:
- Abundant bamboo and State incentives drew new units with modern machines. It overtook West Bengal in the early 1990s, with 19 mills, 11.3% of capacity and 13% of output in older counts.
- Andhra Pradesh: Rajahmundry, Tirupati, Kurnool, Srikakulam, Nellore, Kakinada, Bhadrachalam.
- Telangana: Sirpur (Kagaznagar), Sarapaka, Khammam, Bodhan.
- Madhya Pradesh:
- Bamboo, sabai and eucalyptus give a solid base. It had 18 mills and 6.62% of capacity in older counts.
- Centres: Nepanagar, Vidisha, Rewa, Ratlam, Shahdol (Amlai), Bhopal, Rajgarh and Indore.
- Odisha:
- Vast forests and cheap hydel power suit the industry, and mills use Eastern Ghats bamboo, about five lakh tonnes a year.
- Three mills were noted at Brajrajnagar, Rayagada and Choudwar. A later count gave 8 large mills and over 6% of capacity, with the State’s position slipping as bamboo declined.
- Uttar Pradesh:
- The largest number of mills, 68, but small, with capacity of no more than 9%.
- Saharanpur and Lalkuan have large mills.
- Other centres: Meerut, Modinagar, Ghaziabad, Lucknow, Gorakhpur, Pipraich, Muzaffarnagar, Prayagraj (Naini), Varanasi, Kalpi, Budaun and Mainpuri.
| State | Older position | Raw material | Centres |
|---|---|---|---|
| Gujarat | 55 mills; share rose from 3% to 10% (mid-1980s to mid-1990s) | Bagasse, eucalyptus | Rajkot, Vadodara, Surat, Bilimora, Navsari, Songadh, Ahmedabad, Vapi, Bharuch |
| Tamil Nadu | 24 small mills; 5.74% of capacity | Local bamboo | Cheranmahadevi, Pallipalayam, Udumalpet, Chennai, Salem, Amaravathinagar, Papanasam, Madurai |
| Karnataka | 17 mills; 5.48% of capacity | Local bamboo, bagasse | Bhadravati, Belagola, Dandeli, Ramanagara, Bengaluru, Krishnarajasagar, Nanjangud, Munirabad, Harihar, Mandya |
| Punjab | 23 small mills; a little over 5% | Hoshiarpur, Sangrur, Saila Khurd, Rajpura | |
| Assam | Large bamboo areas; greatest potential by older estimates | Bamboo | Nagaon, Guwahati, Cachar, Lumding |
| Haryana | 18 mills | Imported pulp, eucalyptus | Yamunanagar, Faridabad, Dharuhera, Jagadhri |
| Bihar | 6 mills | Dalmianagar, Patna, Darbhanga, Samastipur, Barauni | |
| Others | Himachal Pradesh (Barotiwala, Kala Amb), Keralam (Punalur, Ernakulam, Mavoor, Kozhikode), Rajasthan (Kota), Meghalaya (Shillong), Nagaland (Mokokchung) |
- Assam today: the Hindustan Paper Corporation mills at Cachar and Nagaon have produced nothing since 2015 and 2016 respectively, despite the State’s bamboo.
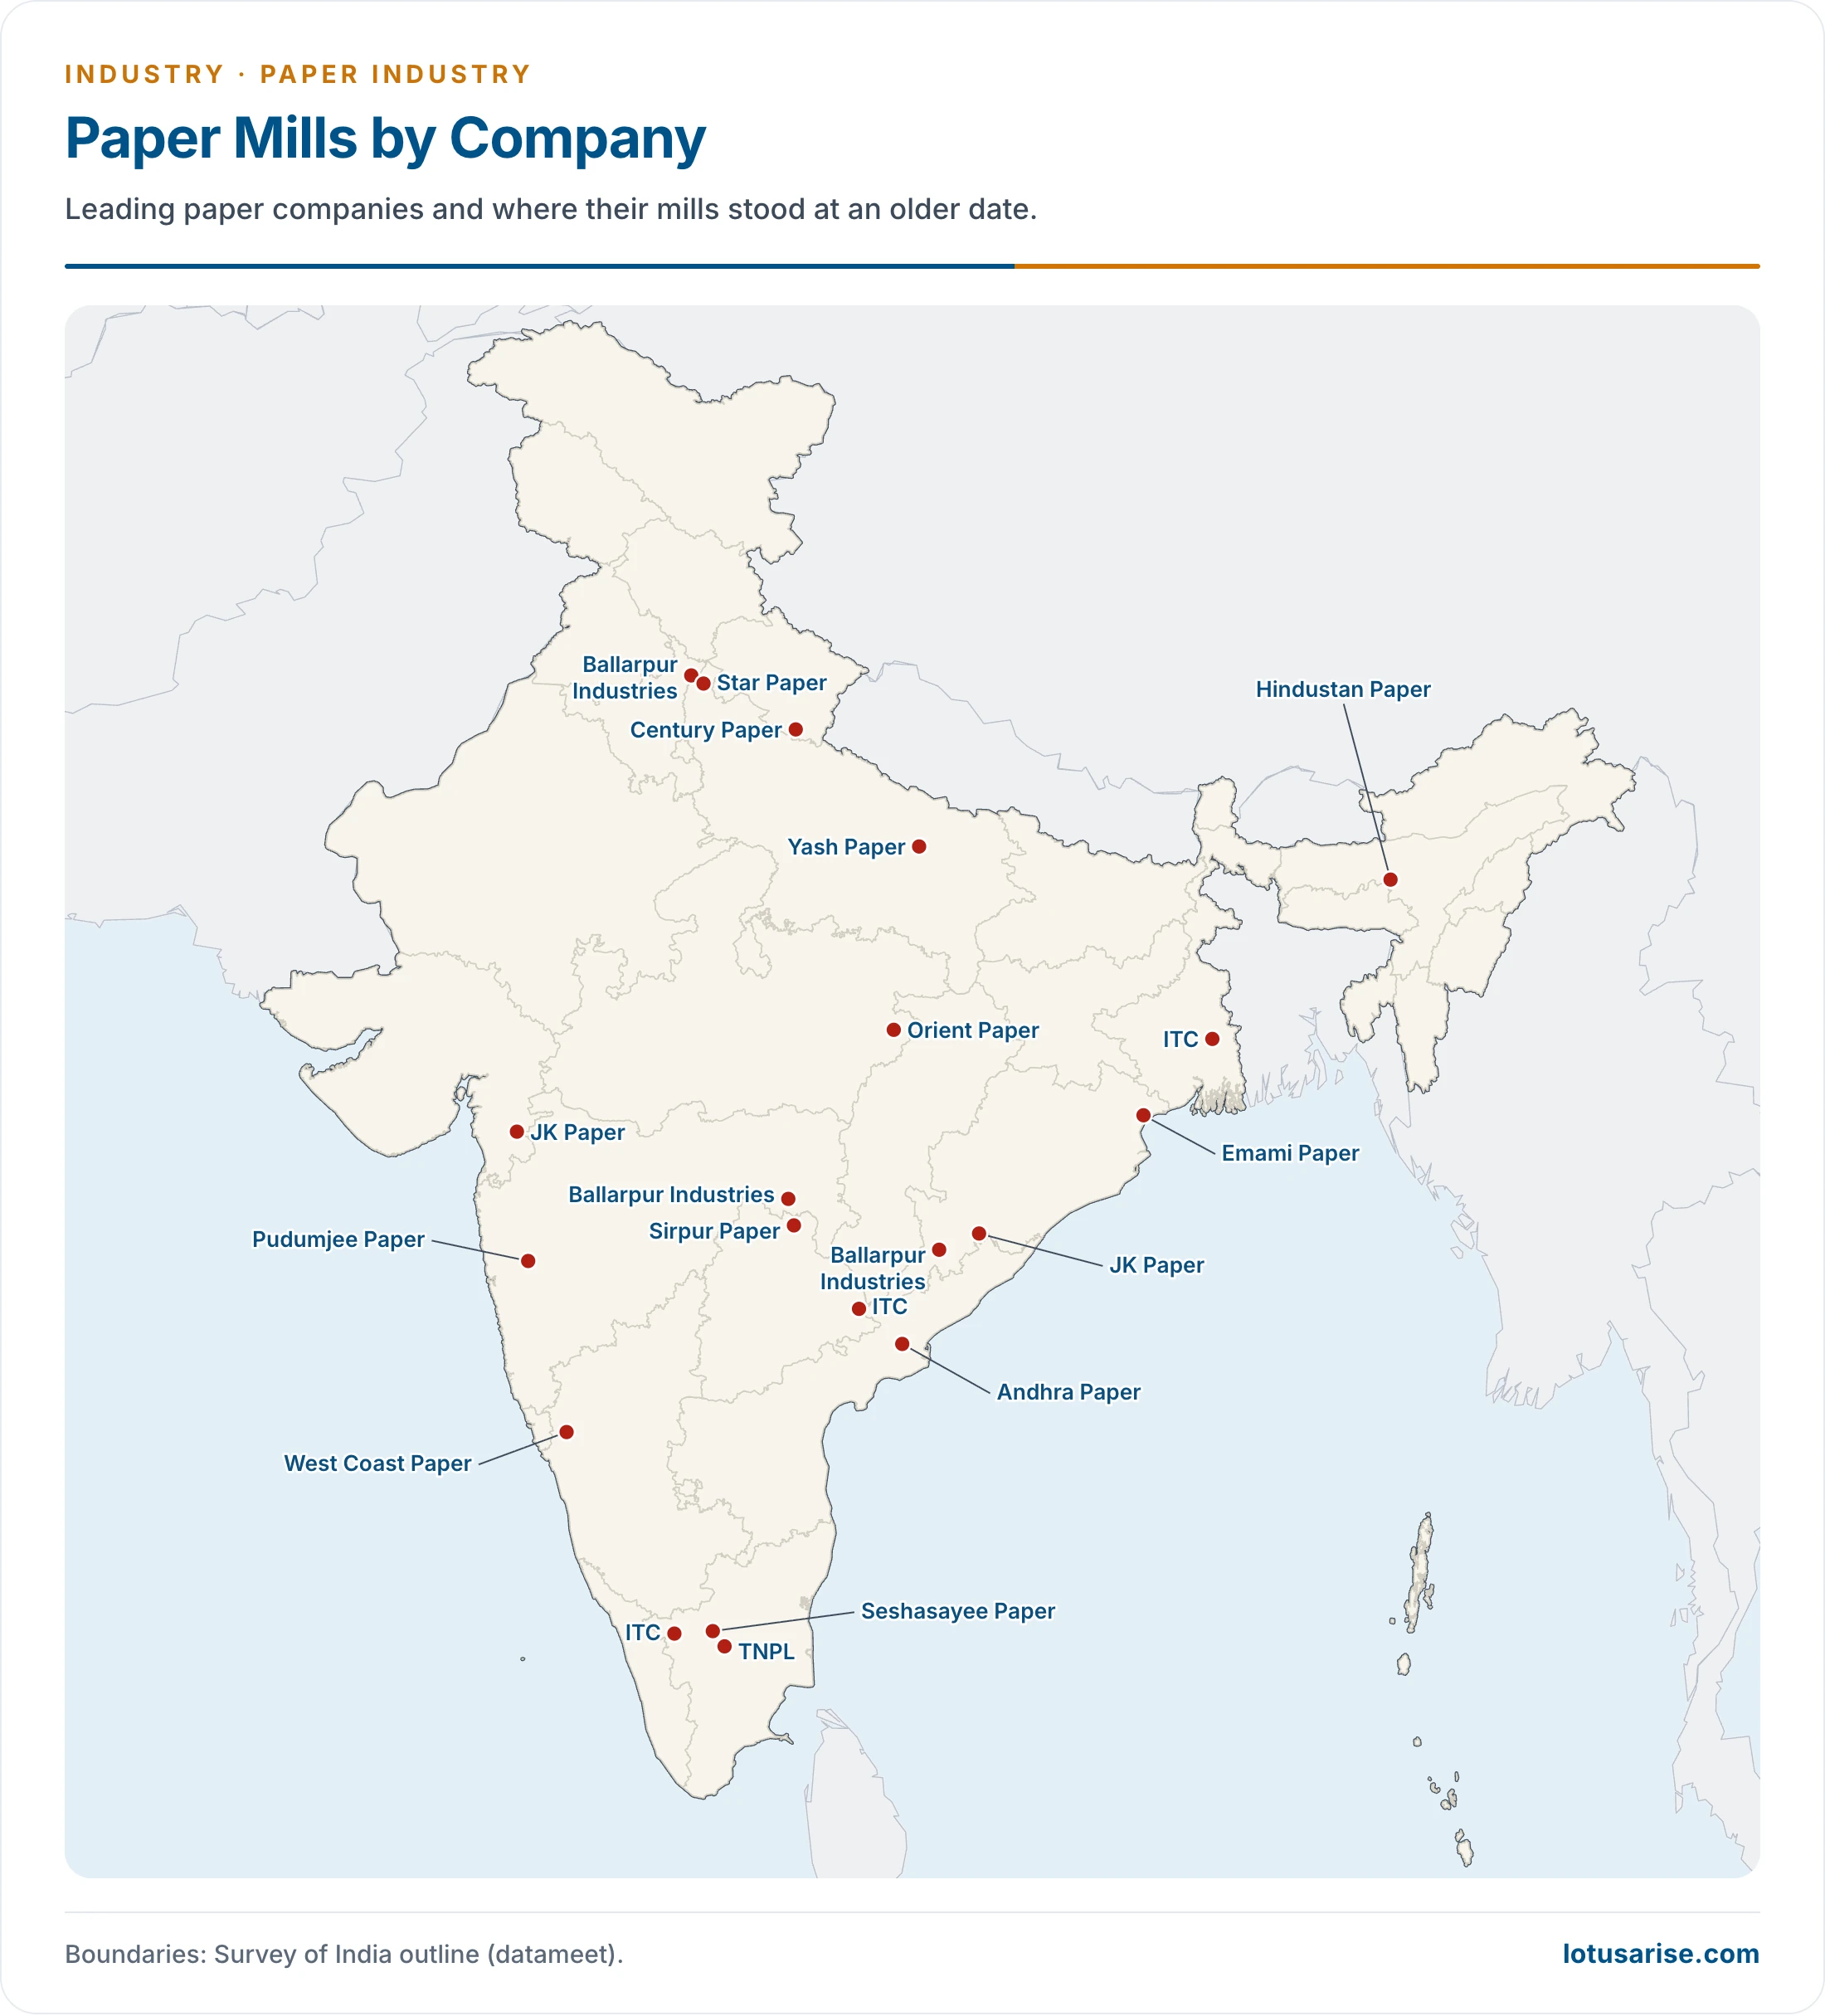
- This map shows mills by company name at an older date. The Hindustan Paper mills in Assam have since stood idle.
Newsprint
- National Newsprint and Paper Mills (NEPA) at Nepanagar, Burhanpur district, Madhya Pradesh, began commercial production in 1956, and remained the sole producer until 1980.
- Its capacity rose from 30 thousand to 75 thousand tonnes.
- It stopped in 2016 and was revived about six years later.
- Later entrants:
- Mysore Paper Mills, Bhadravati (1981): 75,000 tonnes. Production has long stopped, and Karnataka has been weighing a private lease.
- Hindustan Newsprint, Velloor near Kottayam (1982): 80,000 tonnes.
- Tamil Nadu Newsprint and Papers, Pugalur (1985): 50,000 tonnes.
- Newsprint Control Order, 2004: listed mills are exempt from excise duty, subject to actual-user conditions. An older count gave 117 registered mills, of which 73 were producing, with capacity of 1.3 million tonnes.
- Consumption (older): only 600 grams per head, against 1.9 kg in Asia outside Japan and China and 6 kg worldwide.
Problems and Prospects
Problems of the Industry
- Shortage of raw material:
- Sabai and bamboo supply is often interrupted, and industry long had no plantations of its own.
- Dwindling forests cause serious shortages.
- Unconventional materials such as eucalyptus, wheat bran and rice straw need new processes and new equipment.
- High cost of production:
- Capital equipment is costly at international prices.
- Power and coal costs rose steeply, royalties on bamboo and hardwood rose by 70% in the same decade, and bulky raw material brings heavy transport costs.
- Royalties and lease:
- Many governments raised royalties on leased forest land to meet current spending, some by 5–6 times in 5–6 years.
- Policy on royalties and leases needs to be stable and long-term.
- Over-capacity and under-use:
- 180 mills came up between 1974 and 1984 under active encouragement, creating excess capacity.
- Even with utilisation of 72%, 7 large and 13 small units lay idle for years.
- Sickness in small units:
- Investment costs are high and returns low, with a heavy burden from finance and markets.
- Shortage of coal and raw materials, and rising electricity and water charges, add to this. They could not compete with large units.
- Effluents:
- Suitable treatment is beyond small units, which forced many to close.
- Lack of research:
- New processes, pulp grades and equipment are needed.
- Unconventional materials need advanced technology, which a developing country may find hard to afford.
- Eco-conservation:
- Growing concern for forests and biodiversity cuts raw material supply further.
- Environmentalists object to effluents released into drains, rivulets and rivers.
- Rising demand:
- India, with about 16–17.5% of world population, used about 1–2.5% of world paper in older figures.
- Spread of education and literacy will keep demand rising, and older accounts expected it to double within ten years.
- Small mills:
- Average size was under 10,000 tonnes. Comparable figures were 50,000 tonnes for South-East Asia and 85,000 tonnes for the Asia-Pacific.
- Small size blocks new technology and raises costs, and many mini plants run on worn-out machinery.
- Costly imports: dearer imported pulp and waste paper, set against poor selling prices, have closed many mills.
- Recycling:
- Only 15% of output rested on recycled material in older figures, against 30–35% worldwide. This has changed sharply, though collection remains fragmented.
- Competitiveness: a study for the industry department pointed to poor cellulosic raw material, obsolete technology, costly basic inputs and environmental issues.
Future Prospects and Suggestions
- Raw material strategies:
- A shift from bamboo to eucalyptus, wattle and mulberry.
- Recycling fibre, making production more environment-friendly and saving energy.
- Social and farm forestry: more thrust here has begun to ease supply.
- Plantations: bamboo cultivation has turned uneconomic, so reliance has moved to unconventional materials. Mills need plantation forestry around them.
- Technology: modernisation is a must, but it needs heavy capital, which private firms do not always find easy to raise.
- Bagasse:
- Judicious use should be encouraged, since much is burnt as fuel in sugar mills.
- Sugar mills could move to coal-fired boilers in place of bagasse-fired ones, and India’s large cane crop gives this great potential.
- Rural labour: the large pool of rural workers can be used to raise raw materials.
- Outlook: a growth rate of 6–7% a year is projected over the next five years, with revenue of about Rs 1,00,000 crore by 2027-28.
- India needs to add about 1 million tonnes a year of integrated capacity to keep pace.
Advantages of the Indian Paper Industry
- Growth cycle: tropical plantations are ready in 6–7 years, whereas western conifers take about 50 years.
- Wages: labour is cheap compared with the West.
- Skills: the workforce is well trained at all levels, so good-quality paper can be made with suitable technology at relatively low manpower cost.
Previous Year Questions
- No direct PYQ has been asked on this sub-topic yet.





Superbly amazing analysis of paper industry in India 🙏
Keep reading & Happy Learning.
geography will become easy subject when you visit lotus arise