

- Marine resources are all the living and non-living materials, and the energy, that people can draw from sea water, the sea floor and the rocks beneath it. They range from fish and seaweed to salt, sand, oil, metal-rich nodules, tides and waves.
- The ocean covers about 71% of the Earth’s surface and holds most of its living space, yet it supplies a far smaller share of human needs than the land. Most of the ocean is a biological desert, and its richest minerals lie under thousands of metres of water.
- It also regulates climate, takes up carbon and releases oxygen, and its resources give jobs, goods and services to billions of people.
- Marine resources differ from land resources in three ways:
- Common property: beyond national limits they belong to no one, so they are easily overused.
- Mobility: fish, larvae and pollutants cross every boundary drawn on a chart.
- Frontier character: fisheries are already pressed to their limits, while deep-sea minerals and most marine energy are barely tapped.
- Their use is governed by the maritime zones of UNCLOS: coastal states hold sovereign rights over resources within the Exclusive Economic Zone (EEZ) and the legal continental shelf; the deep sea-bed beyond them is the “Area”, the common heritage of mankind.
Classification and Productivity
Bases of classification
| Basis | Classes | Examples |
|---|---|---|
| Nature | Biotic (living); abiotic (non-living) | Fish, seaweed; salt, nodules, oil |
| Renewability | Renewable; non-renewable | Fish, tides, waves; oil, placers, nodules |
| Use | Food; minerals; energy; water; services | Fisheries; manganese; OTEC; desalinated water; shipping, tourism |
| Location | Shelf; slope; deep-sea floor; water column | Placers and oil; gas hydrates; nodules; dissolved salts |
- Ocean services are a resource class of their own: shipping carries over 80% of world trade by volume, and the ocean absorbs about a quarter of human carbon dioxide emissions and over 90% of excess heat.
Where marine life is concentrated
- Marine life zones are set by light and depth:
- The pelagic realm (open water) is divided into the sunlit photic (euphotic) zone, down to about 200 m, and the dark aphotic zone below it (mesopelagic, bathypelagic, abyssopelagic).
- The benthic realm (sea floor) runs from the littoral (between tide marks) and sub-littoral (the shelf floor) to the deep-sea floor.
- Over the shelf the water is the neritic zone; beyond it is the oceanic zone.
- Primary production happens only in the photic zone, through phytoplankton, the “marine pasture”.
- Its supply of nitrates and phosphates is the limiting factor. Nutrients sink with dead matter, so the surface stays rich only where water is mixed or upwelled.
- Productivity varies sharply. Net primary productivity (Robert Whittaker and Gene Likens, 1975) is about:
- 125 g/m²/yr in the open ocean;
- about 360 g/m²/yr over the continental shelf;
- about 500 g/m²/yr in upwelling zones;
- 1,500–2,500 g/m²/yr in estuaries, algal beds and reefs, which rival tropical forests.
- John Ryther (1969) showed what this means for fish: the open ocean (about 90% of the area) yields almost nothing, while coastal waters and upwelling zones covering only about 0.1% of the ocean each yield about half of the world’s fish.
Biotic Resources
Plankton, nekton and benthos
| Community | Way of life | Members | Resource value |
|---|---|---|---|
| Plankton | Drift with currents | Phytoplankton (diatoms, dinoflagellates, algae); zooplankton (copepods, krill, larvae) | Base of every food web; krill fishery; harmful algal blooms (red tides) |
| Nekton | Swim independently | Fish, squid, turtles, whales, dolphins, seals | Bulk of the fish catch; marine mammals |
| Benthos | Live on or in the floor | Seaweeds, seagrass, oysters, mussels, crabs, sponges, corals | Shellfish, seaweed, pearls, drugs, reef fisheries |
- Benthos may be epifauna (on the floor) or infauna (buried in sediment), and fixed or mobile. Deep benthos lives on food sinking from above.
- Phytoplankton are autotrophs: floating micro-plants such as algae and diatoms that make their own food. Zooplankton are the floating micro-animals that graze on them.
- Biotic resources span fish, crustaceans, molluscs, corals, reptiles such as sea turtles, and mammals. Benthic communities run from tidal pools on the foreshore across the shelf to the abyssal depths.
- Coral reefs are the “rainforests of the sea”. They nurse reef fisheries, protect coasts and draw tourists.
Fisheries
Kinds of fish and fisheries
- Pelagic fish live in the upper water, often in huge single-species shoals: herring, sardine, anchovy, mackerel, tuna.
- Demersal fish live on or near the bottom of the shelf, mostly within 200 m: cod, haddock, hake, halibut, flounder, pollock.
- Anadromous fish grow at sea and spawn in rivers: salmon, hilsa.
- By family, the herring-like clupeoids (herring, sardine, anchovy) form the largest share of the world catch, followed by the cod-like gadoids.
- Fin fish make up about nine-tenths of the catch; the rest is crustaceans (shrimp, lobster, crab), molluscs (squid, oysters) and other invertebrates.
Major fishing grounds of the world
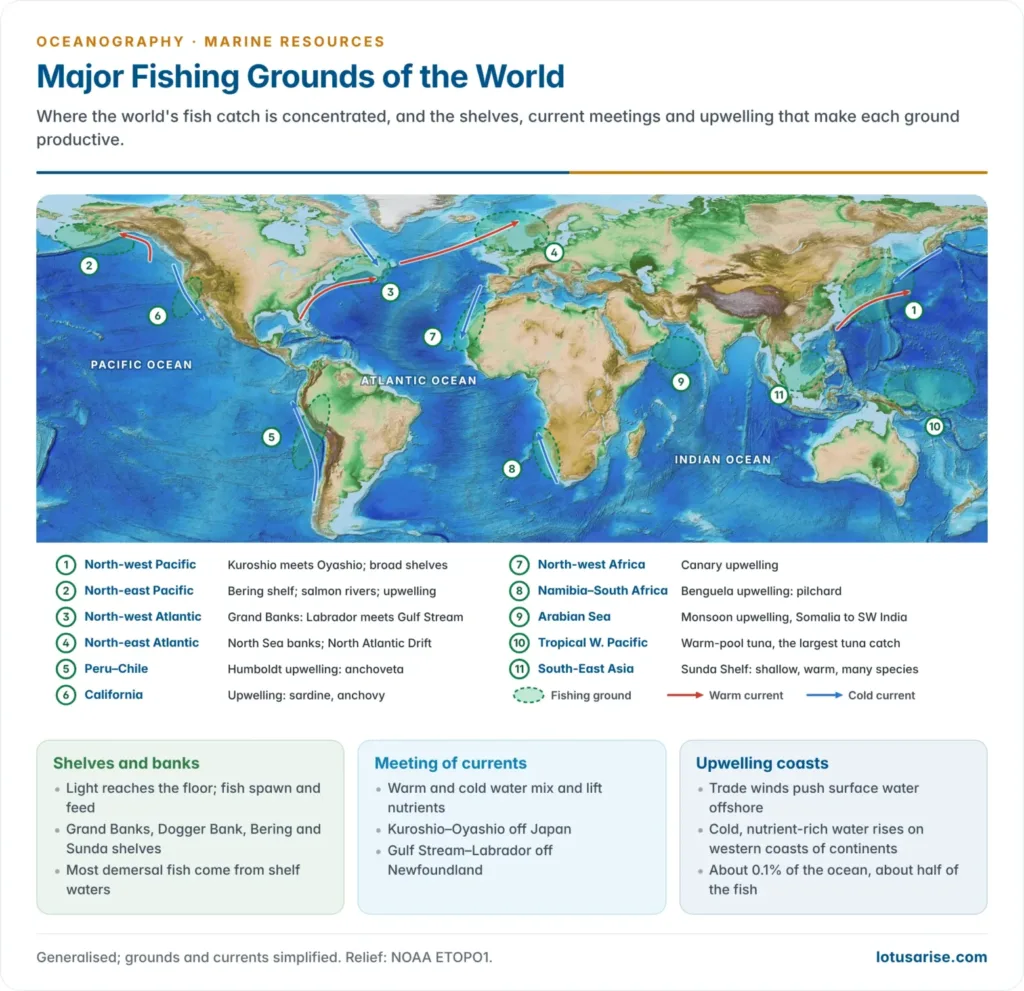
| Fishing ground | Location | Why it is productive | Main catch |
|---|---|---|---|
| North-west Pacific | Japan, Korea, China, Russian Far East | Kuroshio and Oyashio meet; broad Yellow and East China Sea shelves; indented coasts | Pollock, sardine, mackerel, squid, salmon |
| North-east Atlantic | North Sea, Norway, Iceland | Wide shelf and banks (Dogger Bank); North Atlantic Drift keeps ports ice-free | Herring, cod, mackerel, haddock |
| North-west Atlantic | Grand Banks, Georges Bank | Shallow banks where the cold Labrador Current meets the warm Gulf Stream | Cod, haddock, herring, scallops |
| North-east Pacific | Bering Sea to British Columbia | Broad Bering shelf; upwelling; salmon rivers | Pollock, salmon, halibut, crab |
| Upwelling coasts | Peru–Chile, Benguela, Canary, California | Trade winds drive surface water offshore; cold, nutrient-rich water wells up | Anchoveta, pilchard, sardine |
- The North-west Pacific is the most productive fishing area in the world, and China is by far the largest producer.
- Peru’s anchoveta fishery is usually the largest single-species fishery on Earth, but it swings with El Niño: warm water caps the upwelling, plankton fails and the catch crashes, as in 1972–73 and 1982–83.
Why some seas are rich: the controls
- Physical controls:
- Broad, shallow continental shelves and banks, where light reaches the bottom and fish spawn.
- Mixing of warm and cold currents, which overturns the water and lifts nutrients.
- Upwelling along the western coasts of continents, driven by offshore Ekman transport.
- Cool temperate water, which holds more dissolved oxygen and carbon dioxide and supports dense plankton.
- Human controls:
- Indented coasts with sheltered harbours, and forested hinterlands that once supplied boat timber.
- Scarce farmland that pushes people to the sea, as in Norway and Japan.
- Large markets, capital, cold storage and canning, and modern fleets with sonar and satellite fish-finding.
Why tropical fisheries lag
- Warm, stratified water: a strong thermocline traps nutrients below the photic zone, so plankton stays thin except where upwelling breaks it.
- Many species, few shoals: tropical seas hold great diversity but few dense single-species shoals, which makes bulk catching and processing harder.
- Narrow shelves and reef or mangrove coasts in many places hinder trawling.
- Fish spoil quickly in heat, and cold chains, harbours and processing capacity are limited.
- Small-scale, labour-intensive fleets with little capital, and weak local demand for some species.
- Exceptions: monsoon upwelling in the Arabian Sea (Somali and Oman coasts, India’s south-west coast) and the western and central Pacific tuna grounds, which now produce the largest tuna catch in the world.
World fish production today
- In the most recent global assessment (June 2026, for 2024), world fisheries and aquaculture reached a record 235 million tonnes, including algae.
- Aquatic animals: 195 million tonnes, of which aquaculture supplied 103 million tonnes (53%). This is the first time farming has passed 100 million tonnes.
- Capture fisheries: about 92 million tonnes, of which about 80 million tonnes was marine. The marine catch has hovered near this level since the late 1980s.
- The round figure of about 200 billion pounds a year, long quoted for the catch of fish and shellfish, is the same order: roughly 91 million tonnes.
- Food supply: about 21 kg of aquatic food per person a year.
- Food value: fish give protein and vitamins A, B and D. Inedible fish feed livestock, and scales and fishery waste serve as organic manure.
- Stock health is slipping: in 2023 only about 62% of marine fish stocks were fished within biologically sustainable levels, down from about 64.5% in 2021.
- Grand Banks cod is the warning case. Decades of overfishing led Canada to close the fishery in 1992, and the stock has still not fully recovered.
Aquaculture and mariculture
- Aquaculture is the farming of aquatic organisms with control over their breeding, feeding and protection. Mariculture is aquaculture in sea or brackish water.
- Molluscs (oysters, mussels, scallops) are the easiest to farm. They feed on natural plankton and are grown on ropes, racks or sea-bed plots. Japan’s suspended-rope oyster culture is the model.
- Shrimp are farmed in coastal ponds in India, Thailand, Vietnam and Ecuador.
- Cage fish such as Atlantic salmon (Norway, Chile) and sea bass need large inputs of feed.
- Brackish-water polyculture of milkfish and mullet is centuries old in Indonesia and the Philippines.
- India: coastal aquaculture divides into sea farming in open bays and brackish-water farming on land, using salt water from creeks and estuaries.
- Impounded wetlands called bheries in West Bengal and salt-tolerant paddy fields called pokkali in Keralam (Kerala) are old brackish systems.
- Shrimp farming has grown in Andhra Pradesh, above all Nellore district, and in Odisha and Tamil Nadu, helped by hatcheries and the Marine Products Export Development Authority.
- Mariculture began with milkfish trials at the Mandapam centre of the Central Marine Fisheries Research Institute in 1958-59, and later took in oysters, mussels and clams.
- Integrated multi-trophic aquaculture recycles the waste of fed fish or shrimp through seaweed and shellfish, to balance the system.
- Problems: shrimp ponds have cleared mangroves; farms release wastes, antibiotics and disease; escaped fish dilute wild stocks; and carnivorous fish are fed on wild-caught fishmeal.
Ocean ranching and aqua-cowboys
- Ocean ranching (sea ranching, ocean husbandry) controls marine animals at only some stages of their life and leaves the rest to the open sea, as a rancher leaves cattle on open range.
- Fisheries sense (now dominant): juveniles bred in hatcheries are marked and released, grow on natural food and are caught when they return.
- Pacific salmon suit this best, because they home to their natal stream. Hatcheries in Japan, the USA (Alaska), Russia, Canada and Korea release about 5 billion juveniles a year into the North Pacific.
- China and Japan add artificial reefs and seagrass beds to create “marine ranches”.
- India’s Central Marine Fisheries Research Institute is releasing hatchery-raised green tiger shrimp in Palk Bay and the Gulf of Mannar to rebuild depleted stocks.
- Older, wider sense: the taming and training of sea mammals (porpoises, dolphins, small whales) to work in the sea.
- Fisheries sense (now dominant): juveniles bred in hatcheries are marked and released, grow on natural food and are caught when they return.
- Aqua-cowboys link the two senses.
- In the original usage they are porpoises and dolphins trained to herd fish and to help divers, carry tools to underwater stations and assist in rescue. In 1965 the US Navy dolphin Tuffy carried tools to the Sealab II habitat.
- Wild dolphins at Laguna in southern Brazil drive mullet towards cast-net fishers, a natural version of the same partnership.
- The label now also covers the people and the sound signals that release, track and round up ranched stock. In Japan, released red sea bream are conditioned to gather at an underwater sound.
- Concerns: hatchery fish compete with wild fish for food (hatchery-origin fish form a large share of North Pacific salmon biomass), weaken wild genetic stock, spread disease and return at uncertain rates.
| System | Confinement | Feeding | Example |
|---|---|---|---|
| Capture fishery | None | Natural | Trawling, purse-seining |
| Ocean ranching | Hatchery stage only | Natural during growth | Salmon ranching, shrimp stock release |
| Mariculture | Whole life | Natural (molluscs) or artificial | Oyster ropes, salmon cages |
Whales and other marine mammals
- Whales are of two groups: toothed whales (sperm whale, killer whale, dolphins, porpoises) and baleen whales (blue, fin, humpback, grey, minke), which filter krill.
- Industrial whaling with steam catchers, explosive harpoons and factory ships drove the great whales towards extinction in the 20th century.
- The International Whaling Commission (IWC), set up under the 1946 whaling convention, at first fixed catch quotas in blue whale units, a system abandoned in 1972.
- The commercial whaling moratorium took effect in 1986. Norway and Iceland whale under objection, and Japan left the IWC in 2019 to resume commercial whaling in its own waters.
- Seals, sea otters and sea cows (dugongs, manatees) were also hunted heavily. The dugong of the Gulf of Mannar and Palk Bay is now protected in India.
Seaweeds, drugs and marine biotechnology
- Seaweeds are the largest farmed marine crop by volume, grown mostly in China, Indonesia, Korea and Japan.
- They are eaten as food (nori, kombu) and yield agar, alginates and carrageenan for food, medicine and industry. They are also used as fertiliser and feed, and studied as biofuel.
- India farms the red seaweed Kappaphycus along the Tamil Nadu coast, and a multipurpose seaweed park is being developed in Ramanathapuram district.
- Seaweeds need light, so most grow in shallow water around shores and reefs, above about 15 m. They fall into brown, green and red groups, and are rich in vitamins, minerals and trace elements.
- Marine biotechnology turns sea organisms into drugs and industrial products:
- cytarabine, an anti-leukaemia drug, was modelled on compounds from a Caribbean sponge;
- ziconotide, a painkiller, comes from cone-snail venom;
- trabectedin, an anti-cancer drug, comes from a sea squirt;
- horseshoe-crab blood is used to test vaccines and injectable drugs for bacterial toxins;
- cod-liver and shark-liver oils have long been sold as vitamin sources.
- Other products are pearls, sponges, ornamental fish, shells, chitin from crustacean waste, and fishmeal and fish oil for feed.
Abiotic Resources
Minerals dissolved in sea water and fresh water
- Every natural element occurs dissolved in sea water, at an average salinity of about 35 g per kilogram. Only a few are worth extracting:
- Common salt (sodium chloride): about one-third of the world’s salt comes from sea water by solar evaporation. In India, Gujarat produces most of it, followed by Tamil Nadu and Rajasthan.
- Magnesium and bromine are extracted commercially from sea water and brines.
- Gold, zinc, uranium, thorium and lithium are present in vast total amounts but at such low concentrations that recovery is uneconomic.
- Fresh water by desalination (reverse osmosis, multi-stage flash distillation) is now a major resource in arid coastal states, above all in the Persian Gulf countries.
- In India, Chennai’s plants at Minjur and Nemmeli supply city water.
- Low-temperature thermal desalination (LTTD) plants in Lakshadweep (Kavaratti since 2005, then Agatti and Minicoy, and now eight islands) flash-evaporate warm surface water under low pressure and condense it with cold water pumped up from depth.
Mineral resources by depth zone
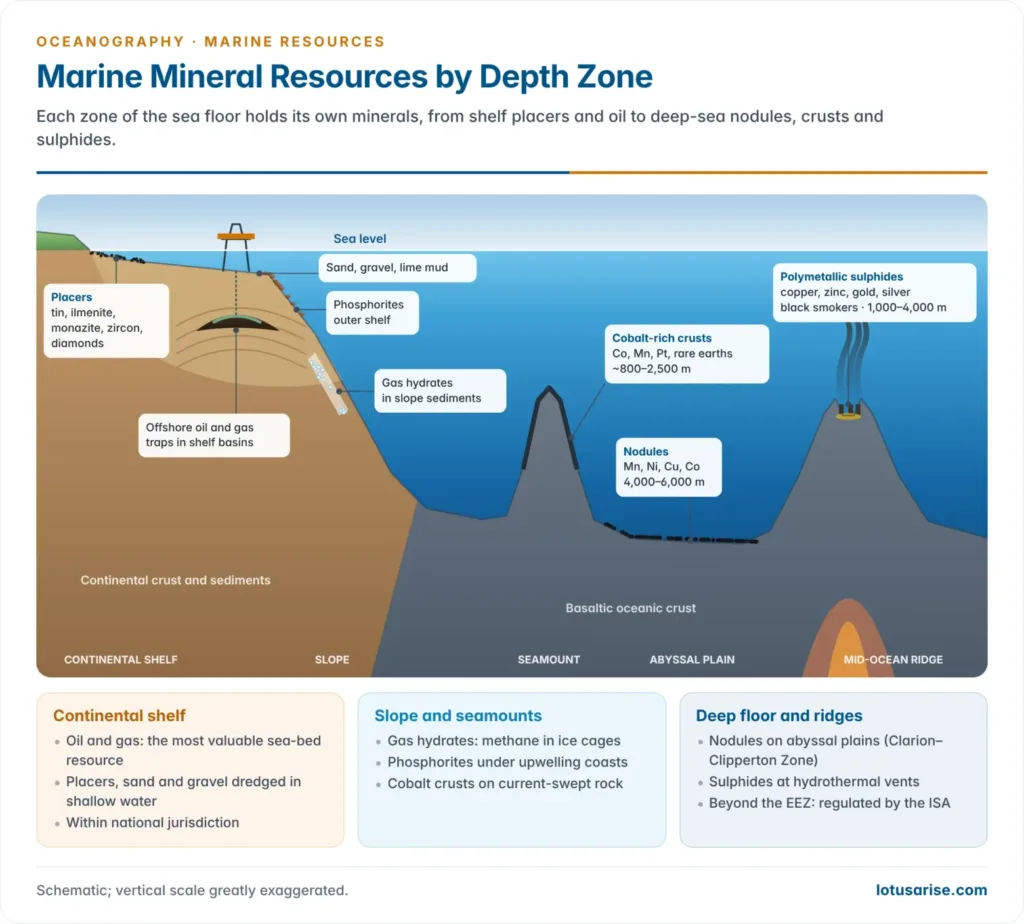
Continental shelf and slope
- Oil and natural gas are the most valuable marine minerals by far. Offshore fields supply over a quarter of world oil and gas.
- Major provinces: the Persian Gulf, North Sea, Gulf of Mexico, offshore Brazil (pre-salt), West Africa (Gulf of Guinea), the Caspian and South-East Asia.
- The Persian Gulf is shallow, sheltered from the open ocean and relatively free of hazards. Off Indonesia and Malaysia, output has been shifting from land to sea, and Western Australia developed its offshore fields from the 1970s.
- In India: Mumbai High, discovered in 1974 and producing since 1976, about 160 km off Mumbai; the Bassein gas field; and the deep-water gas of the Krishna–Godavari basin.
- Major provinces: the Persian Gulf, North Sea, Gulf of Mexico, offshore Brazil (pre-salt), West Africa (Gulf of Guinea), the Caspian and South-East Asia.
- Placers are heavy minerals concentrated by waves and currents in beach and shelf sands. They are the easiest sea-bed minerals to mine, by dredging in shallow water.
| Placer | Use | Main locations |
|---|---|---|
| Tin (cassiterite) | Solder, tinplate | Off Indonesia (Bangka–Belitung), Thailand, Malaysia |
| Diamonds | Gems | Off Namibia and South Africa |
| Ilmenite, rutile (titanium), zircon | Pigments, alloys, ceramics | Keralam (Chavara), Tamil Nadu (Manavalakurichi), Odisha (Chatrapur); Australia; Brazil; Mozambique |
| Monazite | Thorium, rare earths | Keralam and Tamil Nadu beach sands; Brazil; Sri Lanka |
| Gold | Bullion | Nome, Alaska |
| Magnetite (iron sands) | Iron | Volcanic coasts of the Pacific (Japan, New Zealand) |
- Sand and gravel are the bulk sea-bed resource by tonnage, dredged for construction and beach nourishment off the UK, the Netherlands and Japan.
- Lime shell and calcareous sands (off Gujarat) feed cement plants.
- Phosphorites form as nodules and crusts on the outer shelf and upper slope beneath upwelling zones, as off Namibia, Peru and California. Few are mined.
- The Challenger voyage of 1872–76 first dredged sea-floor phosphorite, from South Africa’s Agulhas Bank. It occurs mostly at depths under 500 m, between 40°N and 40°S.
- In the Indian Ocean it lies along the Arabian coast, India’s east coast, near the Andaman and Nicobar Islands and south of Sri Lanka. The Peruvian coast adds calcareous deposits to its phosphate.
- Sulphur occurs in salt domes under the Gulf of Mexico shelf, and around submarine volcanoes.
Deep-sea floor
| Deposit | Setting and depth | Metals | Formation | Main areas |
|---|---|---|---|---|
| Polymetallic (manganese) nodules | Abyssal plains, 4,000–6,000 m | Manganese, iron, nickel, copper, cobalt | Slow precipitation round a nucleus, a few mm per million years | Clarion–Clipperton Zone (Pacific); Central Indian Ocean Basin |
| Cobalt-rich ferromanganese crusts | Flanks of seamounts and guyots, about 800–2,500 m | Cobalt, manganese, nickel, platinum, rare earths | Precipitation on bare rock swept clean by currents | Western Pacific seamounts; Afanasy Nikitin Seamount (Indian Ocean) |
| Polymetallic sulphides | Mid-ocean ridges and back-arc basins, about 1,000–4,000 m | Copper, zinc, lead, gold, silver | Hot vent fluids meet cold sea water (black smokers) | Mid-Atlantic Ridge; Central, South-West Indian and Carlsberg Ridges; western Pacific |
| Metalliferous muds | Hot-brine deeps | Zinc, copper, silver | Brines rising through young rift | Atlantis II Deep, Red Sea |
- Nodules are potato-sized and lie loose on the sediment of the abyssal plains. Manganese and iron make up most of their weight, and nickel, copper and cobalt together only about 2.5–3%.
- They also hold traces of lead and zinc. The Challenger voyage of 1872–76 first found them, and systematic study began in the late 1950s.
- The main technical hurdle is recovering them without lifting the sediment beneath, from depths of over 4,000 m.
- The Clarion–Clipperton Zone (CCZ), between Hawaii and Mexico, covers about 4.5 million km². Its nodules are estimated to hold more nickel and cobalt than all known land reserves.
- The Blake Plateau off the south-eastern USA is another nodule field, at shallower depth.
Deep-sea mining
The legal regime
- Part XI of UNCLOS declares the Area and its minerals the common heritage of mankind. The International Seabed Authority (ISA), set up in 1994 at Kingston, Jamaica, regulates all activity there.
- The ISA has issued more than 30 exploration contracts (for nodules, sulphides and crusts), but no exploitation contract, because the exploitation regulations (the “Mining Code“) are unfinished.
- In 2021 Nauru triggered the “two-year rule” of the 1994 Implementing Agreement, demanding rules by July 2023. The deadline passed without them.
The 2025–26 regime debate
- ISA Council, 2025–26: the Council again failed to adopt the Mining Code at its 30th (2025) and 31st (March and July 2026) sessions.
- In July 2026 it asked for a roadmap, a list of outstanding issues and an advanced negotiating text for the 32nd session in 2027.
- It also extended three exploration contracts, including that of Nauru Ocean Resources Inc. (NORI), a subsidiary of The Metals Company, while a compliance inquiry into contractors continued. India’s Mayank Joshi presided over the Council in 2026.
- By July 2026, 46 countries had called for a moratorium or precautionary pause.
- The US unilateral move: the United States has never ratified UNCLOS.
- An executive order of 24 April 2025, Unleashing America’s Offshore Critical Minerals and Resources, directed the National Oceanic and Atmospheric Administration (NOAA) to speed up permits under the Deep Seabed Hard Mineral Resources Act of 1980, a law that bypasses the ISA.
- A NOAA rule effective 21 January 2026 let firms apply for exploration and commercial recovery in a single consolidated application.
- The Metals Company (TMC): its US arm applied in April 2025 for a commercial recovery permit in the CCZ.
- It filed a consolidated application on 6 February 2026, covering about 65,000 km².
- NOAA found the application in full compliance with information requirements in August 2026. Its public comment period closed on 19 October 2026.
- No permit has been issued. Certification and an environmental impact statement must come first.
- ISA members and many scientists regard such permits as a breach of the common-heritage principle.
- National waters: Norway opened part of its shelf to exploration in 2024, but in December 2025 it paused licensing until the end of 2029.
Benefits and risks
| Benefits | Risks |
|---|---|
| Critical minerals for batteries, grids and electronics (nickel, cobalt, copper, manganese, rare earths) | Permanent habitat loss: nodules are the only hard surface on the abyssal plain and take millions of years to regrow |
| Diversified supply: land cobalt is concentrated in the DR Congo and nickel in Indonesia | Sediment plumes from collectors and discharge smother life far beyond the mined strip and may cloud the mid-water food web of tuna |
| No overburden, blasting or displaced communities on land | Little-known biology: about 5,500 species have been recorded from the CCZ, nine in ten new to science; a 1979 test track was still scarred 44 years later (studies of 2023 and 2025) |
| Strategic and technological gains and deep-sea science | Noise, light and unknown functions, including carbon storage and the disputed “dark oxygen” made at nodule surfaces (2024) |
| Revenue sharing for developing states through the ISA | Governance gap: no binding code, and a parallel unilateral route |
India’s deep-sea programme
- India was the first country registered as a pioneer investor (1987) and has held a 75,000 km² nodule contract in the Central Indian Ocean Basin since 2002.
- An early allotment of 1,50,000 km² in the basin has since narrowed to the present contract. The National Institute of Oceanography, Goa, did much of the early survey work.
- It holds two sulphide contracts of 10,000 km² each:
- on the Central and South-West Indian Ridges (2016);
- on the Carlsberg Ridge (2025).
- It is the first state to hold two such contracts.
- Its application for cobalt crusts on the Afanasy Nikitin Seamount is pending, complicated by Sri Lanka’s overlapping continental-shelf claim.
- The Deep Ocean Mission (2021) of the Ministry of Earth Sciences covers mining technology, the crewed submersible Matsya-6000 (Samudrayaan, designed for 6,000 m, now in trials), biodiversity surveys and ocean-climate services.
- The vehicle carries three people and is built by the National Institute of Ocean Technology, Chennai. Targets set in early 2026 were a first dive to 500 m that year and the 6,000 m dive in 2027.
- Offshore blocks in India’s own EEZ:
- The first auction under the amended Offshore Areas Mineral Act (launched November 2024) offered 13 blocks: construction sand off Kerala, lime mud off Gujarat, and nodules and crusts off Great Nicobar.
- Fishers in Kerala protested against it.
- It was annulled in December 2025 for lack of bidders.
- A second attempt opened on 1 October 2026: two Andaman Sea blocks offered for composite licences, which cover both exploration and mining.
- The Offshore Areas Mineral (Auction) Amendment Rules of 24 September 2026 had cut the technically qualified bidders needed at a first attempt from three to two.
Energy resources
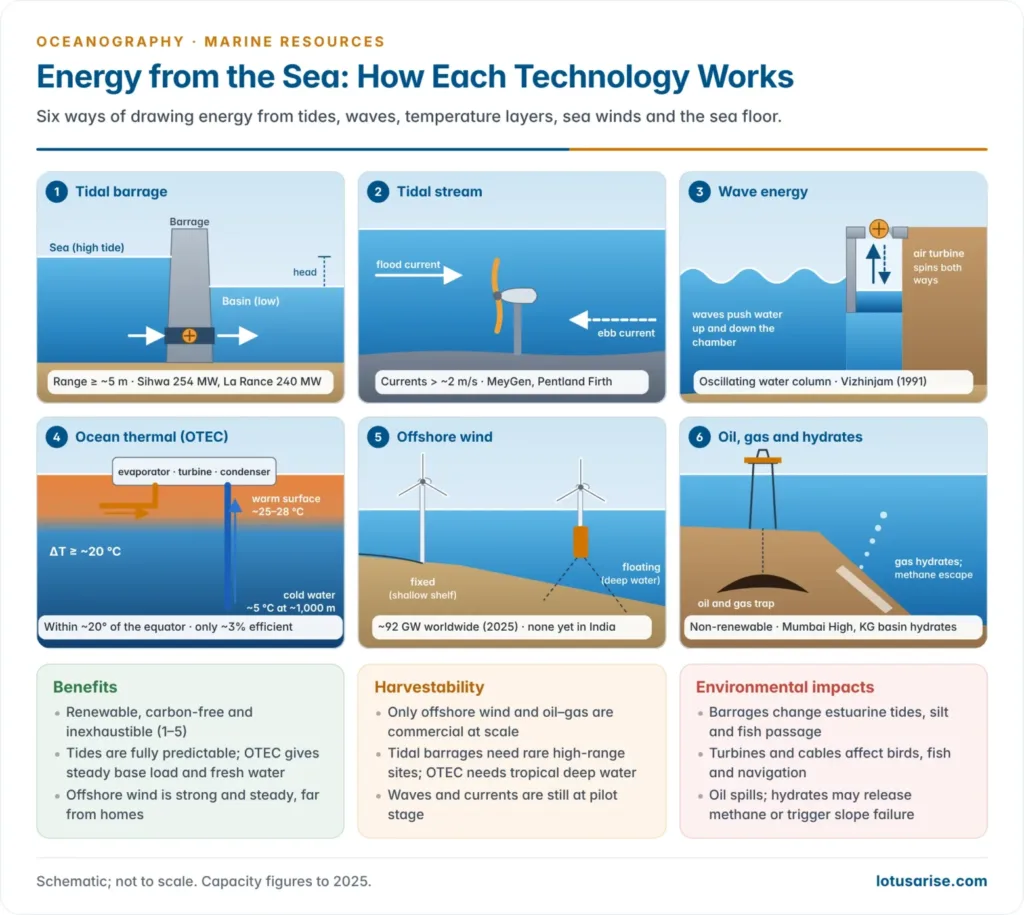
| Source | Principle | Conditions needed | Examples | Limits and impacts |
|---|---|---|---|---|
| Tidal barrage | Dam across an estuary; water runs turbines as tide rises and falls | Tidal range of about 5 m or more; narrow inlet | Sihwa Lake, South Korea (254 MW, 2011); La Rance, France (240 MW, 1966) | Few sites; costly; silting; blocks fish and alters estuary ecology |
| Tidal stream | Underwater rotors in fast tidal currents | Currents above about 2 m/s | MeyGen, Pentland Firth (Scotland) | Harsh conditions; small scale so far |
| Wave | Oscillating water column, floats or overtopping devices convert wave motion | Strong, steady swell (westerly coasts at 40–60°) | Mutriku breakwater (Spain); Vizhinjam pilot, Keralam (1991) | Storms damage devices; energy irregular; high cost |
| Ocean thermal (OTEC) | Warm surface water evaporates a working fluid (ammonia) or flashes sea water; cold deep water condenses it | Temperature difference of at least about 20 °C between surface and about 1,000 m, mostly within 20° of the equator | Georges Claude’s first plant, Cuba (1930); Kumejima, Okinawa (100 kW) | Efficiency only about 3%; huge pipes; costly; bonus of fresh water and nutrient-rich water |
| Offshore wind | Turbines on fixed foundations or floating platforms | Strong, steady winds; shallow shelves for fixed bases | About 92 GW installed worldwide by end-2025, led by China and the North Sea | Cost; grid links; bird, fish and navigation conflicts |
| Ocean currents | Turbines in steady currents | Strong permanent currents | Experiments in the Florida Current and Kuroshio | Experimental |
| Salinity gradient | Osmotic pressure where fresh and salt water meet | Large river mouths | Statkraft prototype, Norway (2009–13) | Membranes costly; experimental |
- How the main renewable forms behave:
- Wave output depends on wave height, speed, wavelength and water density, and the power often runs desalination plants and water pumps.
- Tidal turbines capture the kinetic motion of the tides in places with strong tidal movement.
- OTEC has low thermal efficiency because the temperature gap is small, which is what makes it hard to justify economically.
- Offshore wind gains from wind speeds that are stronger than on land.
- Non-renewable marine energy consists of offshore oil and gas and gas hydrates.
- Gas hydrates are methane trapped in ice-like crystal cages. They are stable under high pressure and low temperature in sediments of the continental slope, below a few hundred metres of water.
- Their total resource is very large but poorly known. Japan ran the first offshore production tests in the Nankai Trough (2013, 2017).
- India’s National Gas Hydrate Programme found rich hydrate-bearing sands in the Krishna–Godavari basin (NGHP-01, 2006; NGHP-02, 2015). Hydrates are also known off the Mahanadi and the Andamans.
- Risks: destabilising slopes and releasing methane, a powerful greenhouse gas.
- India has large tidal potential in the Gulfs of Khambhat and Kachchh and the Sundarbans, and offshore wind potential off Gujarat and Tamil Nadu, but no operating tidal or offshore wind plant.
- Estimates: tidal long stood at 8,000–9,000 MW and now at 12,455 MW identified; wave at 40,000 MW; ocean thermal at 50,000 MW in older work and 1,80,000 MW as the official theoretical figure.
- Older plans for a 900 MW tidal plant in the Gulf of Kachchh and a 100 MW ocean thermal plant off Tamil Nadu were never built.
- The first offshore wind tenders, backed by viability-gap funding for 1 GW, drew no bids and were cancelled in August 2025. A fresh Tamil Nadu tender is planned.
- The 150 kW Vizhinjam wave plant ran from 1991 until it was decommissioned in 2011. The Lakshadweep LTTD plants are now the main working step in ocean energy in India.
Blue Economy and Sustainable Use
The Blue Economy
- The Blue Economy is the sustainable use of ocean resources for growth, livelihoods and jobs while keeping ocean ecosystems healthy. Gunter Pauli popularised the term in his 2010 book The Blue Economy, and small island states pushed it at the Rio+20 summit (2012).
- Pauli’s full title was The Blue Economy: 10 Years, 100 Innovations, 100 Million Jobs.
- It seeks the greening of ocean development: higher productivity with conservation, joined to social inclusion and new business models.
- Its sectors: fisheries and aquaculture, shipping and ports, offshore energy, sea-bed minerals, coastal tourism, marine biotechnology, desalination, waste management on land, and blue carbon (mangroves, seagrass and salt marshes that store carbon).
- Sustainable Development Goal 14 (Life below Water) sets its targets.
- Why it matters:
- Oceans hold about 97% of the Earth’s water and about 99% of its living area, and they absorb a quarter to 30% of carbon dioxide emissions.
- Oceans yield an estimated 3–5% of world GDP, and the sector is often called the next sunrise sector.
- It offers food security and new sources of energy, drugs, chemicals, protein and deep-sea minerals.
- What threatens it:
- Sea-borne insecurity: piracy and armed robbery, maritime terrorism, illicit trade in crude and arms, and human and drug trafficking.
- Natural disasters: tsunamis, cyclones, hurricanes and typhoons strand people and destroy property.
- Man-made harm: oil spills, climate change, and changes in sea temperature and acidity that threaten habitats.
- Pollution and overuse: excess nutrients from sewage and farm run-off, plastic debris, and illegal or unregulated extraction.
- Recent global rules:
- The WTO Agreement on Fisheries Subsidies came into force on 15 September 2025, banning subsidies for illegal fishing and for fishing overfished stocks.
- The High Seas Treaty (BBNJ Agreement) came into force on 17 January 2026. It allows marine protected areas and benefit-sharing from marine genetic resources on the high seas.
- India signed it on 25 September 2024. In December 2025 it was still shaping the domestic framework needed for ratification.
Ecological problems of exploitation
- Overfishing: fleets are too large and too heavily subsidised. Fishing down the food web removes the large predators first. Examples are the collapse of Grand Banks cod and stress on tuna and sharks.
- Destructive gear:
- bottom trawling scrapes up sea-bed habitats;
- bycatch kills turtles, dolphins, sharks and juvenile fish;
- lost “ghost nets” go on fishing for years.
- Illegal, unreported and unregulated (IUU) fishing undermines quotas, especially in poorly patrolled waters off West Africa and in the Indian Ocean.
- Habitat loss: mangroves are cleared for shrimp ponds and ports, reefs are mined for lime or blasted, and estuaries are reclaimed. These are the nurseries of most coastal fish.
- Mining and drilling: oil spills and blowouts (Deepwater Horizon, 2010); sand dredging and coastal erosion; and the plumes and habitat loss of deep-sea mining.
- Energy works: barrages change estuarine tides and salinity, and wind farms affect birds and shipping.
- Pollution and climate change degrade the resource base itself:
- nutrient run-off creates dead zones;
- plastics and heavy metals enter food chains;
- warming bleaches reefs and shifts fish poleward;
- acidification weakens shellfish.
- Management responses:
- catch quotas based on maximum sustainable yield;
- closed seasons, such as India’s monsoon fishing ban of 61 days on each coast;
- mesh-size and gear rules;
- marine protected areas;
- ecosystem-based and community co-management;
- satellite vessel monitoring and the FAO Port State Measures Agreement against IUU fishing;
- environmental impact assessment for mining and energy projects.
India’s marine resources and Blue Economy
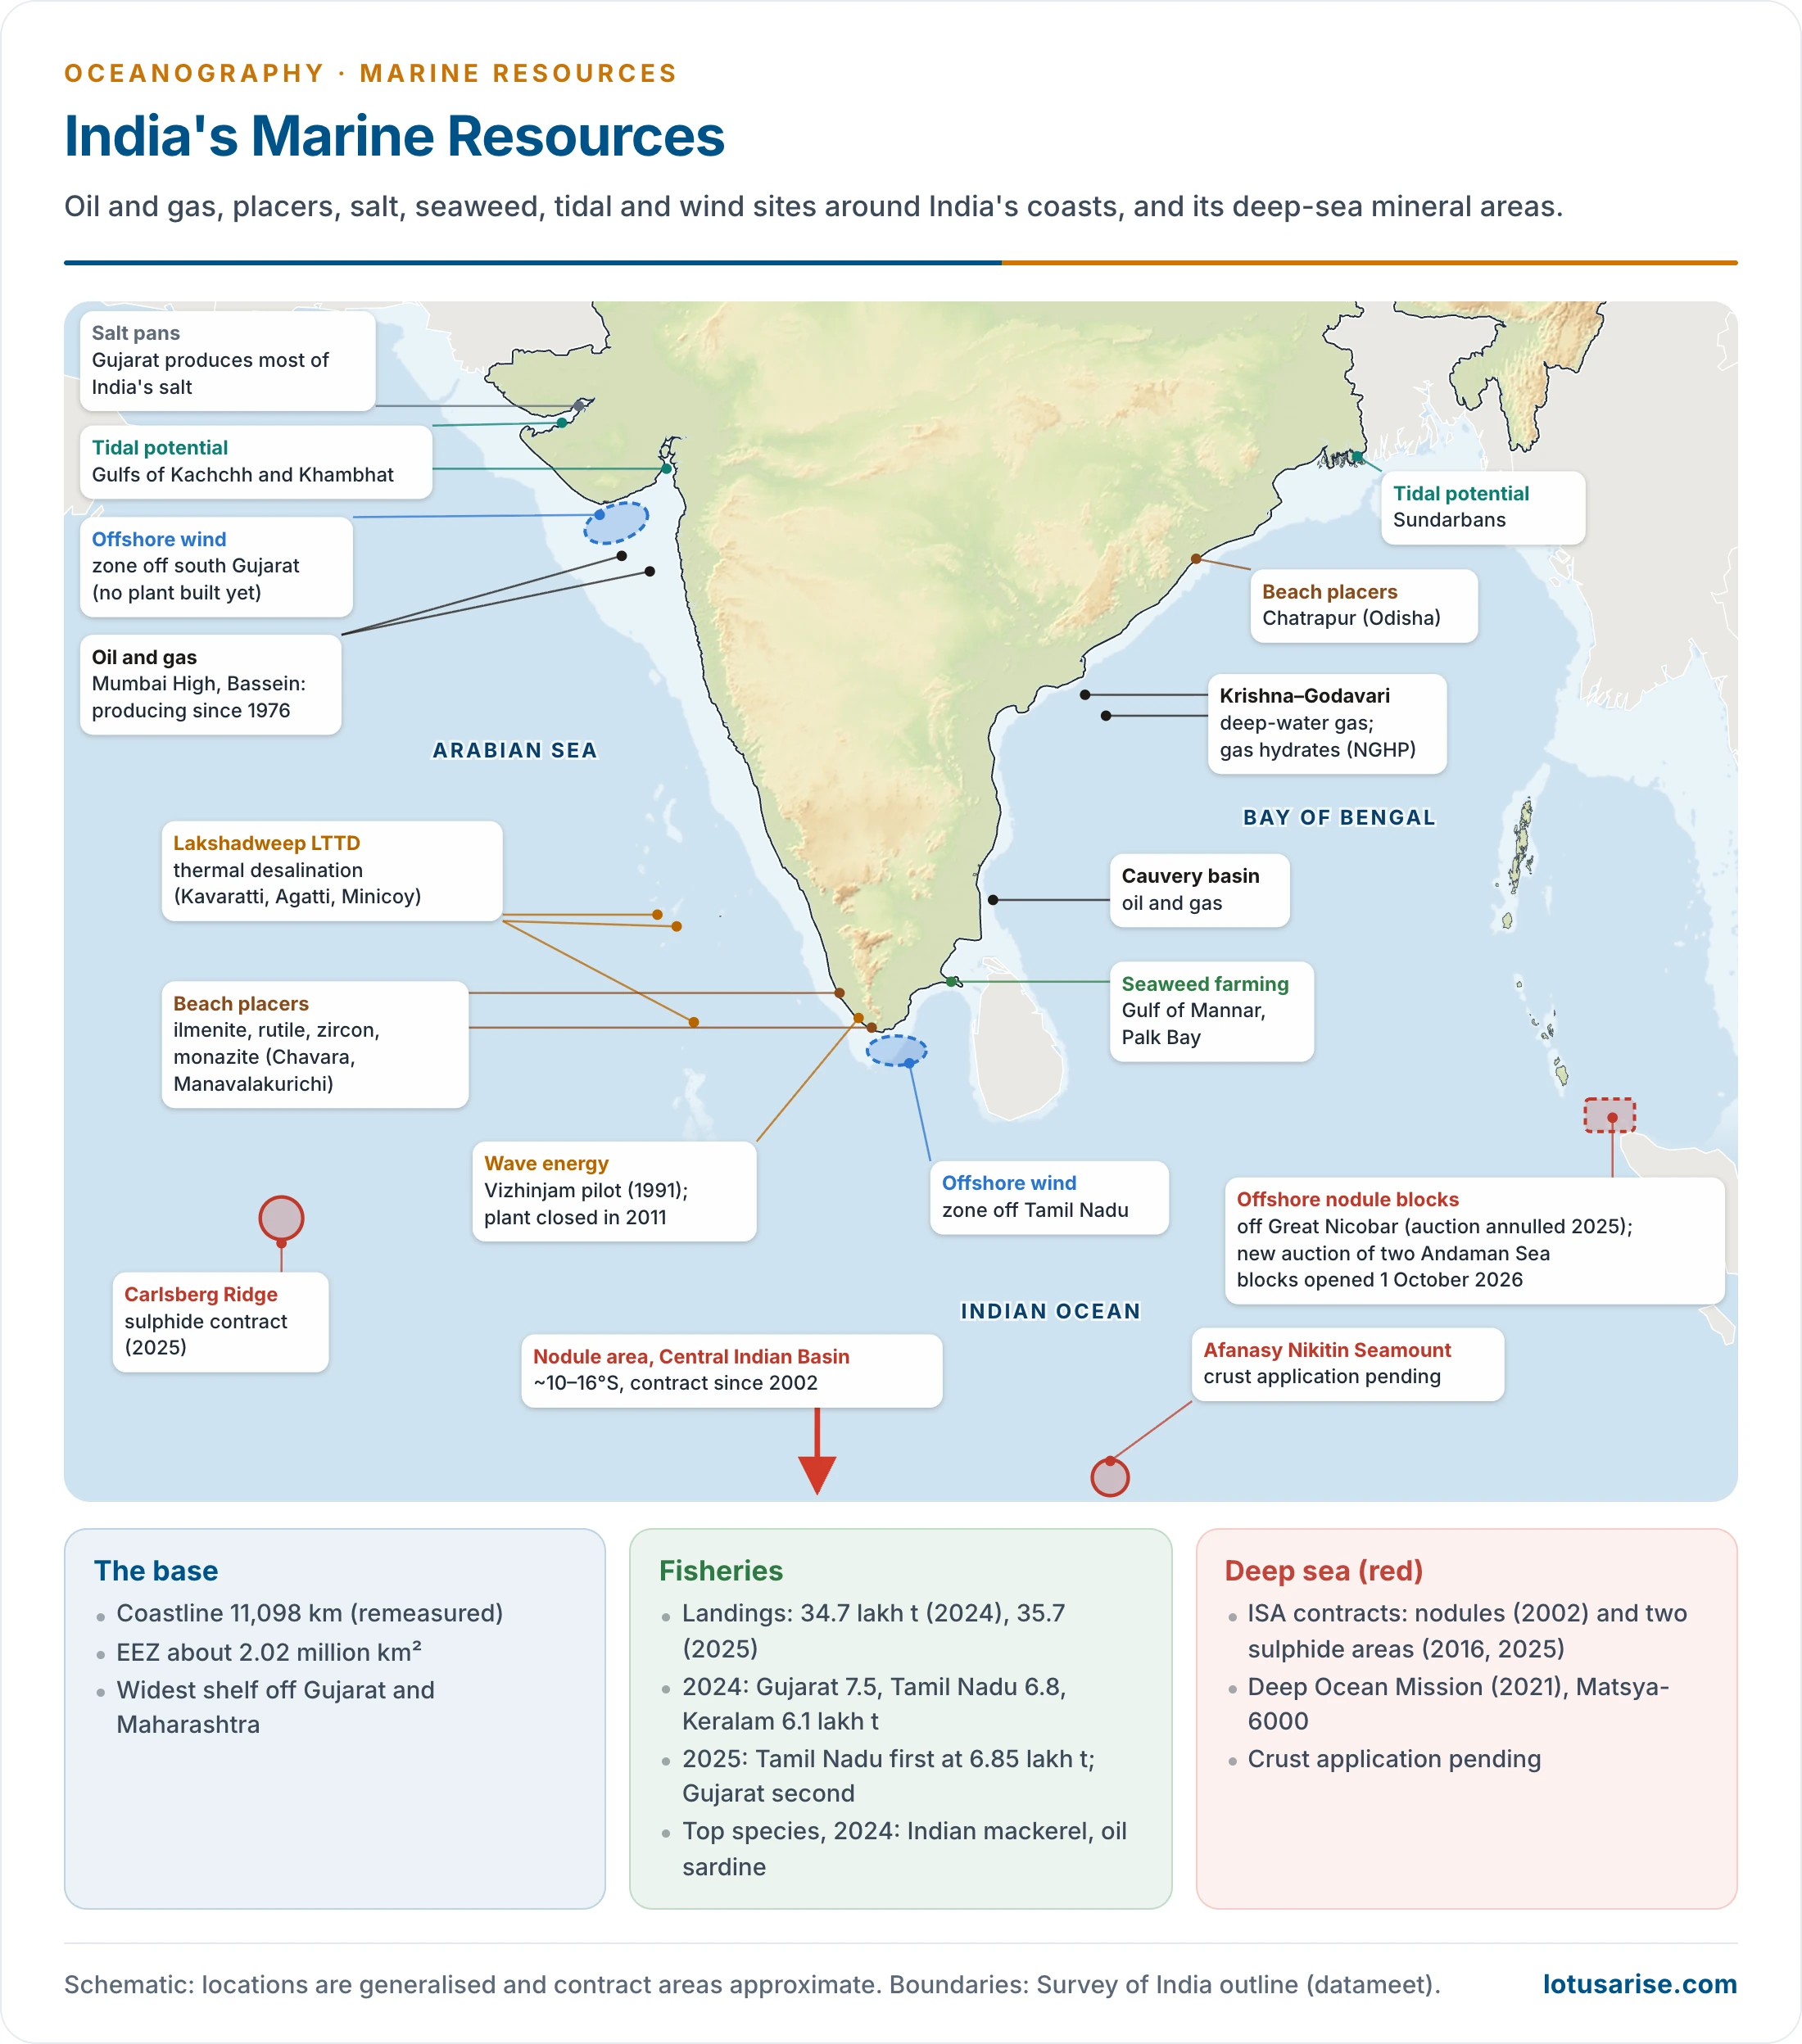
- The base:
- a coastline long given as 7,516.6 km and re-assessed in 2025 at 11,098.81 km, running through 13 States and Union Territories (an older count gave nine States and two Union Territories);
- an EEZ of about 2.02 million km², given as about 24 lakh sq km in a 2026 government statement, of which the Andaman and Nicobar Islands supply about 6 lakh sq km;
- a continental shelf of about 0.5 million km² (0.31 million km² in another count);
- a claim to an extended continental shelf beyond 200 nautical miles, lodged with the UN commission.
- Fisheries:
- India is the second largest producer of fish and of aquaculture in the world, with total production of about 197.75 lakh tonnes in 2024–25. About three-quarters of this now comes from inland waters and farms.
- Marine landings were about 34.7 lakh tonnes in 2024, led by Gujarat (7.54 lakh tonnes), Tamil Nadu (6.79) and Keralam (6.10); Indian mackerel and oil sardine were the top species.
- In 2025 landings rose 3% to 35.7 lakh tonnes (Central Marine Fisheries Research Institute, released 30 April 2026).
- Tamil Nadu took first place at 6.85 lakh tonnes. Gujarat fell about 15% to second, and Keralam stayed third.
- Indian mackerel (2.70 lakh tonnes) led, followed by cephalopods (2.57) and oil sardine (2.53). Pelagic fish made up 54% of the catch.
- Landings were worth about ₹69,254 crore at landing centres.
- The Department of Fisheries, on its own count, gives marine production of about 46 lakh tonnes for 2024-25.
- The estimated sustainable marine potential of the EEZ is about 5.3 million tonnes, against older estimates as high as 20–25 million tonnes. Inshore waters are fully fished, so growth lies in deep-sea tuna, mariculture and better post-harvest handling.
- The west coast lands most of the catch: about three-quarters in older accounts and about 62.5% in 2024, thanks to its wider shelf and the monsoon upwelling off Keralam and Karnataka.
- Why the deep-sea catch stays low: the Blue Revolution has come mostly from inland farms, while sea fishing faces its own limits.
- Heat spoils fish fast, so freezing adds to its price, and the monsoon and cyclones make the season short.
- The coast has few of the gulfs and estuaries that shelter Norway’s fleets.
- Much of the fleet is small: about 60% of fishers in older counts used non-mechanised boats, keeping within about 10 km of the shore and 18 m of water.
- Landing, freezing, canning and market links are thin, and a large vegetarian population limits local demand.
- Institutions and rules:
- The Fishery Survey of India (Mumbai) assesses EEZ stocks, the Central Institute of Fisheries Nautical and Engineering Training (Kochi) trains crews, and the National Fisheries Development Board (Hyderabad, 2006) funds development.
- The harbour scheme has taken up 6 major and 62 minor harbours, with 194 landing centres.
- The Marine Fishing Policy of 2004 aimed at sustainable deep-sea fishing and security for artisanal fishers.
- The EEZ fishing rules of 4 November 2025 require an access pass for motorised vessels of 24 m and over, ban destructive and juvenile fishing, and focus on tuna around the Andaman and Nicobar and Lakshadweep islands.
- Minerals and energy:
- oil and gas from Mumbai High, the Krishna–Godavari and Cauvery basins;
- beach placers of ilmenite, rutile, zircon, garnet and monazite in Keralam, Tamil Nadu, Andhra Pradesh and Odisha, worked by Indian Rare Earths Limited;
- lime mud off Gujarat;
- gas hydrates in the Krishna–Godavari basin;
- deep-sea nodules and sulphides under ISA contracts.
- The economic significance of the Indian Ocean shelf lies in its oil and gas, placers, fisheries, salt and building sands, together with the sovereign rights the UNCLOS shelf regime gives over them.
- Aggregates: sand, gravel and shell, mined mainly on the shelves, are the largest offshore commodity by quantity. Calcareous deposits feed cement plants.
- Placers: titanium sands off Sri Lanka, India and Australia, and tin off Malaysia and Indonesia, one of the main offshore placer areas in the world.
- Oil and gas: India, the Persian Gulf states, Indonesia, Malaysia and Western Australia lead. Small Gulf states gain most, since their land area is limited.
- Fisheries: the Indian Ocean has long been regarded as the least fished of the main oceans, though its tuna and inshore stocks are now under pressure.
- Rivalry: this wealth adds to the contest described in the geopolitics of the Indian Ocean.
- Trade: a large part of the world’s seaborne oil crosses this ocean, so better regional connectivity cuts transport costs and waste.
- Policies:
- Sagarmala (2015) for port-led development, modernised with IT-enabled services, with inland waterways, coastal shipping and Coastal Economic Zones (CEZ) where sea-dependent industry and townships cluster;
- the Pradhan Mantri Matsya Sampada Yojana (2020) for fisheries, the core of the Blue Revolution;
- O-SMART, an umbrella scheme for ocean services, technology and regulated use of the sea;
- the Deep Ocean Mission (2021);
- the draft Blue Economy Policy (2021);
- Integrated Coastal Zone Management, for conservation and coastal livelihoods;
- the national fisheries policy’s Blue Growth Initiative, for sustainable use of fisheries wealth;
- SAGAR (2015), widened to MAHASAGAR (2025), for maritime cooperation in the Indian Ocean.
- National aims: the Blue Economy serves livelihoods, energy security, ecological resilience and the 2030 goals on hunger and poverty. Marine services were cast as a backbone of the drive to a $5 trillion economy, a target first set for 2025; GDP for 2026 is about $4.06 trillion (IMF, October 2026).
- Challenges:
- an ageing, small-boat fishing fleet and post-harvest losses;
- conflict over fishing rights in the Palk Bay with Sri Lanka;
- mangrove and coastal-erosion pressures;
- pollution off industrial coasts;
- weak deep-sea technology;
- the vulnerability of the island territories to cyclones and sea-level rise.
- the contest over the Great Nicobar port and township between strategic aims and ecology and tribal rights. The National Green Tribunal declined to interfere with its environmental clearance in February 2026, and a forest-clearance challenge was pending before the Calcutta High Court in late 2026.
Previous Year Questions
2025What is deep-sea mining? What are the potential benefits and risks associated with it?2025Examine the validity of the Blue Economy initiatives of India. Elaborate the impacts of this economy on the country’s development.2023What is ocean ranching? How are aqua-cowboys related to such activities?2023Give an account of marine resources and their economic significance. How has marine pollution affected such resources?2020Marine resources are economically very significant. Discuss citing suitable examples.2018Describe the potential marine energy resources with reference to their benefits, harvestability and environmental impacts.2016Bring out the various ecological problems associated with the exploitation and use of oceans and their resources.2013Analyse the reasons for a comparatively poorer development of fishing grounds in tropical areas.2011Give an account of potentiality and prospects of development of marine resources of India.2009Examine economic significance of the resource of the Continental shelf of the Indian Ocean.1997Write short note: Marine resources, biotic mineral and energy resources.1995Write short note: Food from the sea.1993Critically examine the marine resources of India and discuss the problems encountered in their development.1986Give an account of marine resources and discuss their present-day utilization.





Great content
Your notes are really helpful .Thank you Sir
Keep Reading
Superb content..for upsc as well as state pcs..thank you..keep posting..
Beautifully written
Very helpful content for civil service aspirants
Is this sufficient for gs1
Yes, of course Khushi.
Concise and informative
thank you
जितनी प्रशंसा करू, कम है 😄😇
Sir , now change the coastal area length.
Where is pelagic deposits notes ?